
Why Is NEXON (TSE:3659) Drawing Fresh Attention Today?
NEXON (TSE:3659) has put a special dividend front and center, with the Board approving a ¥415.00 per share payout funded from retained earnings, tied to a September 30, 2026 record date.
Against this backdrop, NEXON’s share price has climbed 48.65% over the past 90 days even though the year to date share price return is down 20.54%. Long term total shareholder returns of 25.84% over three years and 83.93% over five years suggest momentum has been rebuilding from a lower base.
Scan how NEXON's special dividend compares by sizing it up against hand picked income plays in the 14 dividend fortresses list.
NEXON’s share price has raced ahead of both its analyst price target and one intrinsic value estimate. The real question is whether the new special dividend justifies that premium or stretches fair value too far.
Most Popular Narrative: 12% Undervalued
On the most followed narrative, NEXON’s fair value of ¥3,600 sits above the last close at ¥3,176, which puts the new special dividend into the context of a stock already priced above one intrinsic value model yet still below this higher fair value estimate.
Analyst consensus believes international expansion, especially for Dungeon & Fighter and MapleStory, will drive growth, but this may be understated: with sustained triple-digit growth in Korea and breakthrough performances in China and Western markets, Nexon's core franchises are positioned to achieve not just incremental, but potentially exponential user and revenue growth, with higher-than-expected net margins as scale efficiencies are realized.
See why 1 investors see NEXON as 12% undervalued.
This storyline pairs that ¥3,600 fair value with a 6.98% discount rate and assumes revenue growth of 5.88% and a net margin near 21.52%, so it leans on modest top line expansion and still healthy profitability rather than a dramatic upturn. It also leans on a higher future P/E of roughly 25x for NEXON than the current 18.5x, which implies investors would accept paying a richer multiple for earnings if those franchise and pipeline assumptions hold.
Under that framework, the current share price already exceeds one discounted cash flow estimate of ¥2,734.26 but still trails the higher narrative fair value, which shows how sensitive valuation can be to assumptions about long term earnings and required returns. Against a special dividend of ¥415 per share and regular dividends that now total ¥30 per share, readers can weigh whether the combined income and buyback activity align with those earnings and growth expectations or simply pull future returns forward.
Result: Fair Value of ¥3,600 (UNDERVALUED)
Still, the bullish NEXON narrative faces two obvious threats: if new titles underperform expectations, or if regulators tighten rules on in game monetization in key markets.
Find out about the key risks to this NEXON narrative.
Another View On NEXON’s Valuation
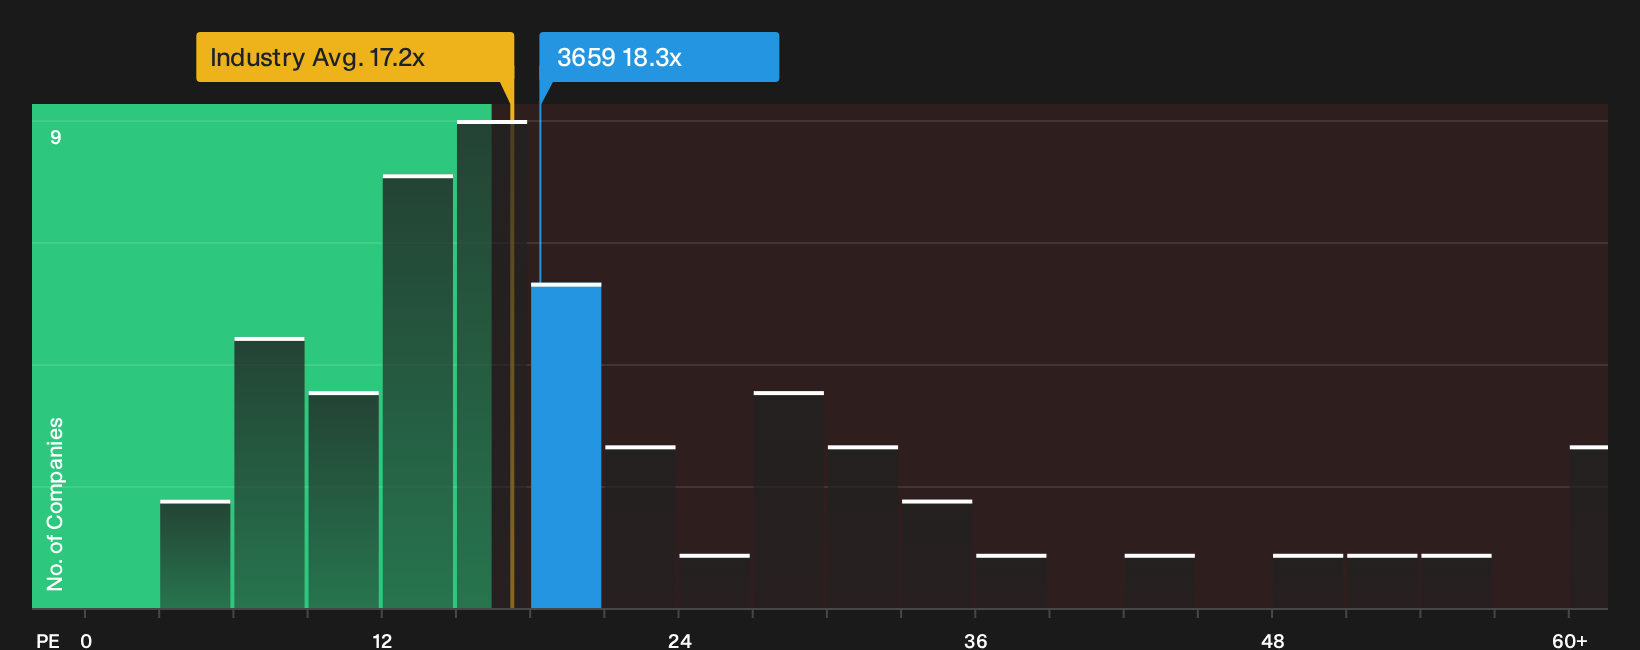
The story changes when you look at NEXON through its P/E. The shares trade on 18.5x earnings, which is higher than the JP Entertainment industry at 17.2x, yet below a peer average of 25.4x and under an estimated fair ratio of 22.6x. That mix points to both a quality premium and some room for sentiment to cool or warm, so how comfortable are you with that trade off?
For a closer look at how this earnings multiple stacks up against the assumptions behind it, including risks and peer comparisons, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and hesitation around NEXON feels familiar, treat it as your cue to move quickly and evaluate the numbers yourself. A balanced view means weighing both sides, so start by checking the 1 key reward and 3 important warning signs.
Looking for more NEXON sized ideas?
If NEXON has you thinking harder about where the next opportunity comes from, use this as a prompt to widen your net before the crowd catches up.
- Target dependable payouts by lining up NEXON’s income profile against a curated group of high yield candidates with the 14 dividend fortresses.
- Hunt for quality at a discount and compare NEXON against businesses that combine sturdy balance sheets with compressed valuations using the 17 high quality undervalued stocks.
- Spot tomorrow’s potential market leaders early by scanning a focused 75 high quality undiscovered gems before wider attention pushes prices higher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com