
Construction Partners (ROAD) Dropped, So What Is Behind The Latest Attention?
Construction Partners (ROAD) has completed its purchase of Roads, Inc. of NWF, adding a hot mix asphalt plant in Cantonment, Florida. This deal broadens the contractor's reach across the Florida Panhandle and neighboring markets.
The Roads, Inc. deal lands at a tricky moment for Construction Partners, with the share price down 13.87% over the past 30 days and 25.72% over 90 days. However, the 3-year total shareholder return of 156.42% and 5-year total shareholder return of 172.02% still point to a strong longer-term story.
Scan beyond Construction Partners and explore other infrastructure contractors that are under pressure or quietly compounding with our hand picked list of solid balance sheet and fundamentals (23 results)
Construction Partners looks like a solid operator with growing scale, yet the share price has slid sharply in recent months. So is a quality road builder now on sale or still fully charged?
Most Popular Narrative: 36% Undervalued
On the most followed view, Construction Partners screens as undervalued, with a fair value of $145 against a last close of $93.44, which puts the recent share price slide in a very different light for anyone focused on long term cash flows.
Ongoing vertical integration, through investment in owned asphalt plants and material sourcing, combined with increasing scale, is already associated with enhanced operational efficiencies and margin expansion, as shown by record adjusted EBITDA margins despite weather disruptions. This is expected to support higher net margins and earnings resilience over time.
See why 7 investors see Construction Partners as 36% undervalued.
Result: Fair Value of $145 (UNDERVALUED)
Still, the Construction Partners story can change quickly if public infrastructure budgets tighten or if weather and cost pressures hit project timing and profitability harder than analysts expect.
Find out about the key risks to this Construction Partners narrative.
Another View: Construction Partners Through The P/E Lens
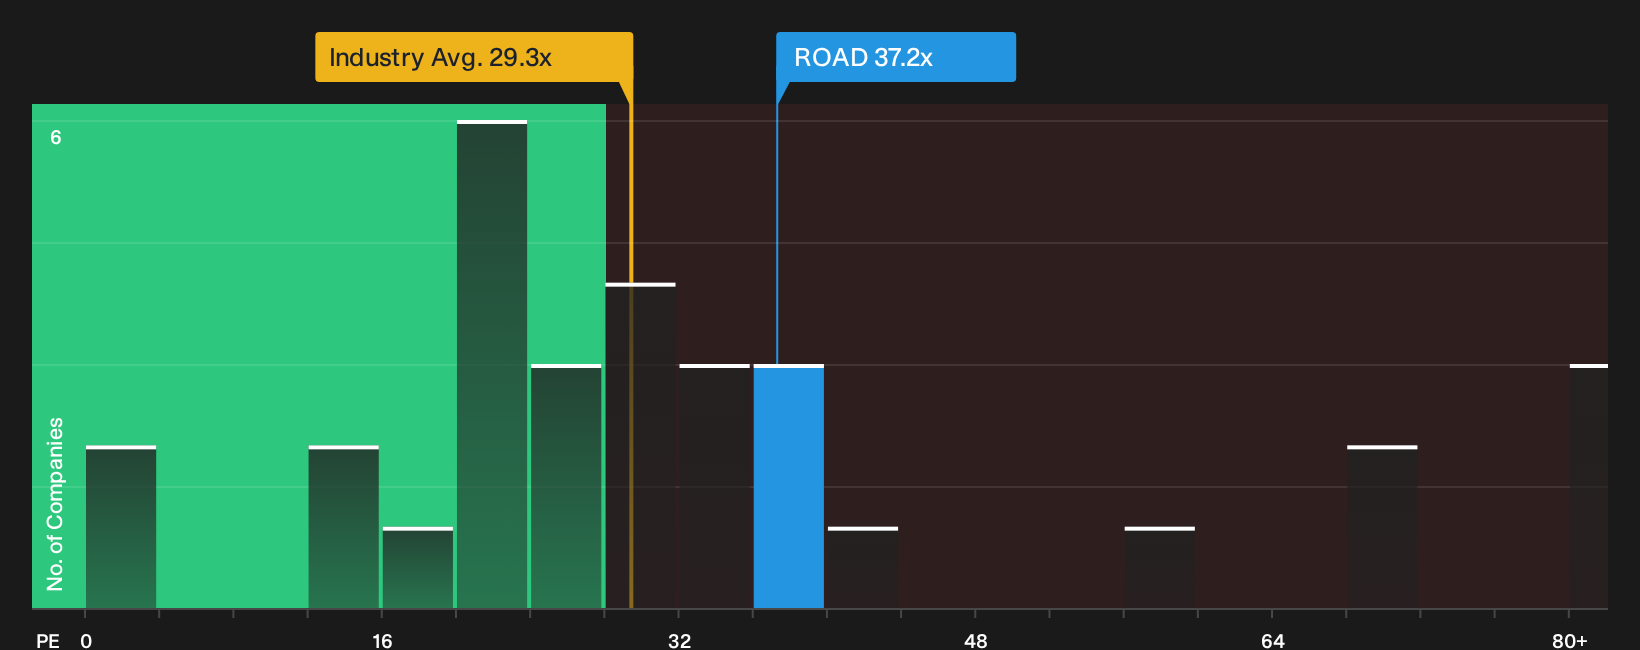
The SWS DCF model paints Construction Partners as undervalued, with the stock at $93.44 versus an estimated future cash flow value of $159.29. The P/E story is different. At 37.2x earnings, ROAD trades richer than the US Construction sector at 29.4x and above peers at 30x, even though the fair ratio sits at 39.7x. So is this a mispriced compounder or a premium that could compress if expectations cool?
For a deeper look at how this aligns or clashes with the cash flow view, including all the moving parts behind that fair value line, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Construction Partners is clearly mixed right now, so it may be helpful to act quickly and review the numbers yourself before the story changes again. To consider both potential drawbacks and opportunities in one place, review the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Construction Partners?
Do not stop with Construction Partners when there are dozens of other setups that could fit your style and time horizon.
- Target resilient balance sheets and steady fundamentals with a focused list of solid balance sheet and fundamentals (23 results) that filters out weaker candidates before you even start comparing.
- Hunt for potential mispricings by scanning a concentrated pool of 30 high quality undervalued stocks that combine quality metrics with compressed valuations.
- Prioritize durability and staying power by zeroing in on 31 resilient stocks with low risk scores that score well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com