
3 Utility Stocks For Steady Dividends When European Bond Risk Rises
French bond markets are flashing red, political risk premia are climbing and investors are rethinking how much turbulence their portfolios can handle. When funding costs jump and budgets tighten, reliable dividend payers with relatively muted price swings often move from background holdings to front-of-mind candidates. This article walks through three European dividend stocks from a defensive, low-volatility screener that appear closely tied to the current French risk story.
The stocks below are only a sample, and the full screen surfaced 12 more European defensive, low-volatility dividend plays with equally compelling stories that are not covered here. If you want to quickly identify and analyze which of these might deserve a closer look in your portfolio, head straight into the European defensive, low-volatility dividend stocks screener
A2A (BIT:A2A)
Overview: A2A is an Italian multi-utility based in Milan that supplies electricity, gas, district heating, water and waste services to households, businesses and municipalities.
Operations: A2A reports €10.4b from Generation and Trading, €7.6b from Market, €2.3b from Circular Economy, €1.2b from Smart Infrastructures and €0.4b from Corporate, with eliminations of €6.2b.
Market Cap: €7.2b
A2A fits the European defensive, low-volatility dividend theme as a regulated Italian utility. Its investment program gives the story extra punch when political risk pushes investors toward predictable cash flows.
"A2A's accelerated investment in electricity grids and smart infrastructure, following large-scale integration of Enel's assets and rapid CapEx deployment, supports its exposure to the ongoing electrification of cities and sectors.
What investors cannot ignore is how one unresolved pressure on funding costs and leverage could reshape the path for future margins.
That funding squeeze is exactly what the full narrative for A2A tackles, with the full narrative for A2A showing how its grid buildout and leverage story could be decoupling.

EnBW Energie Baden-Württemberg (XTRA:EBK)
Overview: EnBW Energie Baden-Württemberg is a German integrated utility that supplies power, gas, grids and energy services across Europe to households, businesses and public entities.
Operations: EnBW generates about €19.9b from Sustainable Generation Infrastructure, €13.5b from Smart Infrastructure for Customers and €9.4b from System Critical Infrastructure, with remaining amounts from other items and consolidation effects.
Market Cap: €22.1b
EnBW Energie Baden-Württemberg fits the European defensive, low-volatility dividend theme as a large German utility with regulated grids and diversified generation. However, its unprofitable earnings, weak dividend coverage and debt-dependent funding mean the income profile depends heavily on how one unresolved pressure on cash generation and balance sheet flexibility develops.
That funding strain is exactly what the EnBW Energie Baden-Württemberg financial health report unpacks, showing where balance sheet pressure might be masking future income resilience.

Naturgy Energy Group (BME:NTGY)
Overview: Naturgy Energy Group is a Spanish integrated gas and power utility that runs regulated networks and energy markets across multiple regions.
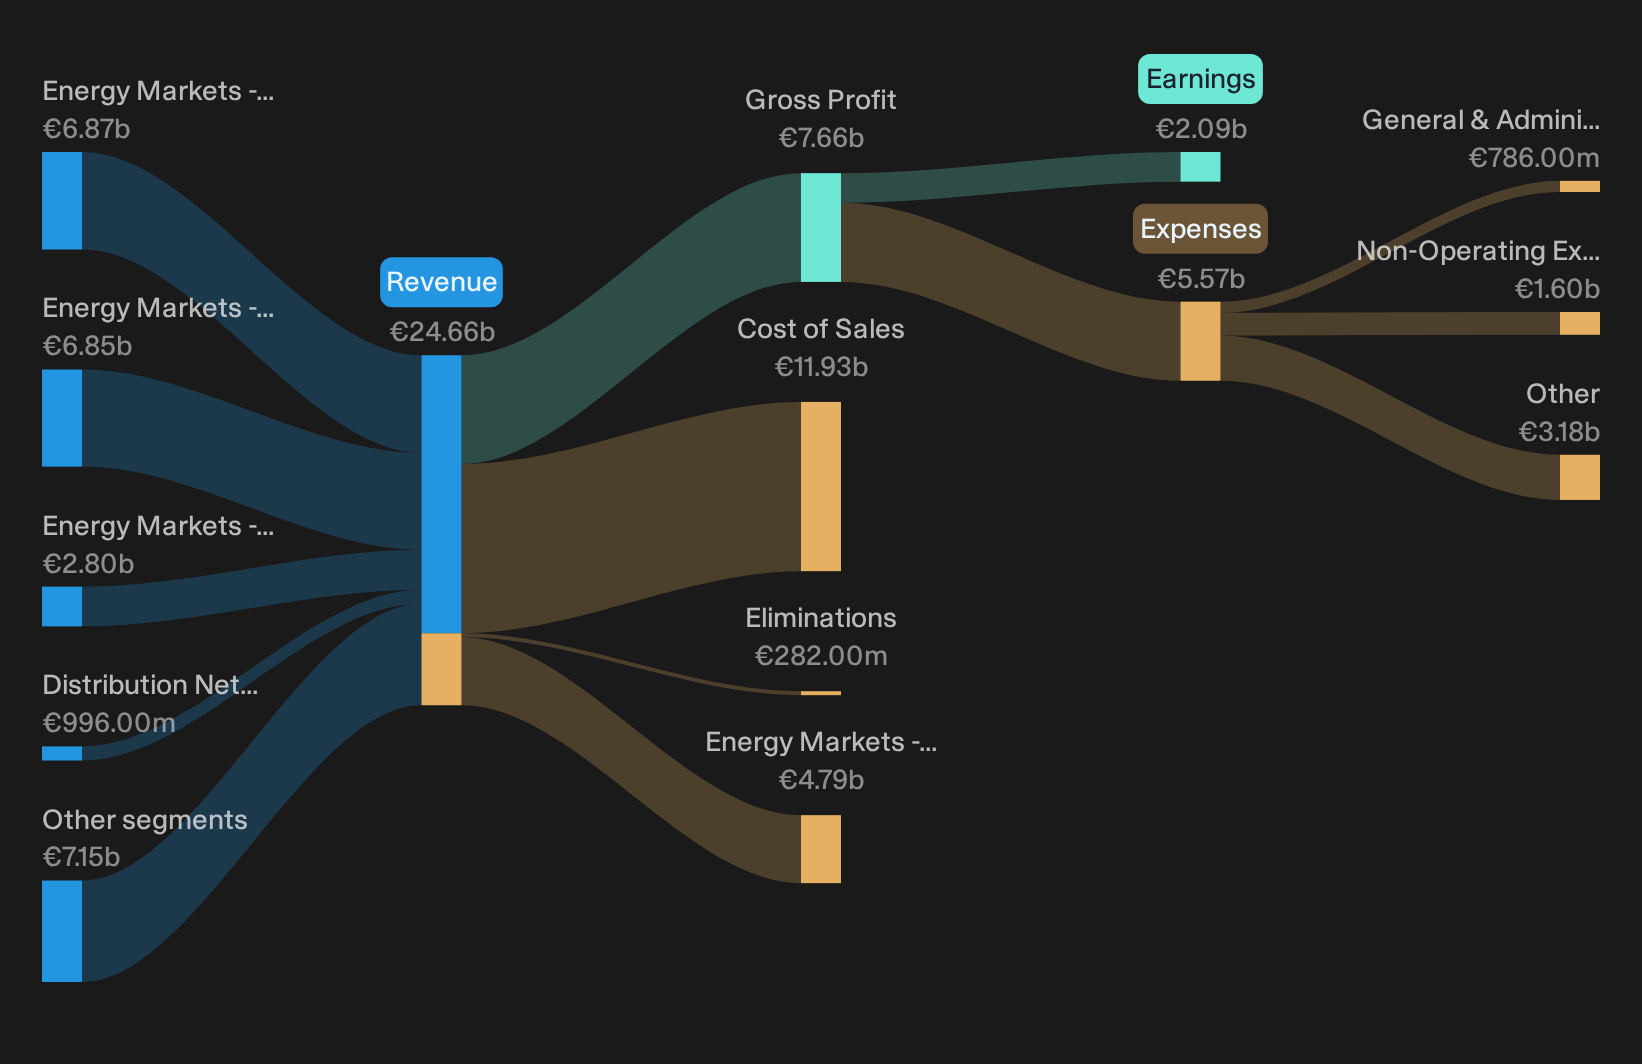
Operations: Naturgy Energy Group earns most revenue from Energy Markets activities around €17.5b, supported by roughly €5.3b from global gas and electricity distribution networks.
Market Cap: €27.1b
For a defensive dividend screen built around large, low beta utilities, Naturgy Energy Group brings a mix of regulated infrastructure and energy supply that can be relevant when bond volatility pushes investors toward steady cash flows.
"The current resilience of natural gas as a "transition fuel" in the energy mix and Naturgy's messaging that gas remains a critical part of decarbonization efforts may lull investors into underestimating longer-term regulatory headwinds or rapid renewable adoption that could diminish intrinsic demand for midstream gas infrastructure and supply in the coming decade."
What really matters for long term dividend comfort is how one slow burning shift in the policy and energy mix plays out from here.
That slow burning shift is exactly what the full narrative for Naturgy Energy Group unpacks, revealing where accelerating policy change and renewables could reshape Naturgy Energy Group's long term dividend potential.
Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum is flying, entry points can be gone. Scan curated lists while it matters and before they are fully caught. Act now.
- Spot resilient compounding potential in companies with strong balance sheets by running the list of solid balance sheet and fundamentals (198 results) before the rest of the market starts paying attention.
- Track where real earnings momentum meets AI adoption by scanning the 38 profitable AI stocks that aren't just burning cash while these cash generating stories stay under the radar for now.
- Pursue income strength with staying power by reviewing the curated 160 dividend fortresses before yield hunters crowd into the same set of dependable payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com