
Nidec (TSE:6594) Faces Activist Pressure, Is The Stock Expensive?
Oasis Management has gone public with an activist campaign at Nidec (TSE:6594), pushing for changes to the board, officer lineup, capital structure, potential asset sales, and future dividend policy.
Recent trading suggests growing interest in Nidec, with a 30-day share price return of 8.60% and an 11.29% gain over 90 days. The 35.28% year-to-date share price return contrasts with a much weaker 5-year total shareholder return that is down 52.66%.
Scan how activism pressure on Nidec compares with other industrial opportunities by reviewing our hand picked list of list of solid balance sheet and fundamentals (21 results) for ideas beyond this one situation.
Recent gains in Nidec now sit against a long stretch of weaker shareholder returns and fresh activist pressure. Are buyers reacting to a better underlying business or simply to a new story around it?
Most Popular Narrative: 9% Overvalued
Nidec last closed at ¥2,830, which sits above the most followed fair value estimate of ¥2,596 that is built on detailed cash flow and earnings assumptions. That gap puts the focus on whether the current activist push and R&D overhaul can justify paying more than the narrative fair value today.
Ongoing structural reforms targeting a ¥100 billion reduction in variable costs and ¥50 billion in fixed costs through business consolidation, site rationalization, and exit from low-margin segments are expected to materially improve operating margins and net profitability, especially into FY2027, supporting a rerating of the business.
See why 5 investors see Nidec as 9% overvalued.
Result: Fair Value of ¥2,596 (OVERVALUED)
Still, the Nidec story could shift quickly if internal control investigations deepen, or if the large restructuring push disrupts operations and weighs on earnings quality.
Find out about the key risks to this Nidec narrative.
Another View On Nidec’s Value
The cash flow lens tells a different story. While the narrative fair value pegs Nidec at ¥2,596 and flags the stock as 9% overvalued, the SWS DCF model estimates future cash flows at ¥3,720, with the shares trading about 23.2% below that level. Which yardstick do you trust more when activism is in the mix?
Look into how the SWS DCF model arrives at its fair value.
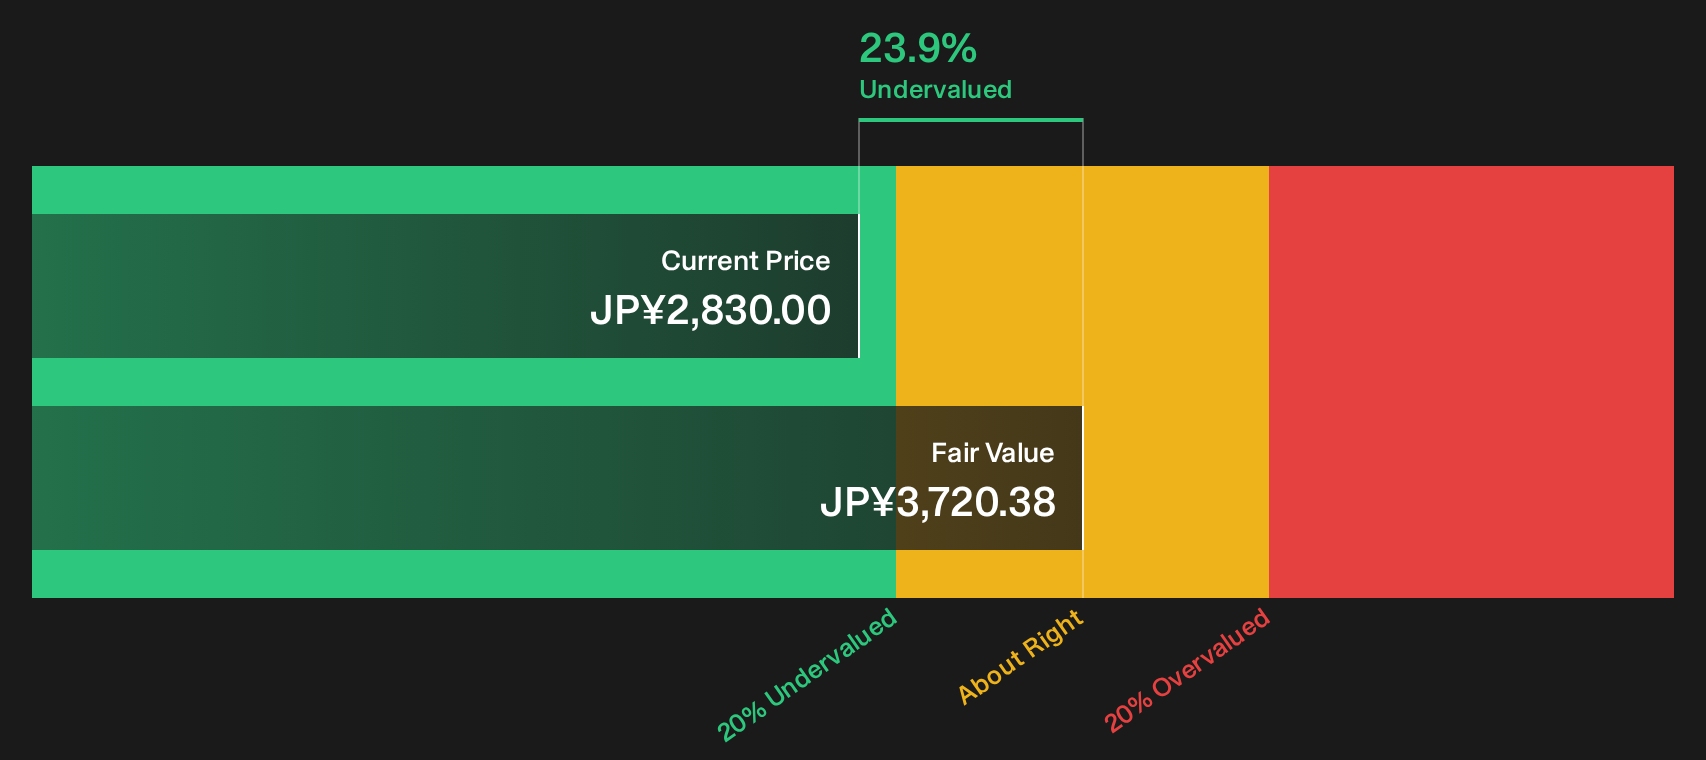
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nidec for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Nidec can pull sentiment in both directions, so move quickly, inspect the data for yourself, and weigh up the 3 key rewards and 1 important warning sign.
Looking for more Nidec investment ideas?
Do not stop with a single situation. Use the Simply Wall Street Screener to hunt for other opportunities that fit the way you like to invest.
- Target resilient income by focusing on businesses that pay you to wait through 14 dividend fortresses.
- Stack the odds toward quality by scanning for companies trading below intrinsic value with the 17 high quality undervalued stocks.
- Protect your downside first by filtering for financially robust candidates using the 21 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com