
Does August Traffic Growth Change The Bull Case For Transurban Group (ASX:TCL)?
- Transurban Group reported that average daily traffic across its toll road portfolio grew 3.4% in August 2026 compared with a year earlier, providing fresh operational detail on current road usage.
- The 3.4% ADT uplift indicates ongoing demand for Transurban Group’s existing roads, which is important when weighed against future project spending and rising maintenance obligations.
- We will now look at how Transurban Group’s investment narrative is affected by this 3.4% August traffic result and what it implies.
Scan how Transurban Group’s 3.4% August traffic result compares with other infrastructure backed companies by reviewing our hand picked list of solid balance sheet and fundamentals (12 results).
Transurban Group Investment Narrative Recap
To own Transurban Group, you need to be comfortable with a toll road operator that leans on resilient traffic and regulated pricing while carrying material debt and rising maintenance needs. The 3.4% ADT uplift in August signals steady road usage. On its own, this looks supportive rather than transformational for the near term story.
The key short term swing factor still sits around how well Transurban Group manages higher maintenance and interest costs as more assets move into heavier upkeep cycles. The biggest current risk is that operating expenses and funding costs rise faster than traffic and toll revenue, which could pressure margins even if volumes stay firm.
The August traffic update directly links to earlier commentary about almost A$13b of projects scheduled to open in the near term and another A$10b under active discussion. For that pipeline to work, you want to see existing roads handling healthy volumes. Stable ADT helps reinforce the case that new capacity could be absorbed rather than sit underused.
The same disclosure set also flagged cost discipline and digital investments that aim to keep operating expenses under control as the portfolio grows. When you put that next to the 3.4% ADT growth, the operational focus becomes clearer. Execution risk stays around whether Transurban Group can keep maintenance, financing and project delivery aligned with this traffic profile so that future earnings expectations remain credible.
Transurban Group's narrative projects A$4.4b revenue and A$772.8m earnings by 2029. This assumes 3.9% yearly revenue growth and an earnings increase of about A$294.8m from A$478.0m today.
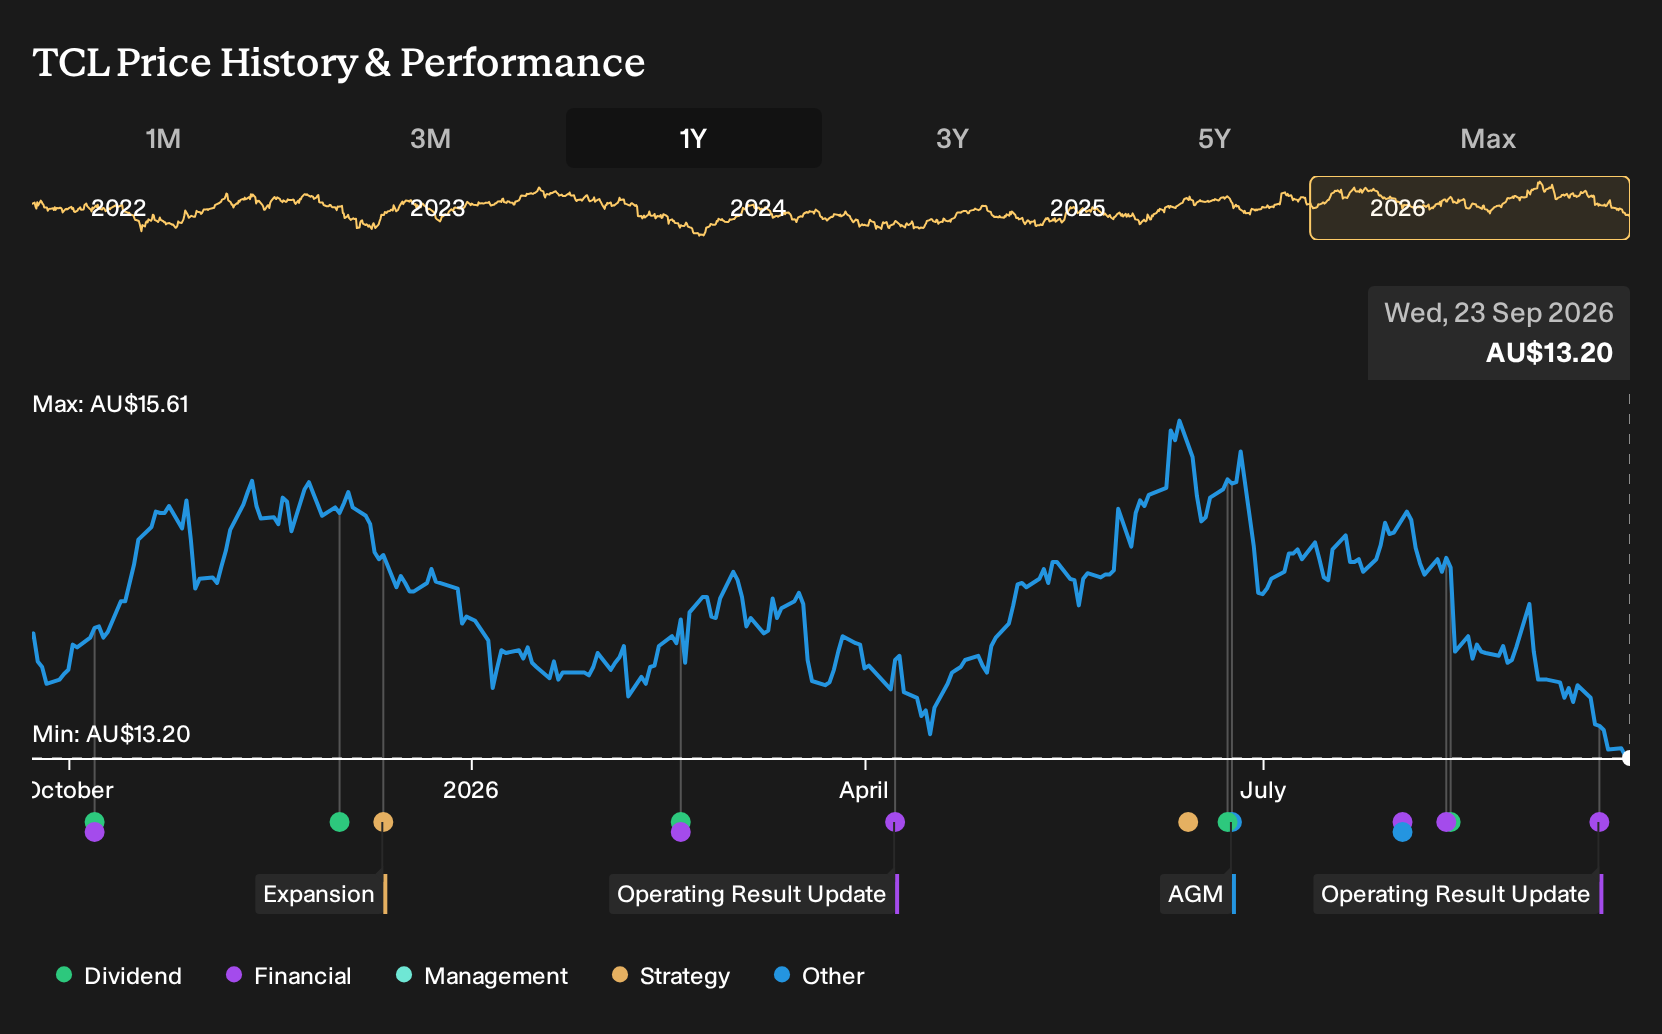
Uncover how Transurban Group's fair value indicates a 6% potential upside to its current price before that discount closes for Transurban Group.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between A$13.96 and A$19.52, so private investors are clearly not marching in lockstep on Transurban Group. These opinions were formed before the August ADT update, while rising maintenance, potential toll reform and higher funding costs all still hang over the story. Investors can review these contrasting viewpoints to test their own expectations for traffic, pricing and long term cash flows.
Explore 2 other Transurban Group fair value estimates, including one that suggests potential upside of as much as 48% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Transurban Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Transurban Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Transurban Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Transurban Group?
Once you have a view on Transurban Group, it can help to widen the lens and compare it with other listed businesses that fit different risk and return profiles. The Simply Wall St Screener lets you scan for opportunities that match your own checklist rather than someone else’s.
- If you want income potential backed by robust balance sheets, review a curated 3 dividend fortresses that combine higher yields with financial resilience.
- For those hunting for potential mispricing opportunities, survey a focused 6 high quality undervalued stocks that pair solid cash generation with what our models flag as discounted prices.
- When capital protection matters most, start with a hand picked 7 resilient stocks with low risk scores that score well on financial strength and business stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com