
McGrath RentCorp (MGRC) Raises Dividend And Capex, Is It Fully Priced?
McGrath RentCorp (MGRC) is back in focus after the board approved a quarterly cash dividend of $0.495 per share, along with higher capital expenditure guidance and rising rental operations revenue despite project timing delays.
The latest dividend decision and higher capital spending plans come after a mixed run for McGrath RentCorp’s stock. The 90 day share price return declined 8.17%, but the year to date share price gain of 7.61% and the 5 year total shareholder return of 69.58% point to longer term compounding. The recent portfolio addition by The London Company and ongoing dividend increases suggest that some investors view the recent share price softness as a reset in sentiment rather than a break in the longer story.
Spot opportunities with similar recurring revenue strength and dividend support by scanning our hand picked 30 high quality undervalued stocks that share key qualities with McGrath RentCorp’s model.McGrath RentCorp has pulled back after a long run and fresh dividend action, which leaves a simple puzzle for investors. Is this where most of the upside is already in the rear view mirror, or still ahead?
Price-to-Earnings of 18.1x: Is it justified?
On simple earnings terms, McGrath RentCorp trades on a P/E of 18.1x, which screens as cheaper than both its peer group on 45.9x and the wider US Trade Distributors space on 25x.
The P/E ratio compares the current share price to earnings per share and gives a quick read on how much investors are paying for each dollar of profit. For a rental focused business with relatively steady demand across classrooms, storage and test equipment, earnings based valuation is a common yardstick because cash generation and profit visibility matter as much as raw growth.
McGrath RentCorp’s earnings are forecast to grow 8.29% per year, and its SWS fair P/E estimate sits slightly lower at 17.3x. That combination points to a market that is not paying up aggressively for the forecast, and the current 18.1x ratio is only marginally above the level the market could move toward if sentiment cools or earnings deliver exactly as expected.
Compared with peers on 45.9x and the broader US Trade Distributors industry on 25x, the 18.1x multiple looks materially lower. Against the 17.3x estimated fair P/E, it looks a touch rich. This leaves McGrath RentCorp trading at a discount to sector enthusiasm but at a small premium to the modelled fair ratio.
Explore the SWS fair ratio for McGrath RentCorp.
Result: Price-to-Earnings of 18.1x (ABOUT RIGHT)
Still, the recent 1 year total return decline of 3.99% and exposure to project timing delays mean sentiment around McGrath RentCorp can shift quickly if contracts slip.
Find out about the key risks to this McGrath RentCorp narrative.
Another View: What The SWS DCF Model Says
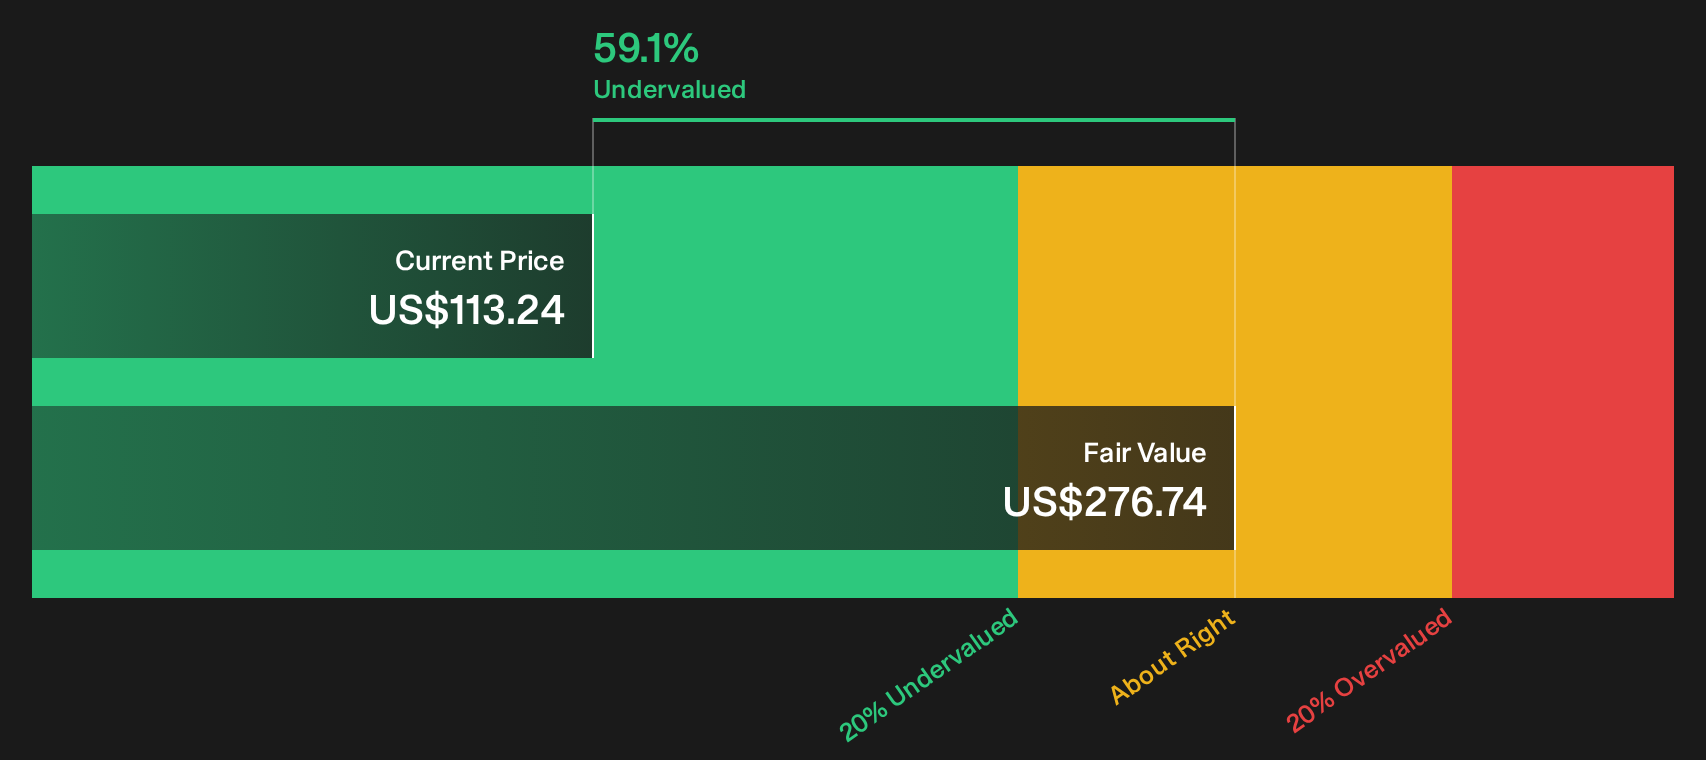
The P/E workup paints McGrath RentCorp as roughly fairly priced, yet the SWS DCF model points in a very different direction. On that framework, MGRC at $113.24 sits well below an estimated future cash flow value of $276.74. This frames a wide gap that investors need to explain.
That spread suggests the market might be putting a low weight on long term rental cash flows or pricing in higher risk around debt levels, project delays and softer recent returns. The question for anyone looking at McGrath RentCorp is simple: Are current worries overstated, or is the DCF model too optimistic about what those future dollars are worth?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out McGrath RentCorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a balanced setup, either way McGrath RentCorp gives you enough data on both risk and reward to form your own call quickly. To weigh that trade off directly, start with the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond McGrath RentCorp?
If McGrath RentCorp has sharpened your focus on quality and valuation, do not stop here. The next move could be finding similar or stronger setups.
- Target resilient balance sheets and steady fundamentals with a tailored list of solid balance sheet and fundamentals (23 results) that helps you focus on financially robust businesses before the crowd catches on.
- Hunt for quality at a reasonable price using the 30 high quality undervalued stocks and quickly line up candidates where fundamentals and valuation stay tightly aligned.
- Zero in on future potential by scanning a curated 16 high quality undiscovered gems and give yourself a chance to spot strength before it becomes obvious.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com