
Stride (LRN) Stock Could Trade At A Discount As Earnings Lead
Stride has delivered a powerful 5 year run, yet its recent pullback puts fresh focus on a simple question. Is the current share price still supported by the earnings behind the business.
- Stride has returned 123.9% over the past 5 years, which makes the link between its earnings power and today’s valuation especially important for anyone considering the stock at current levels.
- The company’s model of delivering education services at scale can influence how efficiently profits convert from revenue and how much of those earnings can be reinvested to support future cash generation.
- Your read on Stride is one view; the desks covering it have another. See what analysts think Stride's shares could be worth.
The stock’s next move may depend on whether its recent earnings justify where Stride is trading today.
If you want a broader earnings test beyond Stride, a focused screen of 30 high quality undervalued stocks is a useful next step for finding other ideas to research.
Does Stride Look Undervalued on Earnings?
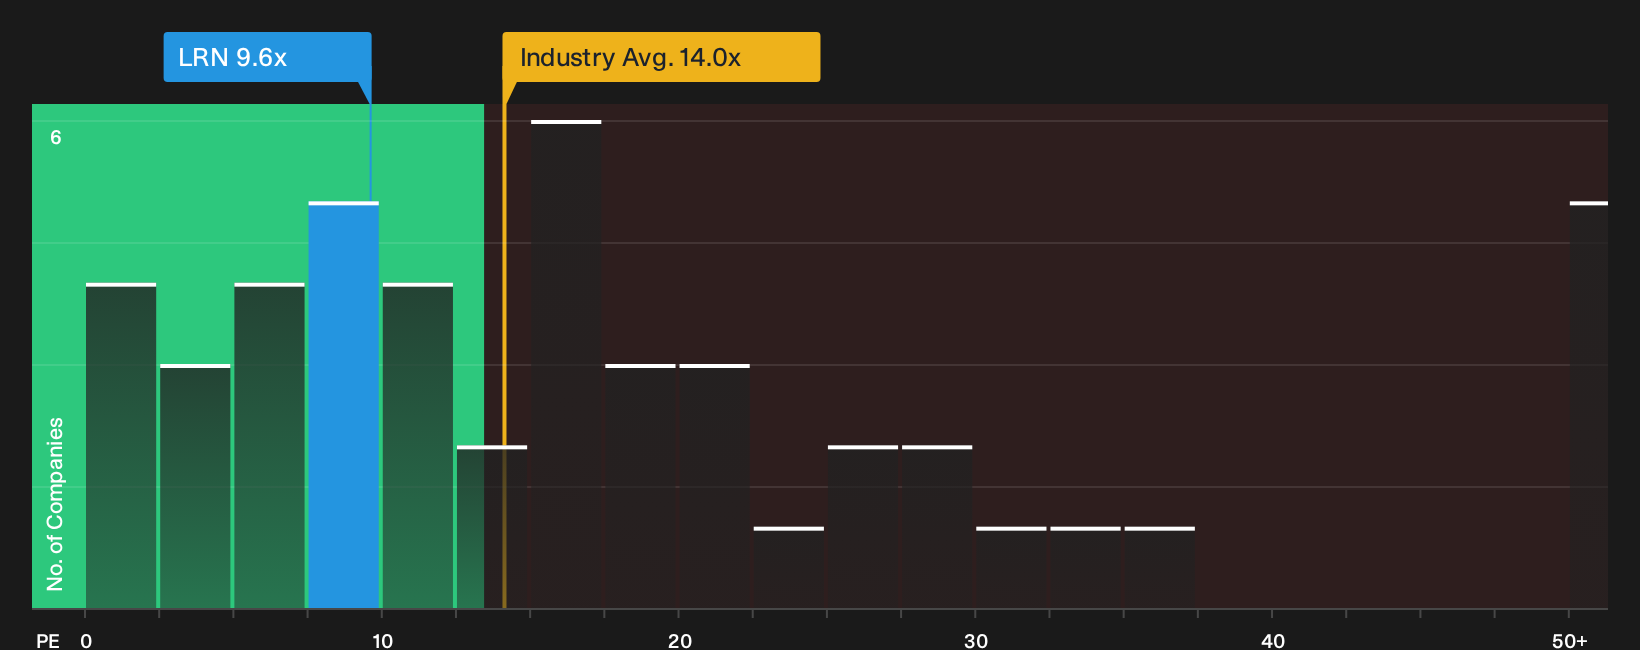
The P/E ratio fits Stride because earnings are a key anchor for how investors judge an education services business that scales through enrollment and course volumes. On that yardstick, Stride trades on a P/E of 9.6x, which is below the Consumer Services sector average of 14.0x and also below a peer group closer to 20.0x.
The valuation model suggests that, given Stride’s mix of growth prospects, profitability profile, size and risk, a higher P/E would typically be expected. Since the current multiple sits under that tailored benchmark, the stock screens as undervalued on this earnings metric, even before digging into cash flow or balance sheet details. Explore the numbers behind Stride's P/E valuation.
The Stride Narrative: What Would Justify Today's Price?
Stride investors looking beyond the P/E ratio can use Simply Wall St Narratives as a way to see what kind of future earnings, margin profile and reinvestment path would need to play out for the current share price to look materially higher or lower. Where a single multiple or valuation output gives one number, Narratives unpack the specific operating assumptions behind it so you can watch over time whether the real business tracks that script on the Community page.
Stride investors are weighing two very different stories, with one camp seeing meaningful upside while the other thinks expectations already look full.
Bull case: 31% undervalued
"Expansion of tutoring and career-focused learning solutions, both internally and as externally monetizable offerings, positions Stride to capture additional revenue streams..."
Discover why this Narrative puts Stride at 31% undervalued.
Bear case: 54% overvalued
"Stride operates across K-12 virtual schools, career learning, adult education, and professional certification programs, while enrollment cycles can be lumpy and politically sensitive..."
Explore why this Narrative puts Stride at 54% overvalued.
One more Stride check that belongs beside the price tag
Share price and earnings only tell part of the story, because the people steering Stride and the way their pay is structured can heavily influence how every future dollar is earned and allocated. See who runs Stride and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com