
Quanta Services (PWR), Why Is The Market Taking A Closer Look?
Analyst sentiment triggers fresh look at Quanta Services
Fresh analyst optimism and higher earnings estimates for Quanta Services (PWR) have pushed the stock back into focus, with recent commentary also spotlighting its record backlog and diversified infrastructure platform.
Recent trading has been choppy, with the share price down 1.2% over the last day but still up 44.4% year to date. That move sits alongside a 57.7% one year total shareholder return and a very large 5 year total shareholder return that underlines how long term holders have been rewarded, even as shorter term momentum has cooled after an 11.7% drop over the past 90 days.
Spot 39 power grid technology and infrastructure stocks that, like Quanta Services, are tied to large scale grid upgrades and could be setting up for their next major move.Bulls point to Quanta Services’ record backlog, diversified grid work and strong analyst support. Bears flag the sharp run up, recent pullback and rich expectations baked into today’s US$634.90 share price. Which side does the valuation lean toward now?
Most Popular Narrative: 10.6% Undervalued
Quanta Services last closed at $634.90, while the most followed narrative pegs fair value at $710.00, which implies a valuation gap that loyal holders have been watching closely as the grid buildout theme gathers attention.
The long case is simple: Quanta sits at the intersection of several unusually durable spending waves: aging grid replacement, transmission expansion, utility hardening, manufacturing reshoring, renewable interconnection, and AI-driven power demand. The company’s scale, labor base, customer relationships, and expanding “total solutions” model make it one of the few contractors able to execute very large, complex programs.
See why 67 investors see Quanta Services as 11% undervalued.
Result: Fair Value of $710.00 (UNDERVALUED)
Still, any wobble in Quanta Services’ large project execution, or a slowdown in utility and data center awards, could quickly pressure this undervaluation story.
Find out about the key risks to this Quanta Services narrative.
Another View: What Quanta Services’ P/E Is Telling You
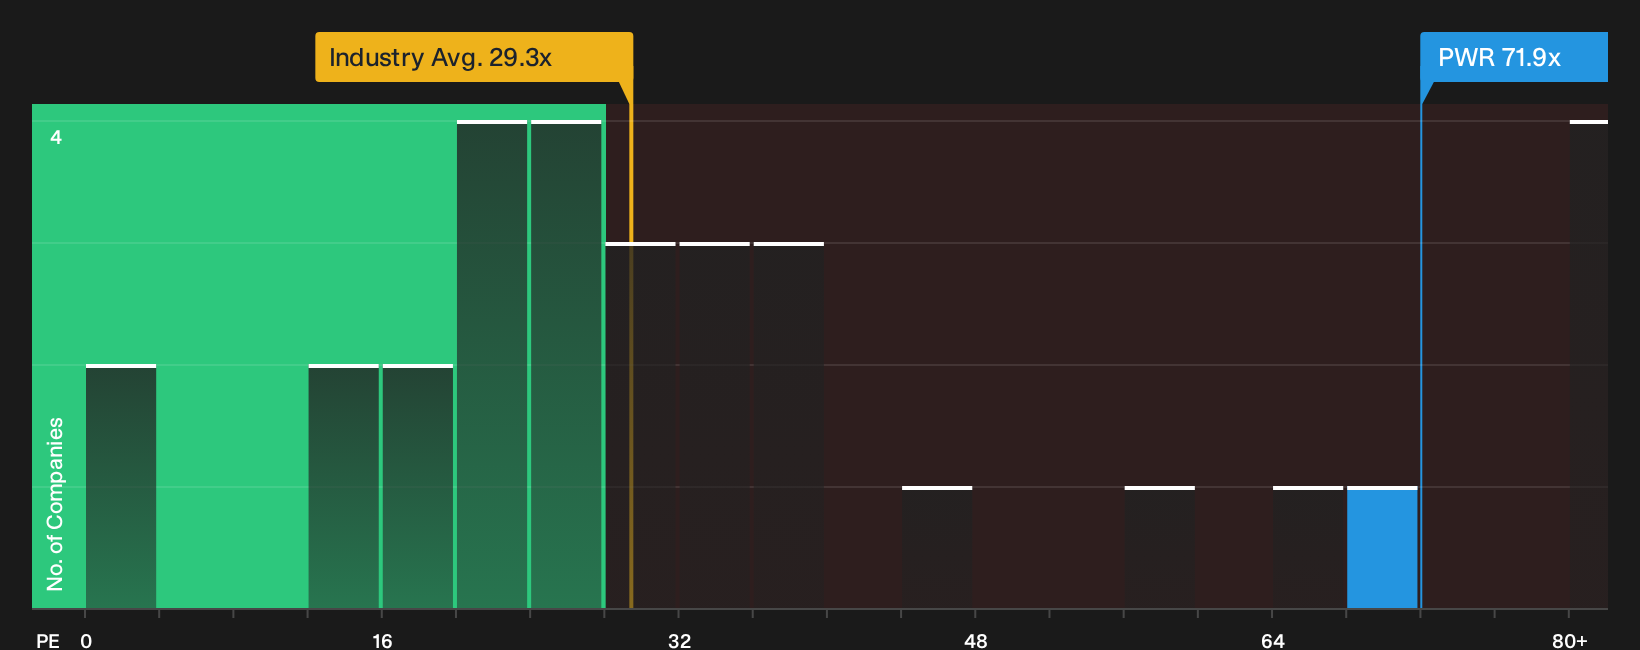
That 10.6% “undervalued” narrative bumps up against a very different message from simple earnings multiples. Quanta Services trades on a P/E of 71.9x, more than double the US Construction industry at 29.3x and well above the 38.8x fair ratio. That gap points to real valuation risk if expectations cool even slightly.
Investors who lean on earnings multiples may want to see how these numbers stack up against a fuller breakdown of assumptions and peer comparisons in our valuation workup, then decide which story feels more durable for their own process. See what the numbers say about this price — find out in our valuation breakdown.
Here is how Quanta Services’ current P/E compares visually with the broader sector.
Next Steps
Mixed signals on Quanta Services so far? Take a few minutes to weigh the data on both sides, including our view of 2 key rewards and 1 important warning sign.
Looking for more Quanta Services style ideas?
If Quanta Services has sharpened your focus on quality and pricing power, do not stop here. Broader opportunity sits with other carefully filtered stocks on Simply Wall Street.
- Target potential mispricings by checking companies that screen as solid quality yet attract discounted market expectations via the 30 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that feature robust payouts and higher yields using the 7 dividend fortresses.
- Dial down volatility in your portfolio by focusing on companies that pass strict balance sheet and fundamentals filters through the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com