
Has Allient (ALNT) Run Too Far After Strong Demand And A Growing Backlog?
Recent commentary around Allient (ALNT) has focused on strong demand, record order activity, and widening margins, with management pointing to a growing backlog that it expects to turn into revenue within months.
Allient’s recent operational updates are landing in a market that has already seen strong momentum, with a 1-day share price return of 5.13% and a 7-day share price return of 19.88% taking the stock to US$113.60. Over a longer window the move is even more pronounced, with a year to date share price return of 104.39% and a 1-year total shareholder return of 155.99%. The 3-year total shareholder return of 269.91% suggests that the current enthusiasm is building on an already strong run rather than appearing out of nowhere.
Ride Allient's momentum by scanning a curated set of industrial and automation players in the 94 robotics and automation stocks that may be building similar order backlogs and earnings strength.Allient’s surge has been tied to real orders, margin progress, and a thicker backlog. However, the speed of the move invites a harder look at whether the current price still lines up with those fundamentals.
Most Popular Narrative: 3.7% Undervalued
On the widely followed narrative, Allient’s fair value sits at $118 against a last close of $113.60. This frames a modest valuation gap that rests on specific assumptions about growth, margins, and risk.
The analysts have a consensus price target of $118.0 for Allient based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $130.0, and the most bearish reporting a price target of just $90.0.
See why 8 investors see Allient as 4% undervalued.
Result: Fair Value of $118 (UNDERVALUED)
Still, Allient could beat this script if its shift toward higher value aerospace, defense, and medical work supports firmer margins and steadier demand.
Find out about the key risks to this Allient narrative.
Another View: Allient Looks Expensive On Earnings
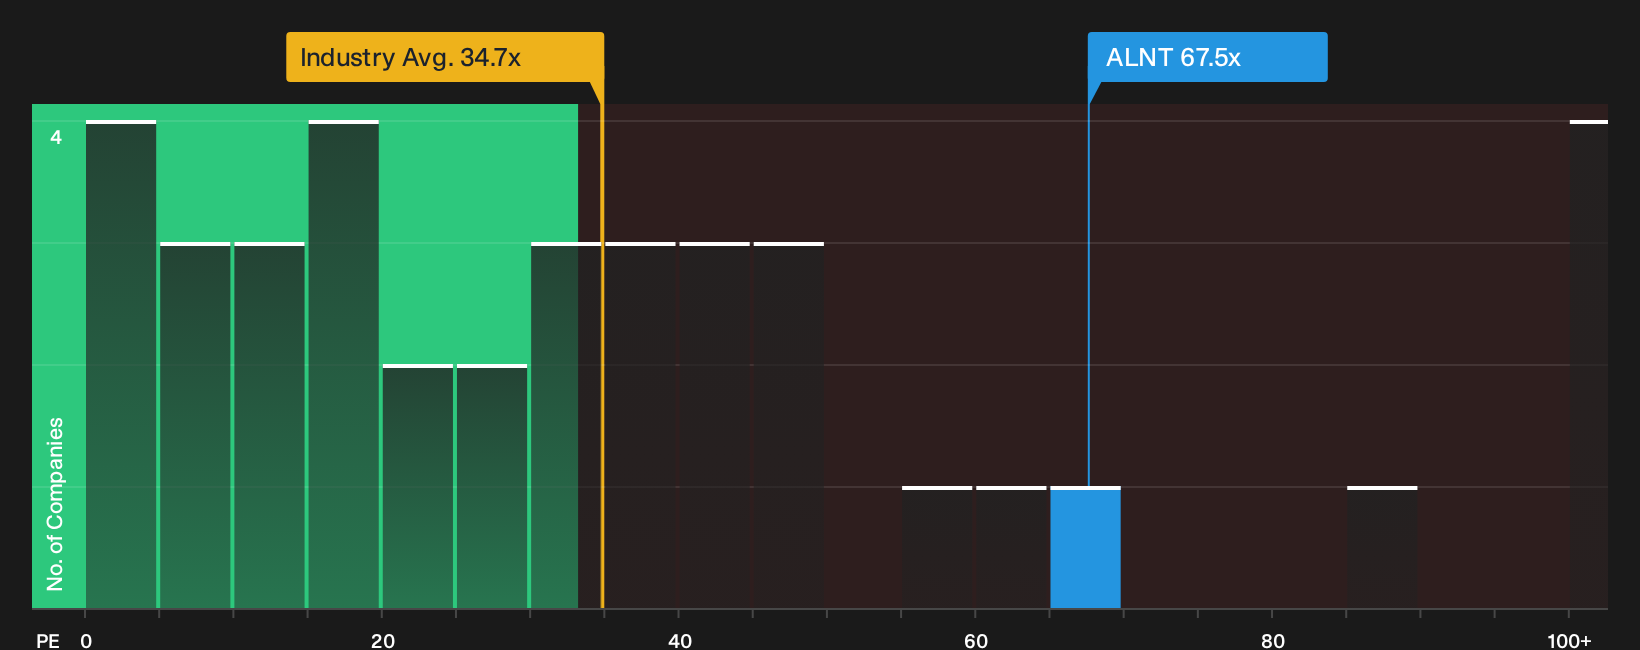
The first narrative around Allient leans on analyst targets and growth assumptions. A simple P/E cross-check tells a tougher story. The stock trades on 67.5x earnings versus 34.5x for the US Electrical sector, 26.3x for peers, and a fair ratio estimate of 25.8x.
This kind of gap suggests investors today are paying a heavy premium for Allient’s current momentum and future earnings profile. The question is whether the business has enough staying power to justify a P/E that is significantly above both peers and its own fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Allient can be interpreted as either a warning light or a potential opening, so review the full picture now and shape your own stance using the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Allient?
If Allient’s surge has your attention, use that momentum. Scan fresh opportunities now so you are not catching up after the next move.
- Target quality at a discount by reviewing the 30 high quality undervalued stocks that combine solid financial traits with prices below estimated worth.
- Build a steadier income stream by focusing on the 7 dividend fortresses that aim for higher yields with supporting fundamentals.
- Prioritise resilience by checking the 31 resilient stocks with low risk scores that score well on financial strength and lower risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com