
How Investors Are Reacting To Shin Etsu Chemical Stock Option Issuance
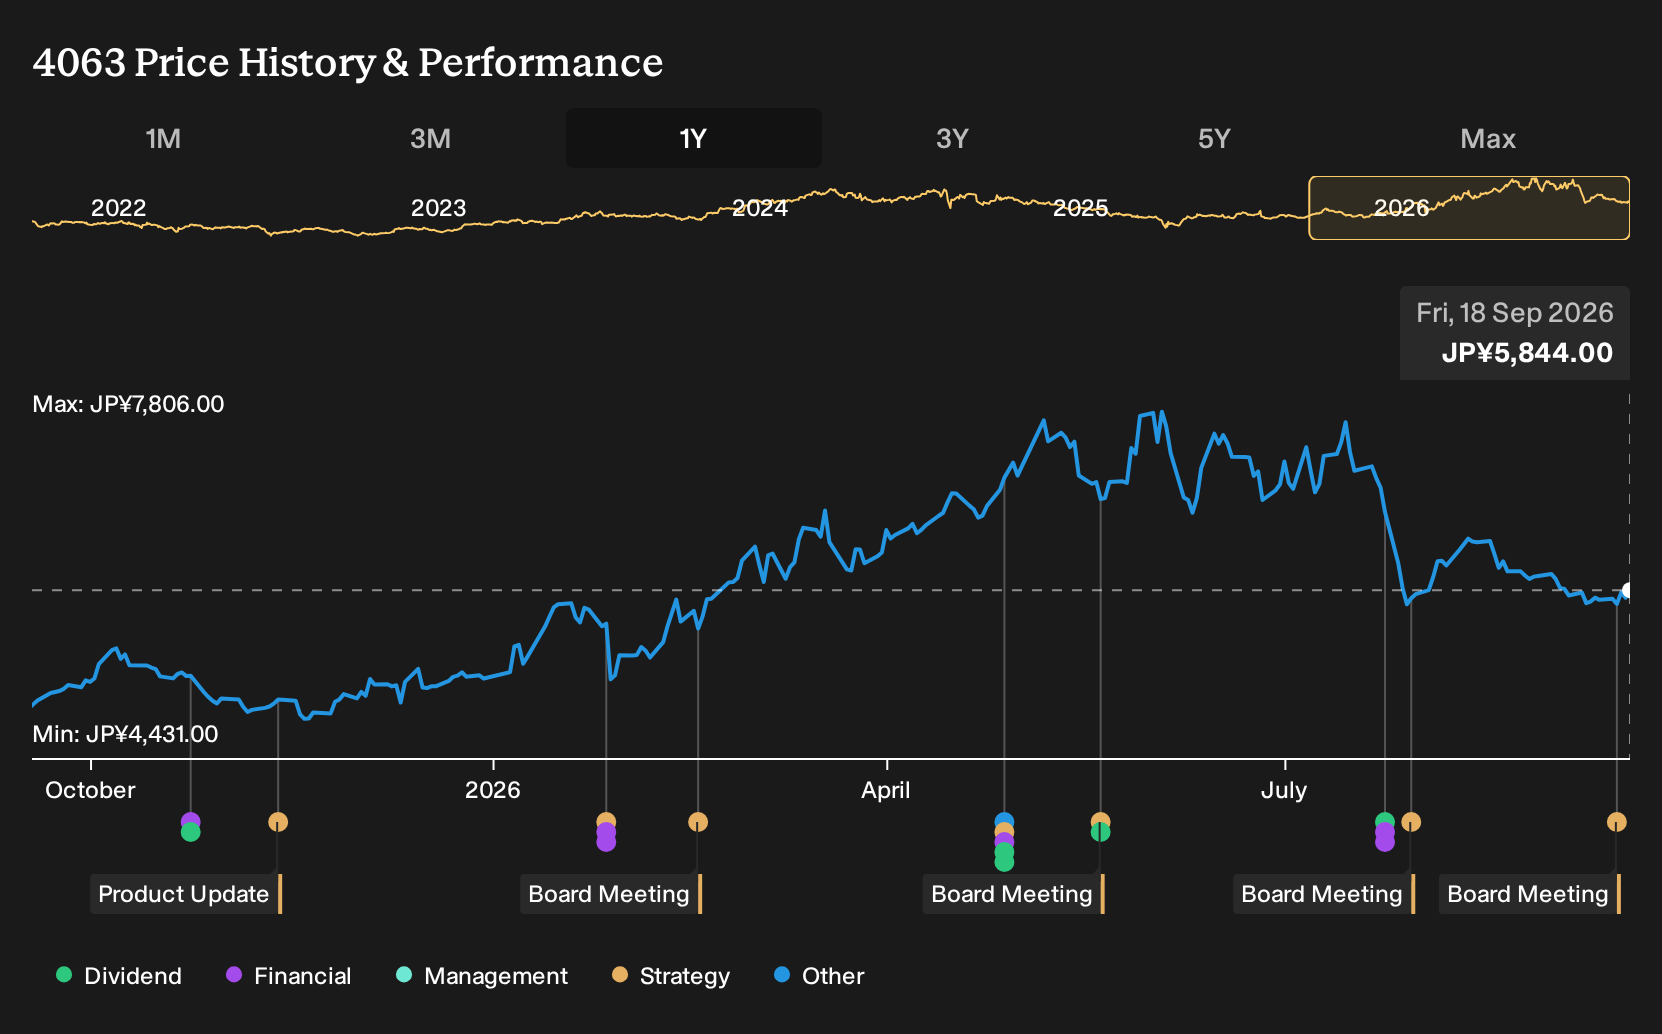
- Shin-Etsu Chemical held a board meeting on Sep 15, 2026, where directors approved the issuance of stock options in the form of stock acquisition rights.
- The fresh stock options program signals a focus on retention and incentives for key personnel and may influence future dilution and operating discipline across Shin-Etsu Chemical's core businesses.
- We will now look at how Shin-Etsu Chemical's investment narrative could be affected by this new stock options issuance plan.
Compare Shin-Etsu Chemical's new stock option move with peers by scanning a curated group of list of solid balance sheet and fundamentals (21 results) that are also using equity incentives to keep key talent aligned.
What Is Shin-Etsu Chemical's Investment Narrative?
To own Shin-Etsu Chemical, you need to be comfortable with a large, globally exposed materials producer that still has to execute day in, day out on complex, capital intensive operations. The key belief is that its positions in PVC, semiconductor silicon and silicones can keep attracting solid demand and support earnings that analysts currently expect to grow around 11.2% a year, with revenue forecast near 7.1% a year. The latest share price, at ¥5,844 and about 23% below one modelled cash flow value, reflects some of that but not all of it, in the view of those forecasts.
The new stock option plan fits into that picture as a governance and incentive tweak rather than a fundamental shift. It could matter at the margin for execution quality if it helps retain talent, yet the immediate effects on volumes, pricing power or capital spending plans look limited. The bigger swing factors in the near term remain demand cycles in electronics, the P/E multiple of 22.7x versus lower peer averages, and the fact that earnings recently fell versus the prior year even as analysts still modelled growth ahead.
Even so, there is a softer undercurrent in the Shin-Etsu Chemical story that could unsettle long term holders if ...
There's only one way to know the right time to buy, sell or hold Shin-Etsu Chemical. Head to Simply Wall St's company report for the latest analysis of Shin-Etsu Chemical's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between ¥7,598 and ¥7,775 per share, which still sits above Shin-Etsu Chemical’s latest traded price. Those views were formed before the September 15 stock option plan, so you should consider how fresh equity incentives could influence future discipline as well as your own expectations.
Explore another Shin-Etsu Chemical fair value estimate, including one that suggests as much as 33% upside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Shin-Etsu Chemical research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Shin-Etsu Chemical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Shin-Etsu Chemical's overall financial health at a glance.
Looking For More Ideas Beyond Shin-Etsu Chemical?
Once you have a view on Shin-Etsu Chemical, it can help to widen the lens and compare it with other companies that match the kind of balance sheet strength, value profile, or income potential you want in a portfolio.
- If you are hunting for potentially mispriced opportunities with solid fundamentals, take a look at our curated 17 high quality undervalued stocks that might offer better value for the risk you are willing to take.
- For investors who care most about income reliability, map out your watchlist using a focused set of 14 dividend fortresses that aim to combine yield with resilience.
- When capital preservation ranks high on your list, stress test your ideas against a hand picked universe of 21 resilient stocks with low risk scores that score well on financial strength and risk controls.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com