
ROHM (TSE:6963) Launches New Automotive MOSFET On A Valuation Debate
ROHM (TSE:6963) has just rolled out the RS4P063BPHZG, a 100V MOSFET aimed at automotive safety and protection circuits, highlighting its push into higher SOA components as vehicle electrification demands intensify.
Recent trading suggests momentum in ROHM is cooling after a strong run. The share price is ¥4,648, with a 1 day share price return of 3.94% and a year to date share price gain of 104.08%. The 90 day share price return has fallen 12.99% and the 1 year total shareholder return sits at 109.56%, indicating that the latest product launches are landing in a market that is reassessing how much future growth and risk is already reflected in the valuation.
Scan beyond ROHM and review a curated group of power and electrification plays through the 39 power grid technology and infrastructure stocks that may also be responding to the same push for higher reliability components.
ROHM looks like a serious player in high reliability power components after its recent run and fresh product news. The real tension now is whether you are paying too much for that quality story.
Most Popular Narrative: 19% Undervalued
Against a last close of ¥4,648, the most followed narrative for ROHM points to a fair value of about ¥5,764. This frames today’s debate around whether recent product news can support that higher valuation over time.
ROHM is planning to increase its production capacity and efficiency for SiC (silicon carbide) power devices, correlating with expected battery EV market growth, which should enhance revenue and earnings as demand eventually picks up. The company is implementing a new organizational structure to better cater to customer needs and market applications, which aims to improve sales and potentially increase net margins by offering more integrated, solution-based proposals.
See why 3 investors see ROHM as 19% undervalued.
Result: Fair Value of ¥5,764 (UNDERVALUED)
Still, ROHM’s narrative could be tested if industrial demand stays weak or if higher fixed costs keep profitability under pressure for longer than analysts currently model.
Find out about the key risks to this ROHM narrative.
Another View on ROHM’s Valuation
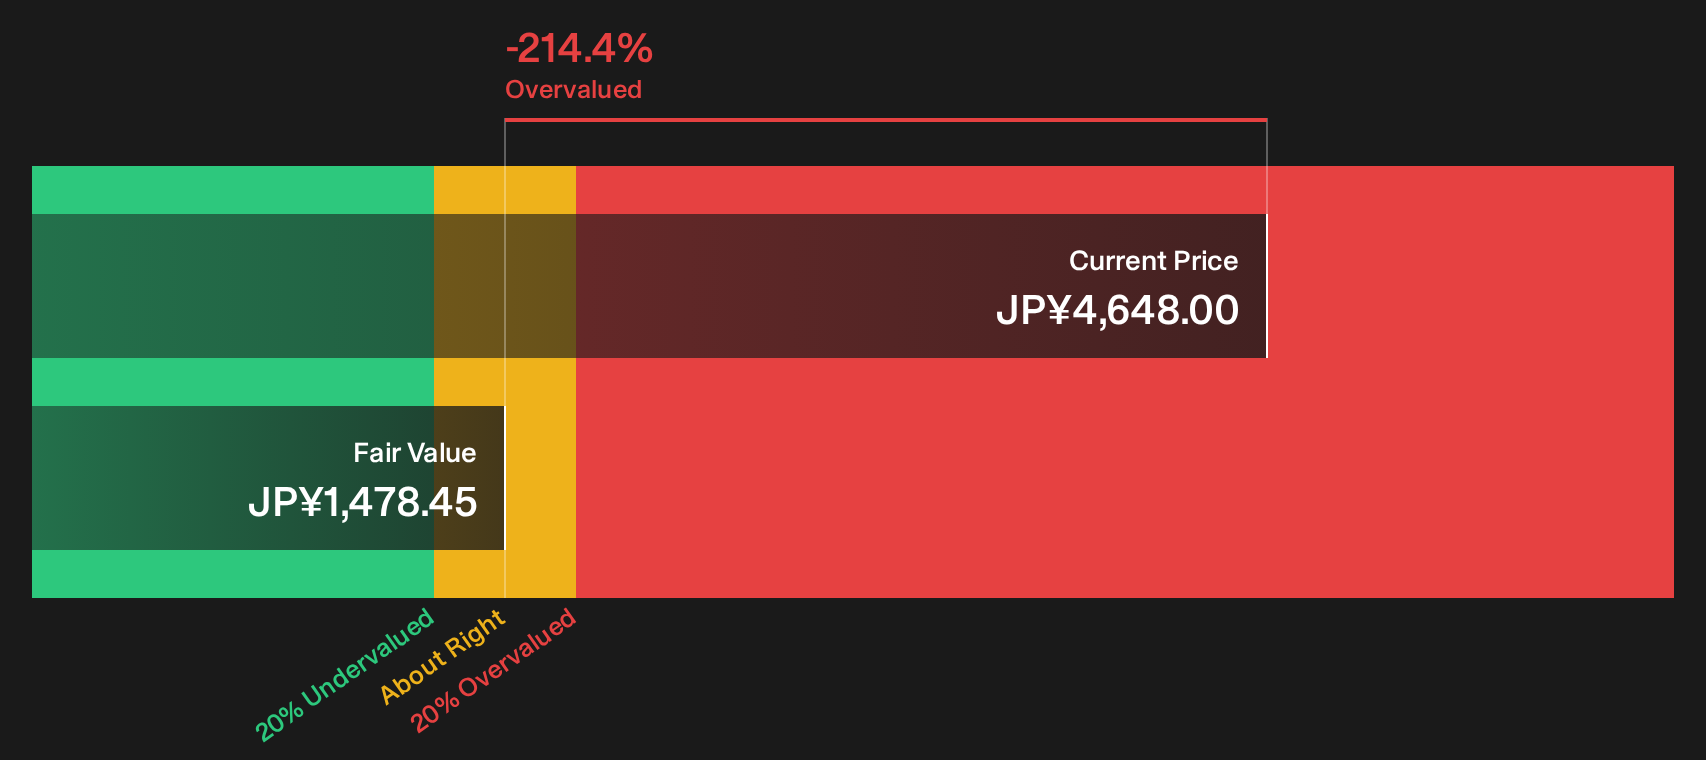
Analysts see upside in ROHM, yet our DCF model points the other way. On an estimate of future cash flows at about ¥1,478 per share versus today’s ¥4,648 price, the stock looks overvalued on this framework. Which lens you trust more comes down to how much near term pain you think matters.
Before leaning on a single approach, it helps to see how the SWS DCF model works in detail. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Feeling uncertain about the tone of ROHM’s story so far? Consider acting while the details are fresh and weigh both sides by checking the 1 key reward and 1 important warning sign.
Ready for more ideas beyond ROHM?
If ROHM has sharpened your appetite for opportunities, do not stop here. Use focused screeners now to surface fresh candidates before others move first.
- Target proven quality and resilience by scanning a list of solid balance sheet and fundamentals (21 results) that can help you avoid fragile stories.
- Hunt for mispriced opportunities by running the 17 high quality undervalued stocks and see which businesses offer more cash flow for every yen you commit.
- Build a steadier income stream by filtering for dependable payers through the 14 dividend fortresses before yields change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com