
Does Earnings Beat Change The Bull Case For Guidewire Stock (GWRE)?
- Guidewire Software recently reported stronger than expected Q2 revenue growth, alongside new insurance client wins for its AI-centric ProNavigator and global payment integration with Adyen.
- The Adyen partnership and Lititz Mutual deployment highlight how Guidewire is embedding AI and payment automation directly into insurer workflows, which deepens its role in day to day policy and claims operations.
- We will now look at how Guidewire's AI focused wins with insurers may influence the company's broader investment narrative.
See how Guidewire Software's AI push compares with other insurers' technology initiatives by reviewing the hand picked 38 profitable AI stocks that aren't just burning cash that already back their story with real earnings.
Guidewire Software Investment Narrative Recap
To own Guidewire Software you need to believe insurers will keep standardizing on its cloud platform and gradually layer on data and AI tools like ProNavigator. The near term story still leans on steady cloud migrations, growing annual recurring revenue, and disciplined cost control. The latest product news helps the narrative but does not radically change it.
The key short term catalyst remains execution on large cloud projects without major delays or cost overruns. The biggest risk still sits in that same transition, along with foreign exchange swings and competitive pressure in new geographies. Recent AI and payments announcements slightly strengthen Guidewire Software's operational pitch.
The Adyen partnership is the cleanest tie in to the current news. ProNavigator speaks to smarter decision support, while Adyen extends Guidewire Software deeper into the money movement that sits behind every policy and claim. That link between AI workflows and payments makes the broader platform more useful inside an insurer's daily operations.
For catalysts, this integration gives Guidewire another reason for carriers to consolidate vendors on its marketplace instead of stitching together regional payment providers. The operational upside sits in fewer payment failures, faster payouts, and unified reporting. Execution risk shows up in how smoothly global insurers adopt the standardized integration across regions and legacy stacks.
Guidewire Software's current analyst narrative points to revenues of US$2.2b and earnings of US$294.1m by 2029, based on an assumed 15.3% yearly revenue growth rate and an earnings move of about US$134.3m from US$159.8m today.
Uncover how Guidewire Software's fair value indicates a 38% potential upside to its current price before that discount closes.
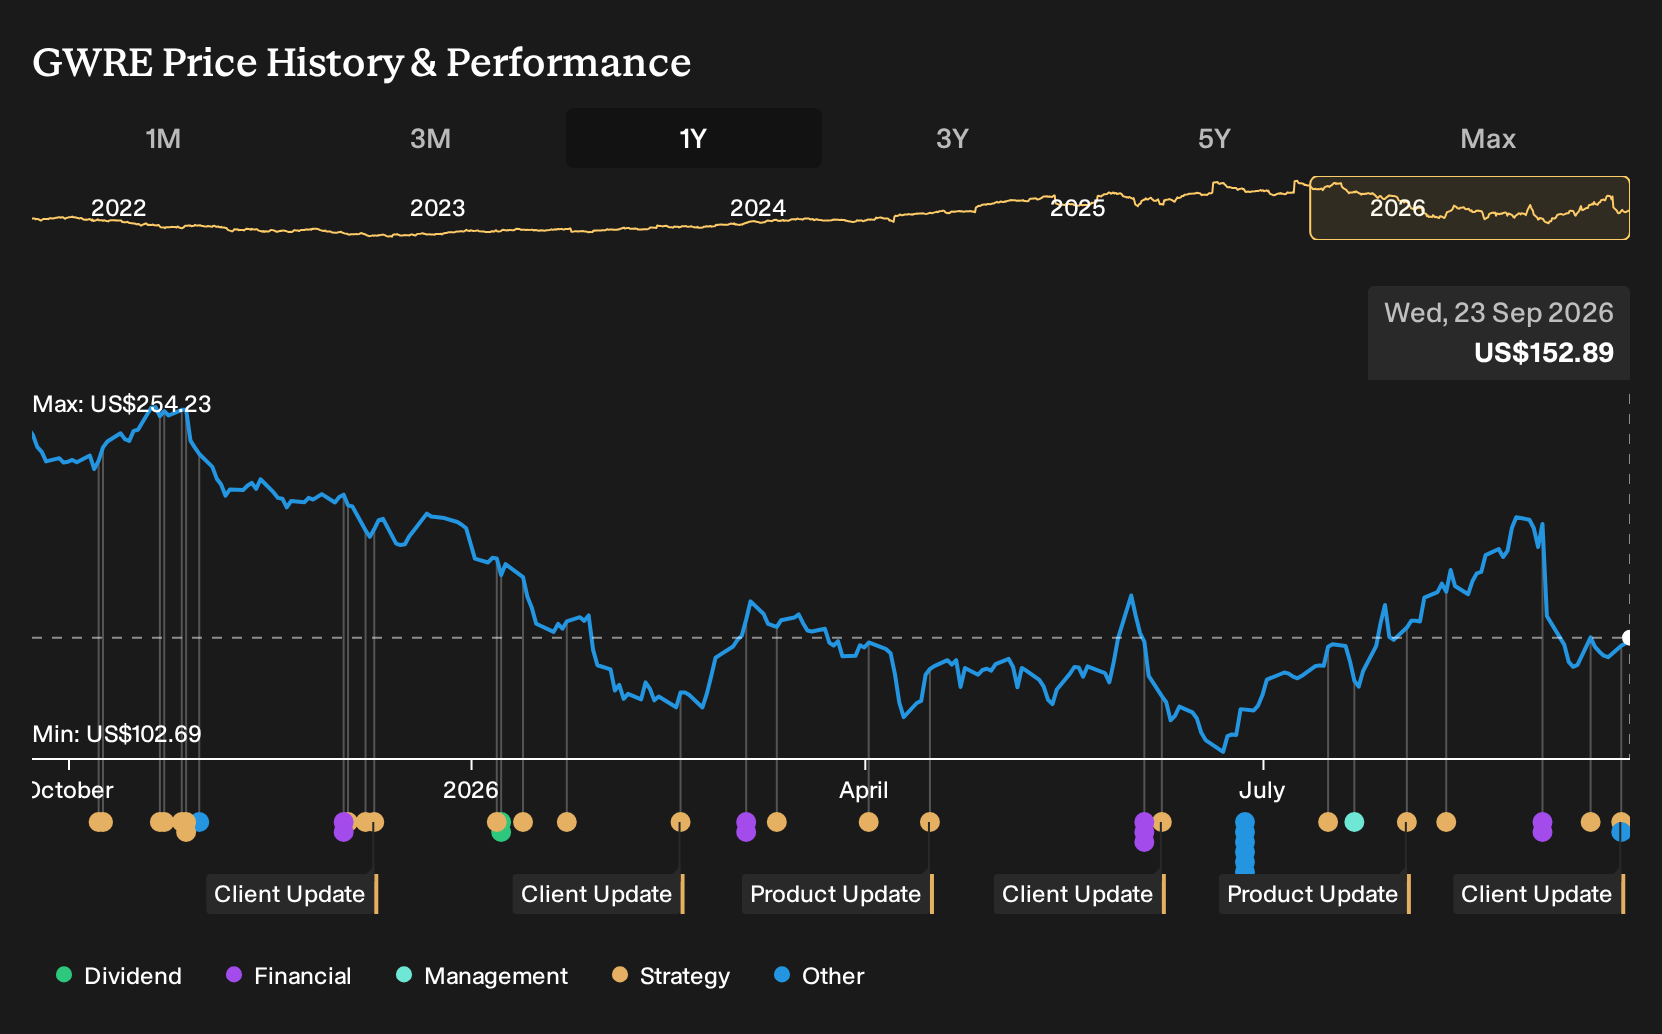
Exploring Other Perspectives
One alternate take on Guidewire Software focuses less on cloud execution risk and more on the chance that AI client wins snowball. Before this news, the most optimistic analysts were already modelling about US$2.3b of revenue and US$310.1m of earnings by 2029. You can judge whether the ProNavigator and Adyen updates push those views even further.
Explore 3 other Guidewire Software fair value estimates, including one that suggests as much as 69% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Guidewire Software research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Guidewire Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Guidewire Software's overall financial health at a glance.
Looking For More Ideas Beyond Guidewire Software?
If you want to stress test your view on Guidewire Software, it can help to scan a wider field of companies with different risk and return profiles using the Simply Wall St Screener.
- For investors hunting for income resilience, review a curated set of potential yield opportunities through the 7 dividend fortresses and see how they stack up on sustainability.
- If capital preservation sits higher on your priority list, filter for companies that show lower overall risk using the 31 resilient stocks with low risk scores and compare their profiles to your current holdings.
- When you want fresh ideas beyond the usual watchlists, surface under-followed opportunities with strong fundamentals by scanning the 16 high quality undiscovered gems and see which ones deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com