
How New COO Appointment Will Impact Proto Labs (PRLB) Investors
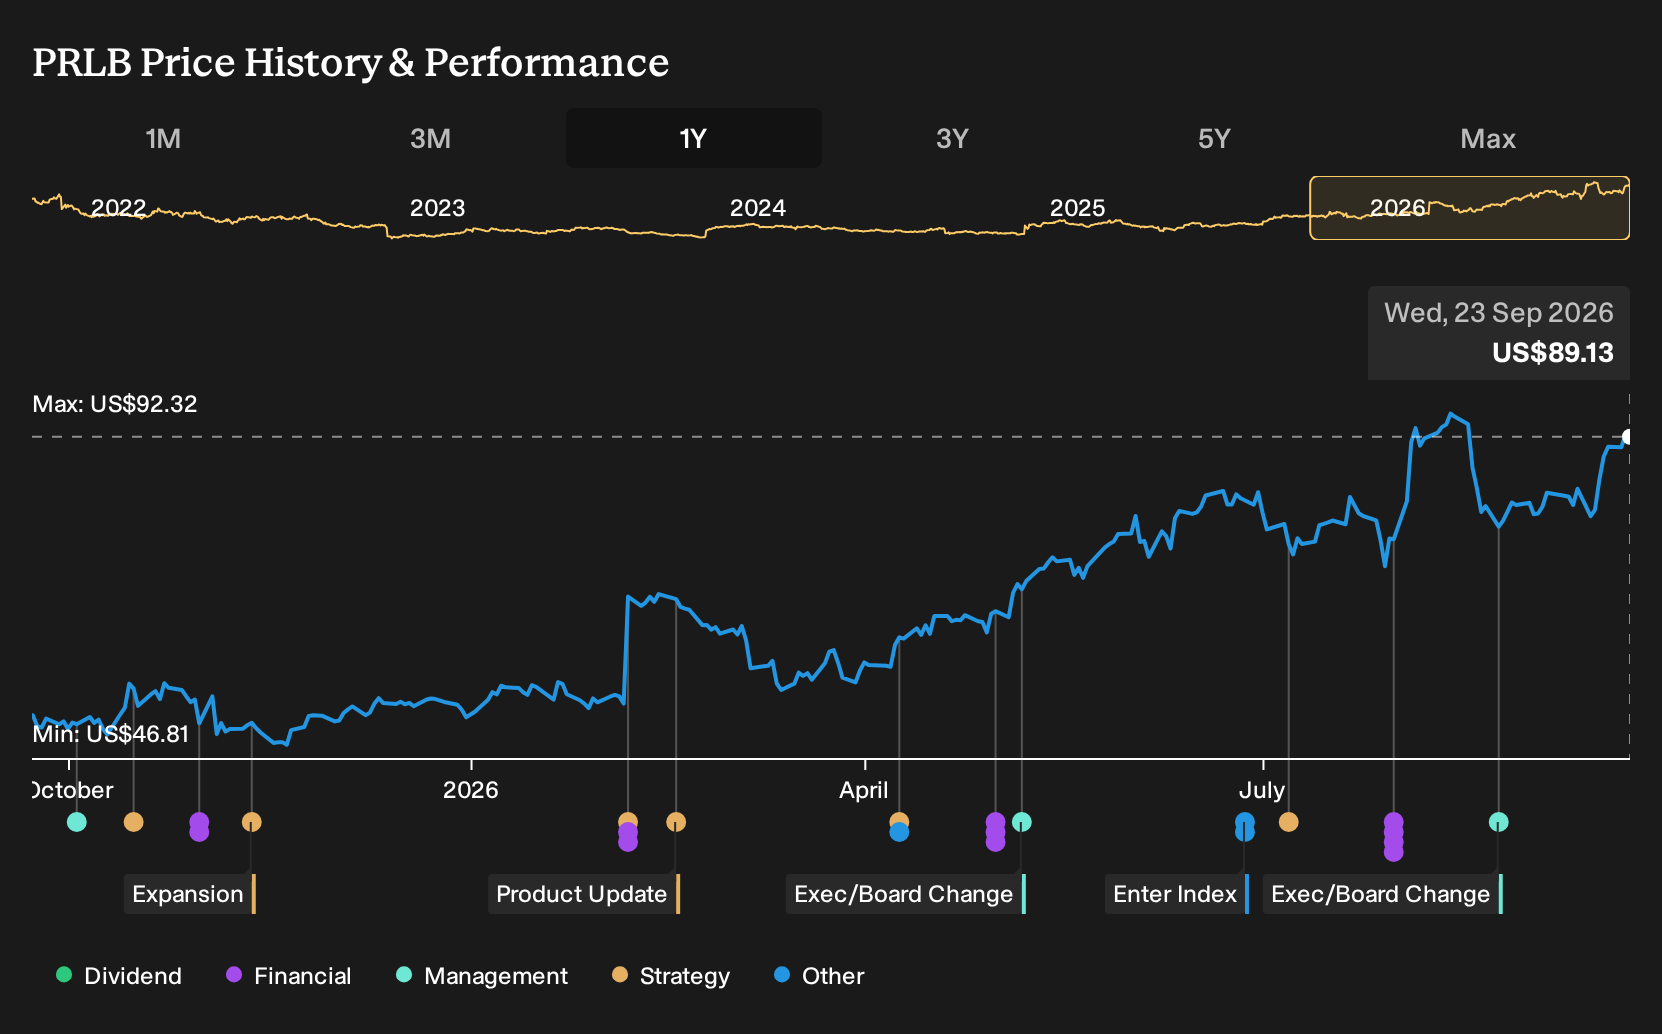
- Proto Labs recently appointed Sam Ramahi as Chief Operations Officer to run global operations, supply chain, quality, sourcing, and continuous improvement, alongside raising its full year revenue growth guidance following strong quarterly performance.
- The hire signals a push to scale Proto Labs’ production oriented manufacturing platform, where tighter execution on operations and supply chain could matter as much as new customer demand.
- The focus now shifts to what this new COO appointment and raised revenue guidance might mean for Proto Labs’ broader investment narrative.
Proto Labs Investment Narrative Recap
To own Proto Labs, you need to believe its digital manufacturing platform can shift from one off prototyping toward higher volume production work without eroding profitability. The new COO and tighter operational focus speak directly to execution on that shift. The raised full year revenue guidance signals management sees enough demand and capacity alignment to support that transition in the near term.
The key short term swing factor is whether Proto Labs can keep operational complexity under control as volumes and mix change, especially with European softness and customer concentration still in the background. The biggest risk remains margin pressure from competition, tariffs, and ongoing investment needs. The latest leadership move is important but does not remove that risk.
The most relevant piece of context for this COO hire is Proto Labs’ push into production oriented manufacturing, including robotics. Management reported that revenue from robotics customers more than doubled in the first half of 2026, alongside strong interest in CNC machining and sheet metal for high requirement work. That shift in mix puts more weight on consistent throughput, quality, and supply chain reliability.
For investors, the central question is whether Proto Labs can turn its robotics and production traction into durable, higher quality earnings without letting costs and complexity run ahead of sales. Operational execution under the new COO, combined with the existing digital network and certifications in areas such as metal 3D printing for medical devices, is central to that thesis and the associated risk.
Proto Labs' current revenue outlook from analysts points to 7.6% yearly revenue growth and a path to US$697.6 million in sales by 2029. Consensus forecasts earnings of US$58.5 million in that year, compared with earnings today of US$30.5 million, which implies earnings would need to almost double, rising by about 2x.
Uncover how Proto Labs' fair value indicates a 7% potential upside to its current price before the gap closes.
Exploring Other Perspectives
One alternative, more optimistic angle is that Proto Labs’ production pivot could eventually support higher earnings quality than consensus expects. Before this COO news, the most bullish analysts were already modeling about US$710.7 million of revenue and US$59.9 million of earnings by 2029. Those forecasts may either gain conviction or be reassessed as this leadership change plays out.
Explore 2 other Proto Labs fair value estimates, including one that suggests as much as 23% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Proto Labs research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Proto Labs. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Proto Labs' overall financial health at a glance.
Looking For More Investment Ideas Beyond Proto Labs?
If Proto Labs has sharpened your interest in digital manufacturing, it can help to compare it with other businesses that fit different risk, income, and quality profiles. The Simply Wall St Screener lets you filter opportunities quickly so you can focus on the few that genuinely deserve a deeper look.
- Target potential mispricings by scanning a curated pool of quality companies trading on what may be attractive terms through 30 high quality undervalued stocks.
- If capital preservation and balance sheet strength matter most to you, narrow the field to businesses with robust finances using the list of solid balance sheet and fundamentals (23 results).
- If you prefer steady income as part of your return profile and want to focus on companies with higher yields and resilient cash flows, then filter opportunities using the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com