
Learn Why The Bull Case For Sopra Steria Group (ENXTPA:SOP) Could Change Following Dynatrace AIOps Launch
- Sopra Steria Group recently launched a dedicated observability and AIOps practice with Dynatrace in France and Norway, targeting complex IT estates across banking, insurance, telecom, retail and public sector clients.
- The new practice aims to replace fragmented monitoring tools with a single source of truth, linking application health directly to customer journeys, downtime risk, capacity planning and engineering productivity.
- We will now look at how Sopra Steria Group's new Dynatrace powered observability practice could influence the broader investment narrative.
Scan how Sopra Steria Group's move into observability compares with other IT and infrastructure plays by tracking the hand picked 85 AI infrastructure stocks in this space.
Sopra Steria Group Investment Narrative Recap
To own Sopra Steria Group, you need to buy into a story where consulting, IT services and software steadily tilt toward higher value work in AI powered operations, cybersecurity and mission critical systems. The Dynatrace observability practice speaks directly to that shift, but by itself does not change the main near term swing factor, which is execution on large digital and defense contracts.
The biggest operational risk still sits in sluggish organic activity in core European markets, pressure from staff costs and weak cash generation after recent negative free cash flow. If the Dynatrace offer is rolled into managed services successfully, it could support margins and renewals. However, any financial impact will likely be gradual rather than immediate.
The new observability and AIOps practice with Dynatrace ties closely to one existing catalyst. Analysts already flag Sopra Steria Group’s push into AI powered digital services as a driver for a mix shift toward higher margin work. This practice gives a concrete operational example, focused on complex estates in banking, insurance, telecoms, retail and the public sector.
For you as a shareholder, the key question is whether Sopra Steria Group can turn this alliance into stickier managed services, better uptime metrics and cross sell into cybersecurity and sovereign cloud. Execution risk remains, given staff attrition and working capital issues, but a successful rollout would sit well alongside the larger defense and public sector contracts already ramping into 2026.
Sopra Steria Group's current earnings of €301.1 million are expected to reach €398.9 million by 2029, implying revenue of €6.5 billion that year and a 4.0% yearly revenue growth rate. This equates to an earnings increase of about €97.8 million by the 2029 forecast horizon.
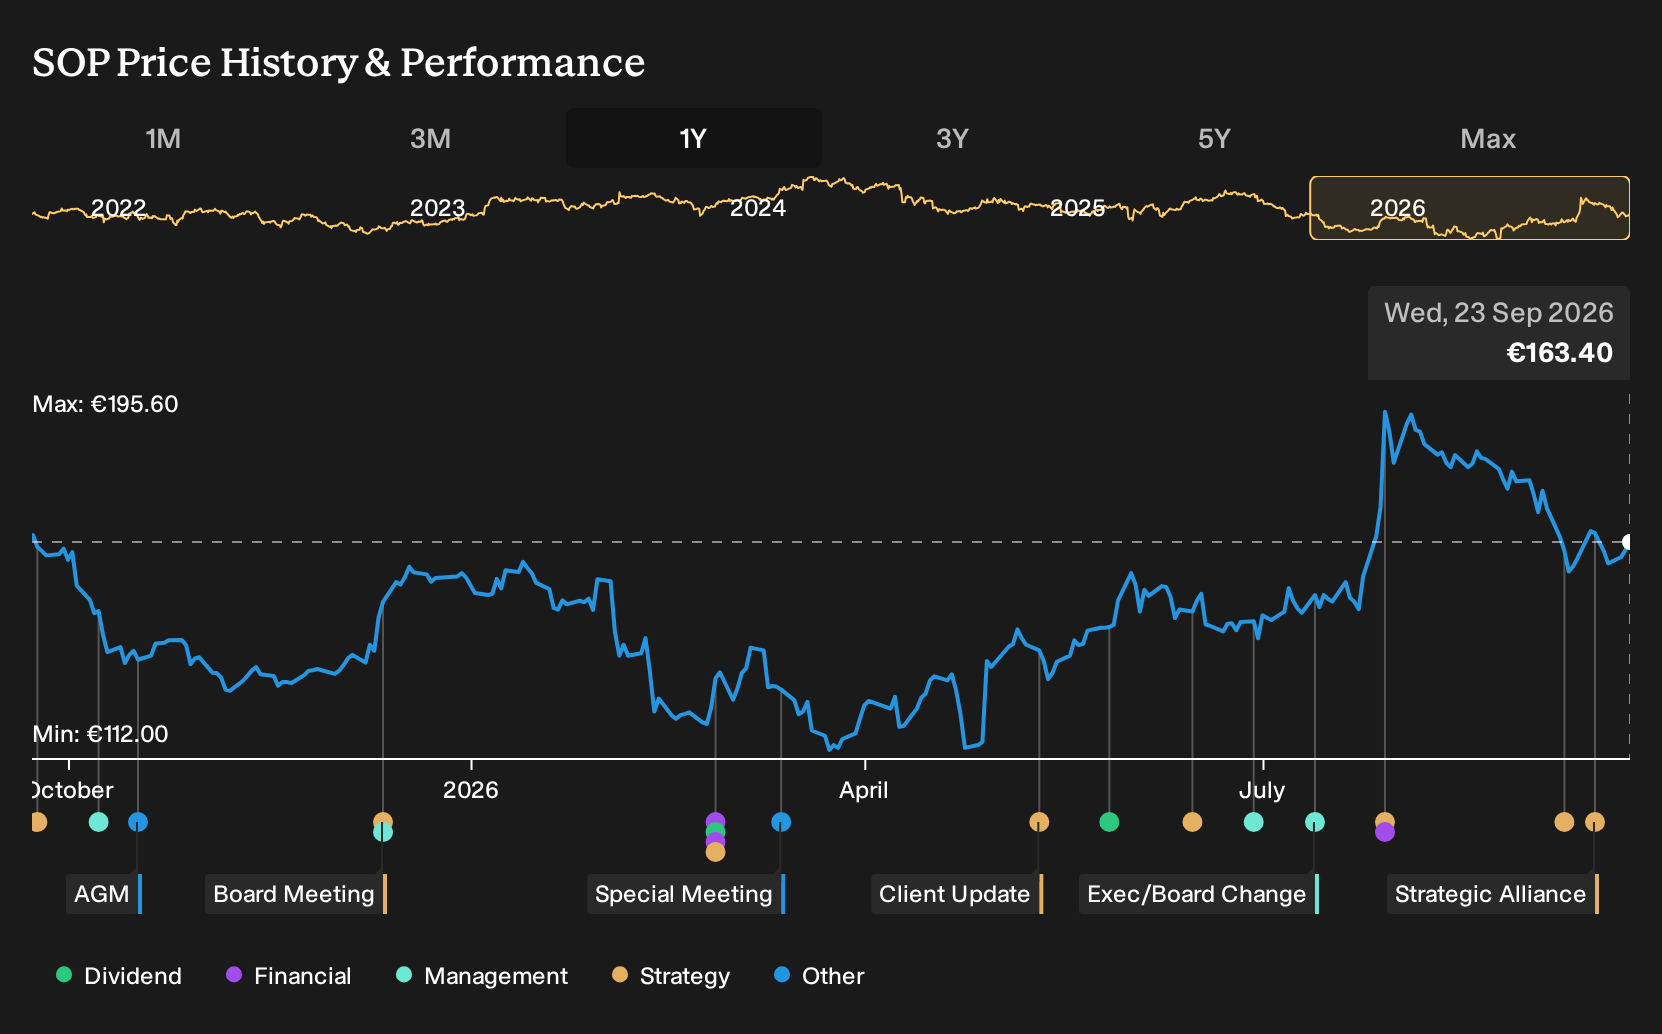
Uncover why Sopra Steria Group's fair value indicates a 34% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts already built a different story for Sopra Steria Group before this Dynatrace move. They were working off revenue of €6.1b and earnings of €378.6 million by 2028, with a higher P/E of 16.3x. You can now ask whether this observability push nudges those expectations even further or exposes them as too hopeful.
Explore 3 other Sopra Steria Group fair value estimates, including one that suggests potential upside of up to 38% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sopra Steria Group research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sopra Steria Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sopra Steria Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sopra Steria Group?
If Sopra Steria Group is only one piece of your watchlist, it can help to scan a wider field of opportunities and compare quality, value and risk across different sectors.
- If you want potential bargains with solid fundamentals and room for a re rating, take a look at the 171 high quality undervalued stocks that fit those criteria.
- If resilience and steadier profiles matter more to you than shooting for the highest upside, filter for companies in the 229 resilient stocks with low risk scores and see which ones match your risk tolerance.
- If you are hunting for under the radar opportunities with strong business metrics, start with the 618 high quality undiscovered gems and see which profiles line up with your own thesis.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com