
Three Undiscovered European Gems With Promising Potential
The European market has recently experienced volatility, with the pan-European STOXX Europe 600 Index ending the week down amid escalating Middle East tensions and fluctuating oil prices, which have heightened inflation concerns. Despite these challenges, opportunities can arise in smaller-cap stocks that are often overlooked but possess strong fundamentals and growth potential. In this article, we explore three such undiscovered gems in Europe that could offer promising prospects for investors willing to navigate current market complexities.
Top 10 Undiscovered Gems With Strong Fundamentals In Europe
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Apator | 13.65% | 6.21% | 20.01% | ★★★★★★ |
| B&C Speakers | 39.08% | 14.82% | 13.88% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| GROUPE SFPI | 18.02% | 4.25% | -29.76% | ★★★★★★ |
| Angler Gaming | NA | -4.50% | -4.71% | ★★★★★★ |
| Alexandria Group Oyj | 5.79% | 6.84% | 8.17% | ★★★★★☆ |
| IDI | 2.16% | -16.11% | -24.28% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Miko | 87.44% | 15.11% | 15.96% | ★★★☆☆☆ |
| Aqualis | 33.30% | 22.28% | -18.13% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
Alligo (OM:ALLIGO B)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Alligo AB (publ) operates in Sweden, Norway, and Finland, supplying workwear, personal protection items, tools, and consumables with a market capitalization of approximately SEK6.71 billion.
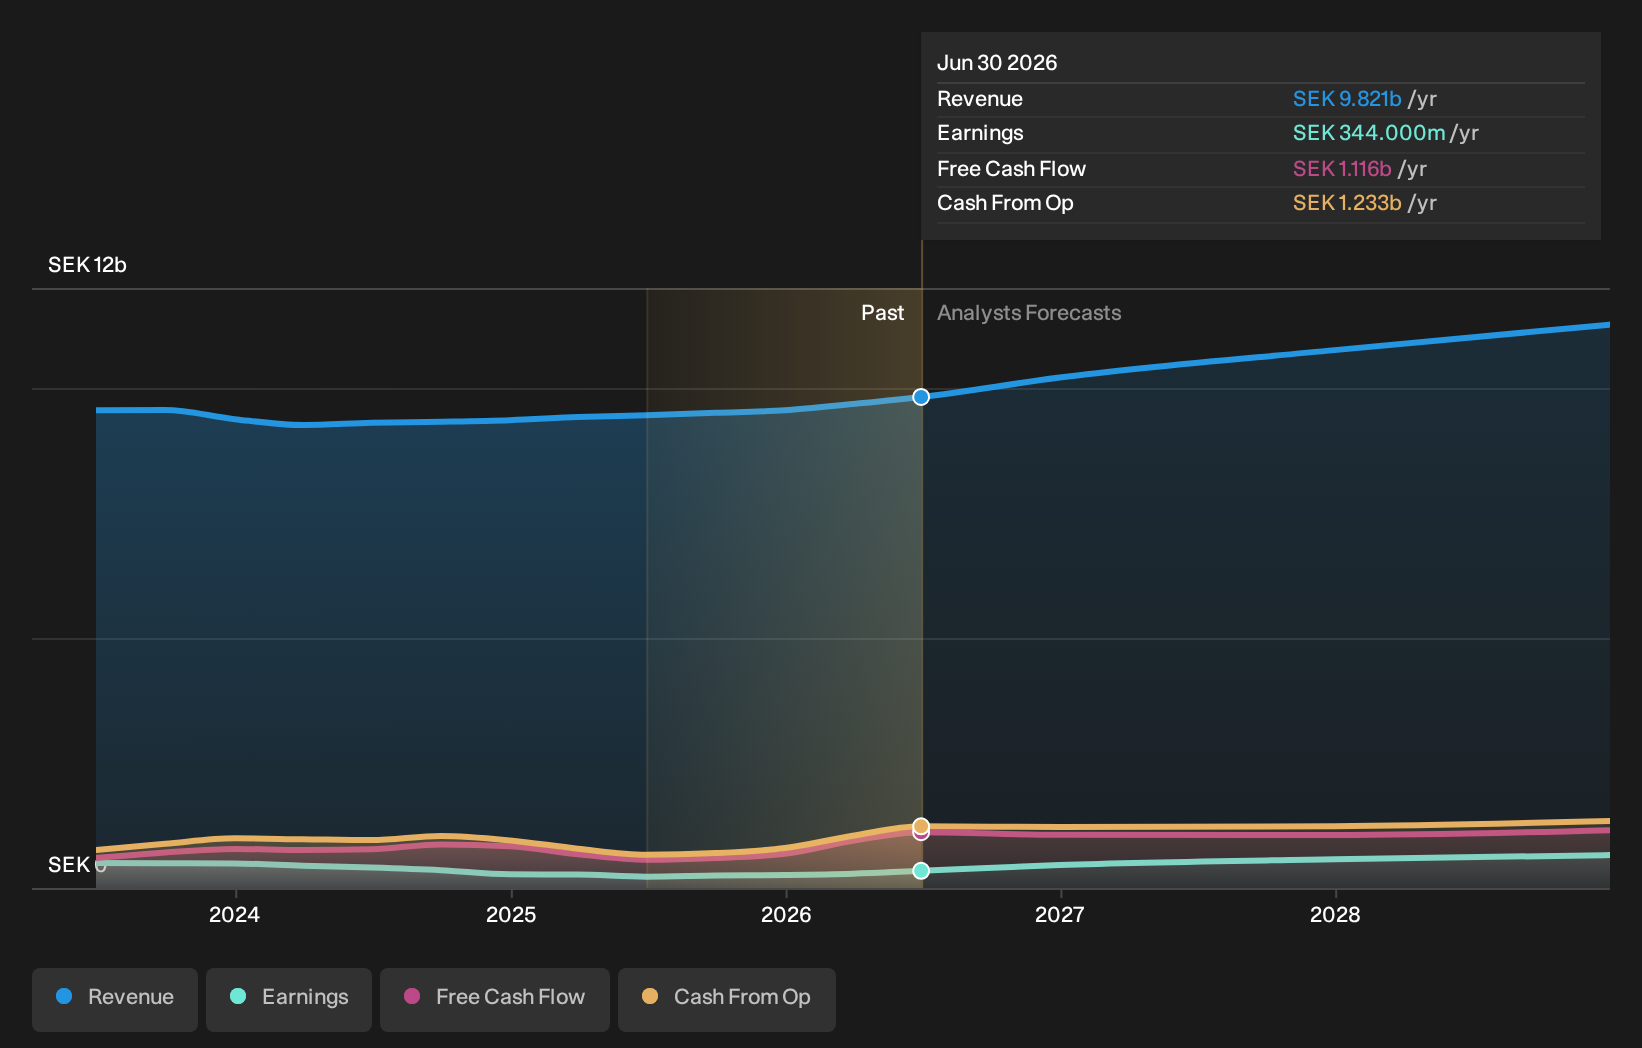
Operations: The company generates revenue primarily from its wholesale segment, specifically machinery and industrial equipment, amounting to SEK9.82 billion.
Alligo, a promising player in the European market, has demonstrated impressive growth with earnings surging 51.5% over the past year, outpacing the Trade Distributors industry at 12.8%. Despite a high net debt to equity ratio of 41.6%, its interest payments are comfortably covered by EBIT at 5.2 times coverage, indicating sound financial management. Recent earnings announcements revealed net income for Q2 at SEK 101 million compared to SEK 44 million last year and basic EPS from continuing operations rose to SEK 2.02 from SEK 0.88, reflecting strong operational performance and potential for future growth in profitability and revenue streams.
Svedbergs Group (OM:SVED B)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Svedbergs Group AB (publ) is a company that focuses on the development, manufacturing, and marketing of bathroom products across the Nordic region, the United Kingdom, and the Netherlands with a market capitalization of approximately SEK3.01 billion.
Operations: Svedbergs Group generates revenue primarily from the development, manufacturing, and marketing of bathroom products. The company operates in the Nordic region, the United Kingdom, and the Netherlands.
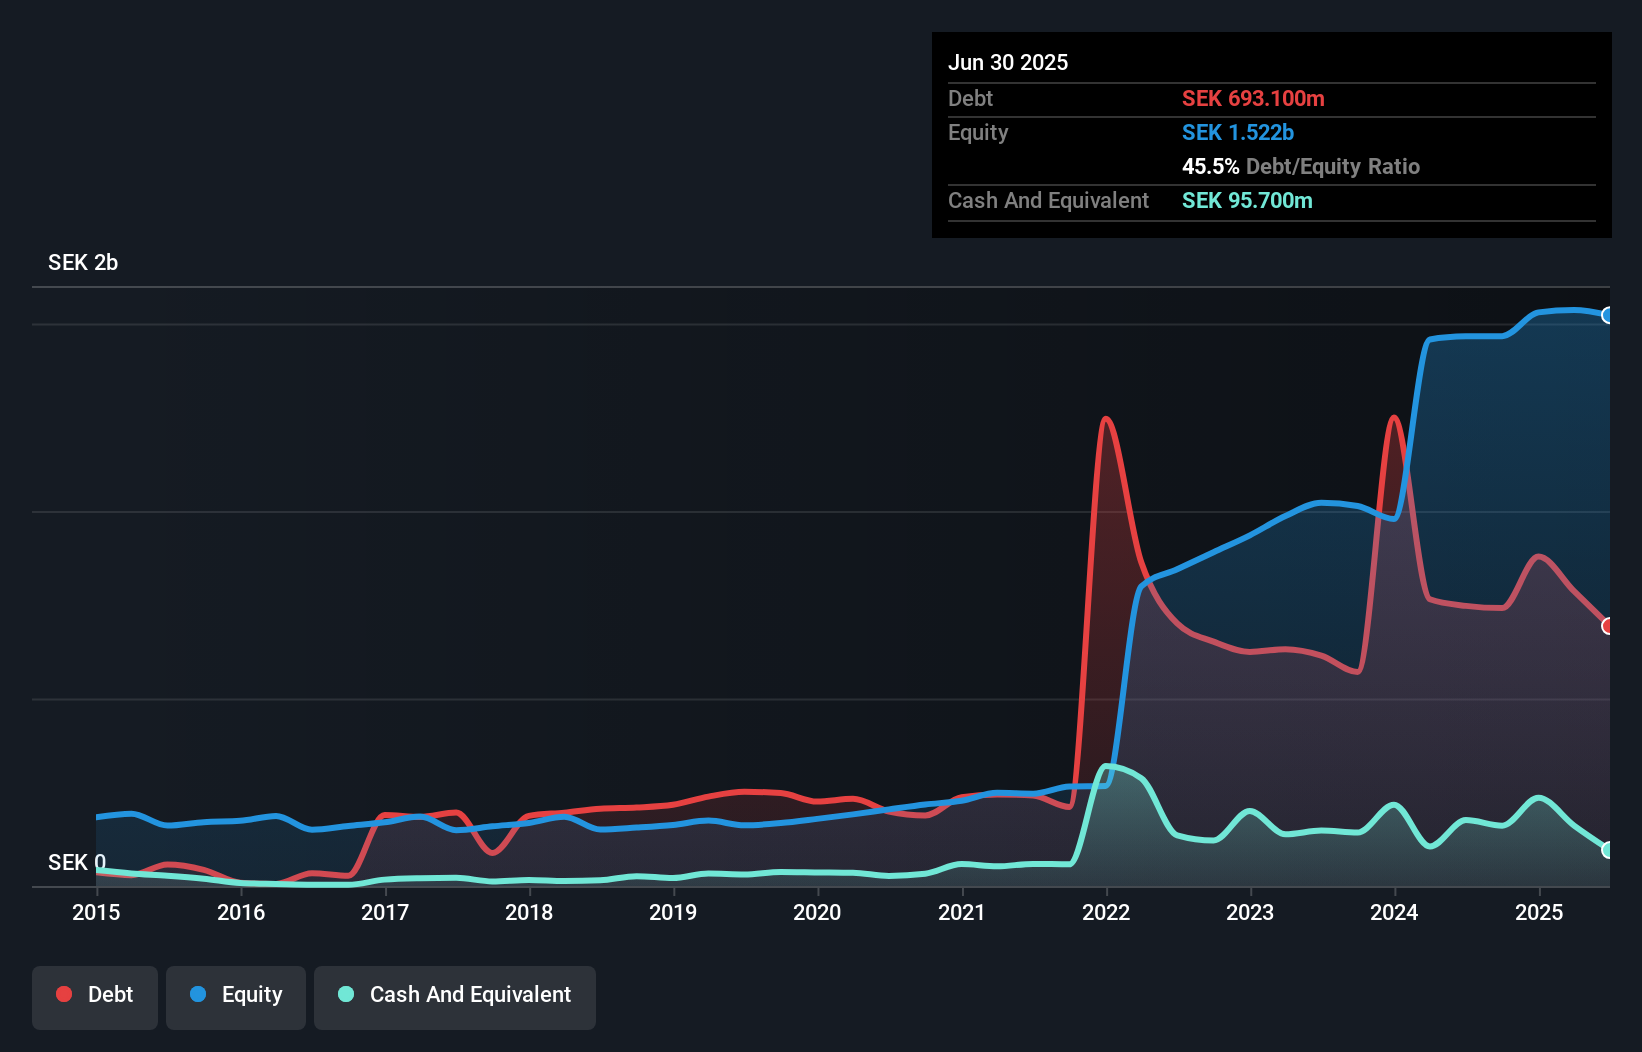
Svedbergs Group, a notable player in the building industry, showcases high-quality earnings with an impressive 18.2% growth over the past year, outpacing the industry's 12.8%. Trading at a substantial discount of 53.7% below its estimated fair value, it presents an attractive opportunity despite its high net debt to equity ratio of 66.2%. The company's EBIT covers interest payments by a robust factor of 11.4x, indicating financial strength amidst debt concerns. Recent inclusion in the S&P Global BMI Index highlights its growing recognition, even as recent earnings show slight dips compared to last year’s figures.
- Get an in-depth perspective on Svedbergs Group's performance by reading our health report here.
Gain insights into Svedbergs Group's past trends and performance with our Past report.
Phoenix Mecano (SWX:PMN)
Simply Wall St Value Rating: ★★★★★★
Overview: Phoenix Mecano AG, with a market cap of CHF 419.87 million, manufactures and sells components for industrial customers globally through its various subsidiaries.
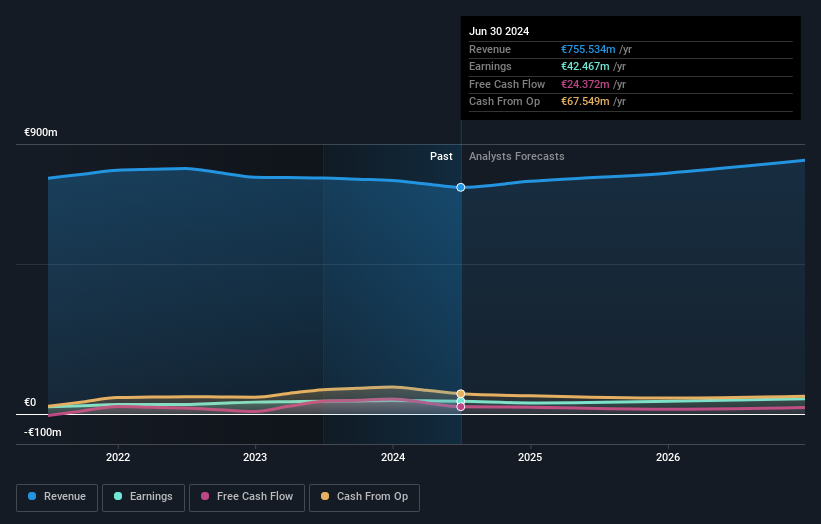
Operations: Phoenix Mecano AG generates revenue primarily through its Dewertokin Technology Group (€344.18 million), Enclosure Systems (€218.82 million), and Industrial Components (€199.05 million) segments.
Phoenix Mecano, a smaller player in the electrical industry, has shown resilience despite recent challenges. Its net debt to equity ratio improved from 98.1% to 54.2% over five years, indicating stronger financial health. The company reported sales of €383.4 million for H1 2026, slightly up from €376.6 million the previous year, with net income rising to €14.5 million from €13.9 million in the same period last year. Earnings per share increased as well, reflecting solid performance amidst sector headwinds like a -1.3% earnings growth against an industry average of -0.9%. With its earnings forecasted to grow by 13%, Phoenix Mecano presents potential for future value appreciation.
- Dive into the specifics of Phoenix Mecano here with our thorough health report.
Gain insights into Phoenix Mecano's historical performance by reviewing our past performance report.
Summing It All Up
- Embark on your investment journey to our 45 European Undiscovered Gems With Strong Fundamentals selection here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com