
How Strong Quarterly Earnings At Frequency Electronics (FEIM) Has Changed Its Investment Story
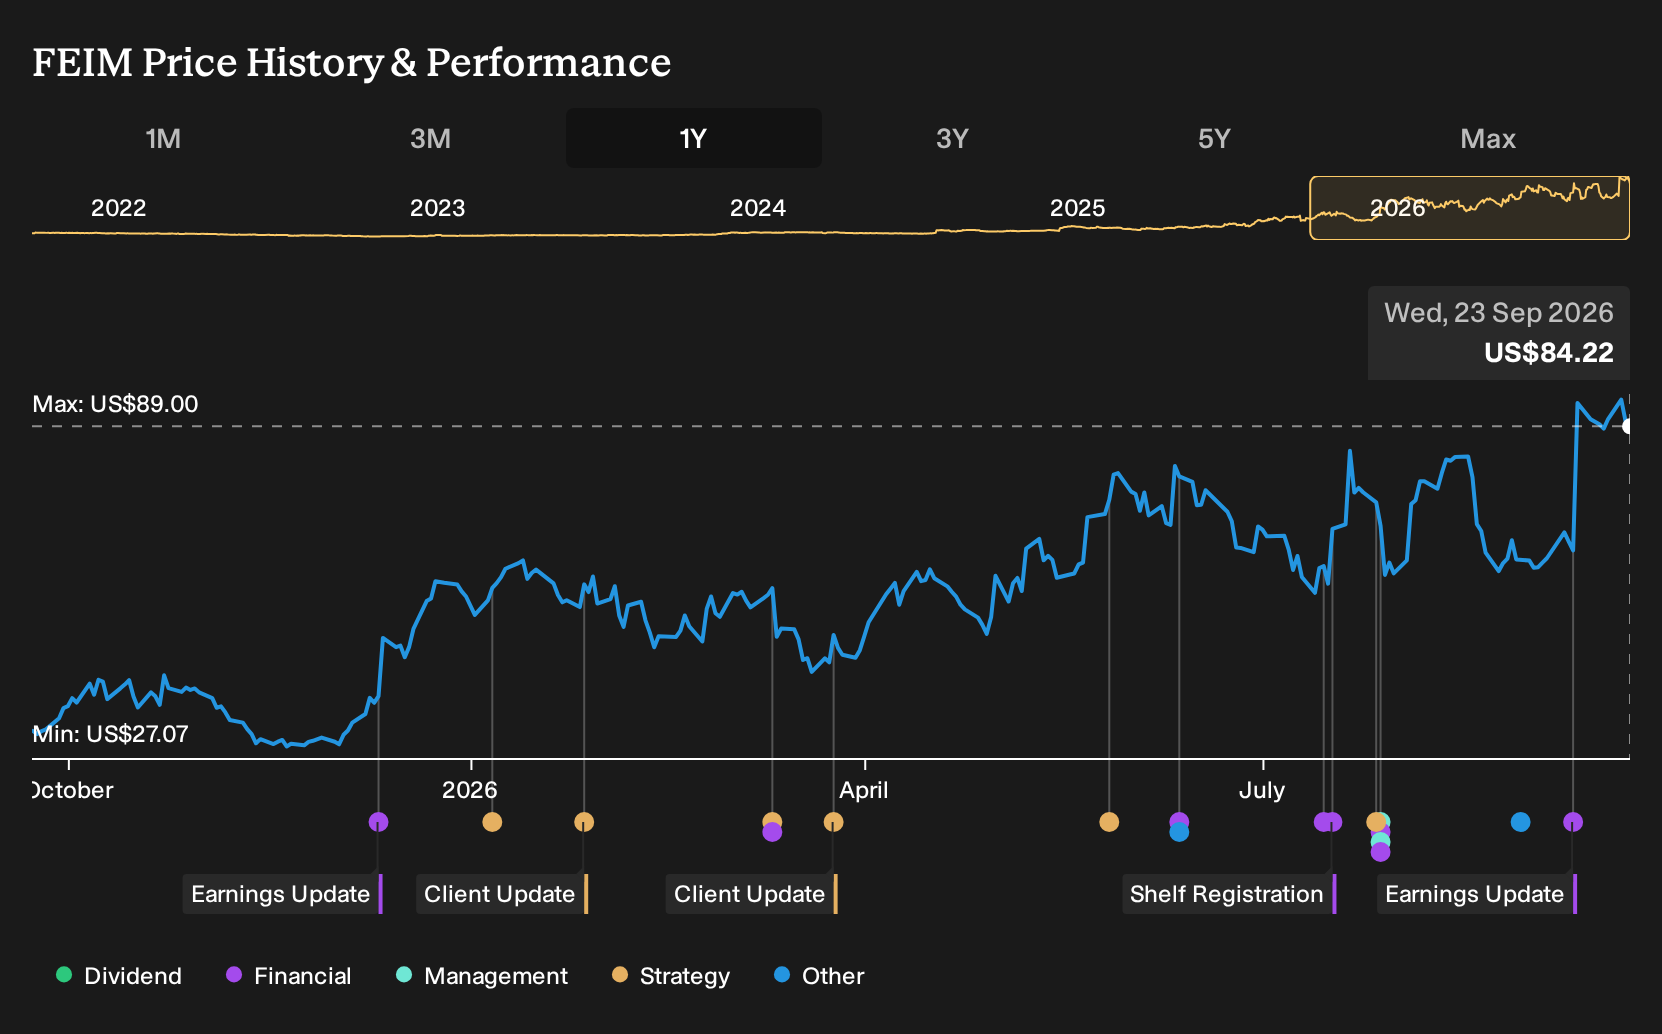
- Frequency Electronics reported first quarter 2026 results with sales of US$23.45 million, net income of US$4.22 million, and basic and diluted EPS from continuing operations of US$0.41.
- The company completed a repurchase of 22,479 shares for US$0.99 million under its September 2025 buyback plan, which modestly reduced the share count. Most of the capital appears to have been directed toward expanding the business that produced the stronger quarterly earnings.
- We will now explore how Frequency Electronics’ stronger first quarter earnings profile could influence the longer term investment narrative for the business.
Scan how Frequency Electronics’ latest buyback and first quarter earnings compare with other potential opportunities by reviewing our hand picked 16 high quality undiscovered gems in similar niches.
Frequency Electronics Investment Narrative Recap
For an investor to stay with Frequency Electronics, the belief is that demand for precision timing in space and defense programs will keep translating into a solid backlog and healthier earnings. The recent quarter shows that the firm can turn funded orders into profit. The biggest near term swing factor is still how reliably it ramps capacity without running into production snags.
The key risk today sits in that same execution. Management already describes throughput as a tight rope, so any bottlenecks in quartz manufacturing or space qualified testing could slow shipments and weigh on margins. The latest earnings do not remove that concern. They show what the model can look like when operations run close to plan.
The clearest announcement to focus on is the first quarter 2026 report. Sales of US$23.45 million and net income of US$4.22 million, with basic and diluted EPS from continuing operations of US$0.41, frame what the current manufacturing footprint is capable of when orders convert efficiently from the US$129 million funded backlog.
For catalysts, that print matters more than the completed 22,479 share buyback. It gives a reference point for how Frequency Electronics is handling long cycle space and defense projects while investing the US$73 million of fresh equity into extra capacity. The outstanding question is whether that higher throughput can be sustained without quality issues or schedule slips that would pressure the 3.7% net margin and already modest 2.2% return on equity.
Frequency Electronics Consensus Expectations In Focus
Frequency Electronics' analyst narrative points to forecast revenue of US$146.6 million and projected earnings of US$38.1 million by 2029. That profile rests on assumed revenue growth of 26.2% per year and an earnings increase of about US$35.4 million from the US$2.7 million of earnings today.
Uncover why Frequency Electronics' fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Frequency Electronics from four members of the Simply Wall St Community span from about US$0.01 to US$95.50 per share, which shows how far apart retail views can be. Set those opinions against execution risks in long cycle defense contracts and the potential catalyst of a US$129 million funded backlog, then weigh several competing viewpoints before deciding how to approach the stock.
Explore 3 other Frequency Electronics fair value estimates, including one that suggests potential upside of up to 13% from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Frequency Electronics research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Frequency Electronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Frequency Electronics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Frequency Electronics?
Once you have a view on Frequency Electronics, it helps to widen the lens and compare it with other potential opportunities that fit different risk and income profiles.
- If you want potential mispricing backed by fundamentals, scan our hand picked 30 high quality undervalued stocks and see which businesses line up with your return and risk expectations.
- For investors who care most about stability and capital preservation, filter opportunities using the 31 resilient stocks with low risk scores to find stocks that may better match a conservative approach.
- If income matters to your portfolio, focus on companies with meaningful payouts by reviewing the 7 dividend fortresses and compare their yields and balance sheets side by side.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com