
Asian Growth Companies With High Insider Ownership
Amidst the backdrop of fluctuating oil prices and evolving geopolitical tensions, Asian markets have shown resilience, with technology shares rebounding strongly after initial sell-offs. In such a volatile environment, growth companies with high insider ownership can offer a unique advantage, as this alignment often signals confidence in the company's long-term potential and strategic direction.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 116.3% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| HUMAN MADE (TSE:456A) | 23.9% | 29.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
We're going to check out a few of the best picks from our screener tool.
Akeso (SEHK:9926)
Simply Wall St Growth Rating: ★★★★★★
Overview: Akeso, Inc. is a biopharmaceutical company involved in the research, development, manufacture, and commercialization of antibody drugs globally with a market cap of HK$89.81 billion.
Operations: The company's revenue primarily comes from the research, development, production, and sale of biopharmaceutical products, totaling CN¥3.45 billion.
Insider Ownership: 18.2%
Return On Equity Forecast: 24% (2029 estimate)
Akeso, a growth company with high insider ownership in Asia, is advancing its innovative pipeline with strong clinical results. The company's bispecific antibody ivonescimab has demonstrated significant survival benefits in trials for non-small cell lung cancer and biliary tract cancer. Akeso's revenue is projected to grow at 30.8% annually, outpacing the market, with profitability expected within three years. Despite trading below fair value estimates, Akeso continues to expand its oncology portfolio through strategic clinical developments and partnerships.
- Take a closer look at Akeso's potential here in our earnings growth report.
- Our valuation report unveils the possibility Akeso's shares may be trading at a premium.
Muyuan Foods Group (SZSE:002714)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Muyuan Foods Group Co., Ltd. operates as a pork company in the hog farming industry in China, with a market cap of CN¥249.02 billion.
Operations: The company's revenue is primarily derived from its Breeding Division, which accounts for CN¥117.19 billion, followed by the Slaughtering and Meat Division at CN¥47.94 billion, and Trading at CN¥6.41 billion.
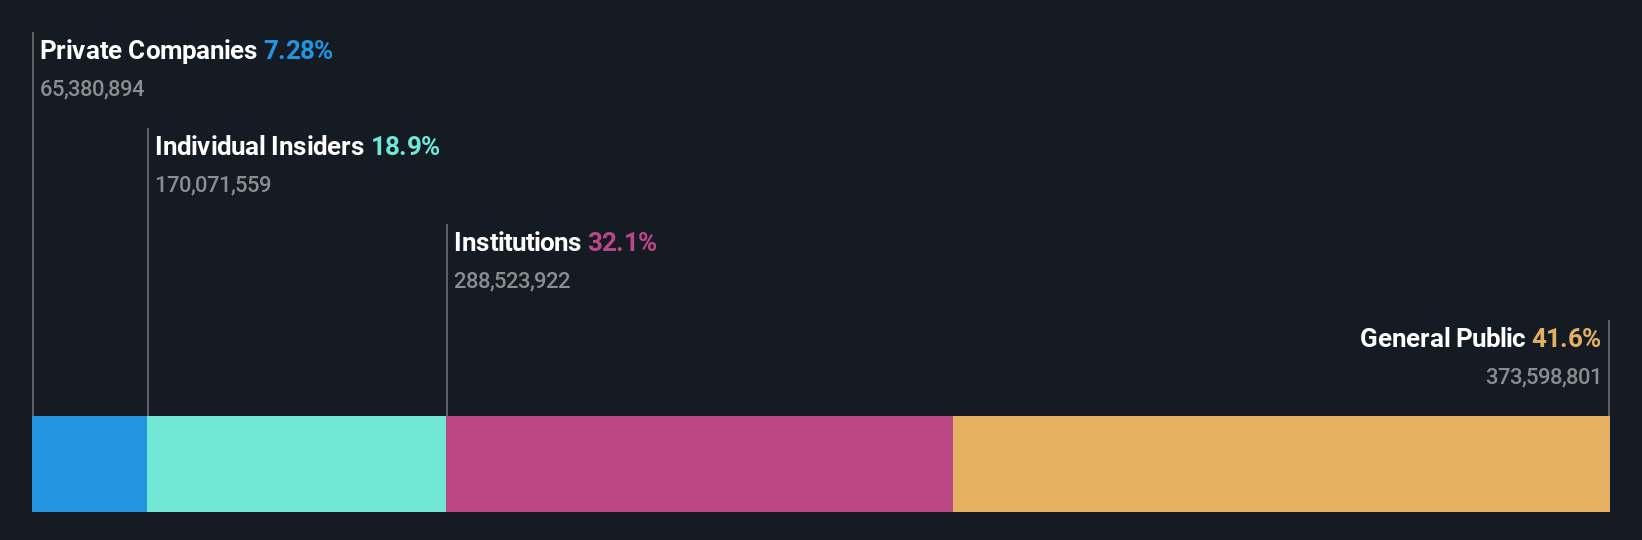
Insider Ownership: 38.3%
Return On Equity Forecast: 24% (2029 estimate)
Muyuan Foods Group is navigating challenging market conditions with high insider ownership. Despite a significant decrease in hog sales revenue and selling prices due to market fluctuations, the company is forecasted to achieve profitability within three years, outpacing average market growth. Trading at 91.4% below estimated fair value, analysts expect a 29.9% price rise. However, interest payments are not well covered by earnings, which may impact financial stability despite strong return on equity forecasts and strategic share buybacks aimed at boosting investor confidence.
- Delve into the full analysis future growth report here for a deeper understanding of Muyuan Foods Group.
- Insights from our recent valuation report point to the potential undervaluation of Muyuan Foods Group shares in the market.

ASE Technology Holding (TWSE:3711)
Simply Wall St Growth Rating: ★★★★★☆
Overview: ASE Technology Holding Co., Ltd. offers semiconductor manufacturing services globally, including in the United States, Taiwan, and Europe, with a market cap of NT$3.05 trillion.
Operations: The company's revenue is primarily derived from Packaging (NT$360.08 billion), Electronic Manufacturing Services (EMS) (NT$293.40 billion), and Testing (NT$84.64 billion).
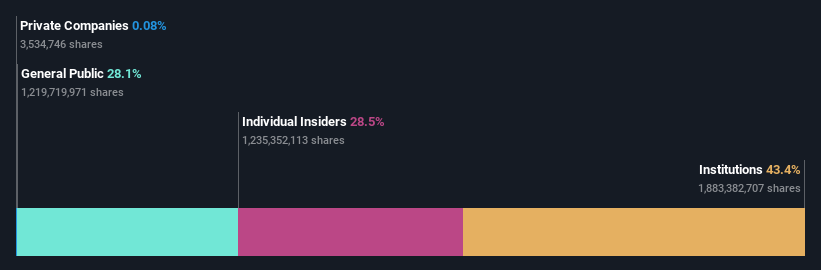
Insider Ownership: 25.8%
Return On Equity Forecast: 28% (2029 estimate)
ASE Technology Holding demonstrates high insider ownership, with insiders buying more shares than selling in recent months. The company has shown robust earnings growth, increasing by 78.1% over the past year and is expected to grow significantly at 36.4% annually, outpacing the Taiwan market's average. Recent revenue results highlight strong performance, with August revenues reaching TWD 82 billion compared to TWD 56 billion last year. However, its share price remains highly volatile and it holds a high level of debt.
- Navigate through the intricacies of ASE Technology Holding with our comprehensive analyst estimates report here.
- Upon reviewing our latest valuation report, ASE Technology Holding's share price might be too optimistic.
Next Steps
- Click through to start exploring the rest of the 490 Fast Growing Asian Companies With High Insider Ownership now.
- Looking For Alternative Opportunities? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com