
Aflac (AFL) Results Put Valuation Back In Focus
Aflac (AFL) is back in focus after reporting quarterly revenue that matched expectations, while book value per share came in ahead of estimates, prompting investors to reassess the insurer’s valuation profile.
Aflac’s latest earnings arrive after a steady climb in the share price over the past few years, with the stock now at US$115.23 and supported by ongoing product launches in Japan as well as health focused campaigns and partnerships in the U.S.
Spot fresh ideas alongside Aflac by scanning hand picked insurers and financials on our 31 resilient stocks with low risk scores, which screens for resilient balance sheets and steadier return profiles.
After a long run and a recent pullback, Aflac now forces a simple question: Does the current price still offer enough upside for the risk you are taking, based purely on valuation?
Most Popular Narrative: 3% Undervalued
Aflac’s most followed valuation story pegs fair value at about $118.53, only slightly above the last close at $115.23. This puts the focus firmly on how future cash flows and capital returns justify that small gap.
The push in Japan to sell first sector savings products such as Tsumitasu, taking advantage of a steep yen yield curve and what management describes as extremely good post reinsurance new business IRRs, can offset slower third sector premium trends and support future revenue and earnings.
See why 38 investors see Aflac as 3% undervalued.
Result: Fair Value of $118.53 (UNDERVALUED)
Still, pressure on Japan premiums and a higher benefit ratio around the top of guidance could quickly challenge the idea that Aflac is modestly undervalued.
Find out about the key risks to this Aflac narrative.
Another View on Aflac’s Valuation
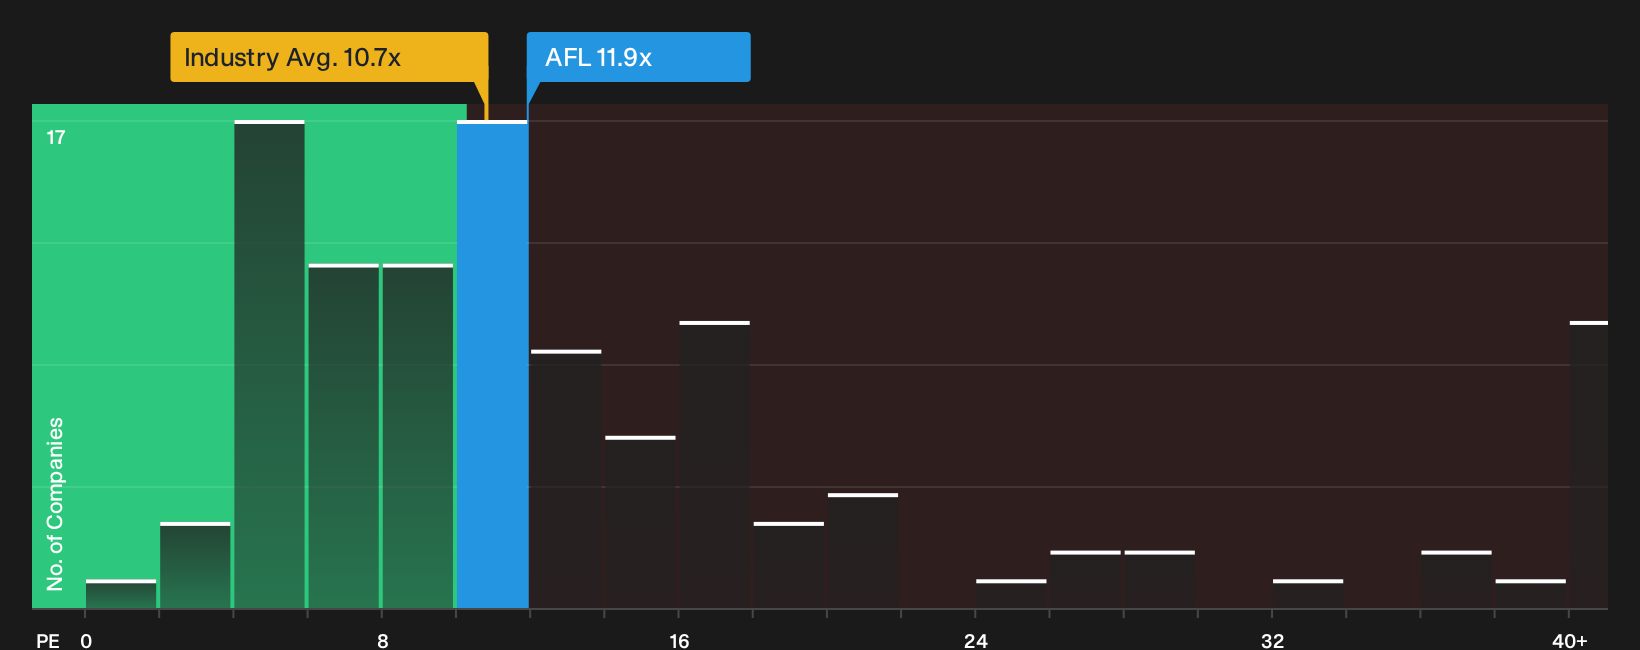
Price-based signals paint a different picture. Aflac trades on a P/E of 11.9x compared with a fair ratio of 9.7x, which points to a richer valuation, while that same 11.9x is cheaper than the peer average at 16.3x and slightly above the wider US insurance sector on 10.7x.
So one model flags value and another suggests investors are already paying up on earnings. This leaves a simple question: which signal do you trust more if profit trends soften from here? Is it the cash flow model, or what the earnings multiple is already baking in, and how much room does that really leave for error before sentiment turns?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Aflac can be useful if you treat them as a prompt rather than an answer, so move quickly and stress test your own thesis using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Aflac?
If Aflac sharpened your focus on valuation and quality, you can keep that momentum going by searching for other opportunities where fundamentals, risk, and price still align.
- Target better value by scanning companies that combine solid balance sheets with attractive pricing through the 30 high quality undervalued stocks.
- Build a steadier income stream by reviewing businesses with higher yields and payout consistency via the 7 dividend fortresses.
- Prioritise resilience by filtering for stronger financial foundations and healthier fundamentals using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com