
Top 3 Canadian Undervalued Stocks Trading Up To 43% Below Fair Value
Central banks are lifting interest rates to contain stubborn inflation, and that puts reliable cash generation front and center for investors. Higher borrowing costs can hurt companies that depend on cheap debt, while strong free cash flow can act like a built in safety buffer. This article looks at three Canadian stocks that our cash flow value screen flags as trading below estimated fair value and explains why they might deserve a closer look.
The three stocks below are just a starting sample from this cash flow value idea, and the full screen surfaced 1 more company with an equally compelling story that is not covered here. Head straight into the Undervalued Stocks Based On Cash Flows screener to identify, filter, and analyze the highest conviction opportunities from this list.
OceanaGold (TSX:OGC)
Overview: OceanaGold is a Canada headquartered miner that runs gold and gold copper operations in the United States, the Philippines, and New Zealand, with producing assets driving its cash flow story.
Operations: Revenue is concentrated at the Haile mine with US$796 million, Macraes at US$781 million, Didipio at US$549 million, and Waihi at US$338 million supporting group cash generation.
Market Cap: CA$9.1b
OceanaGold matters for this cash flow focused screen because its producing gold and copper mines already generate the cash that underpins discounted cash flow value. A pipeline of extensions and upgrades aims to stretch that cash generation further into the future.
"Advancing Waihi North and Wharekirauponga, with fast track permitting and expanded drilling capacity, positions the company to bring on a large, high grade underground ore body that can materially extend reserve life and underpin higher long term earnings."
The real swing factor for OceanaGold’s cash flow story is how the evolving mix of capital spending and operating costs shapes future margins.
That margin question is exactly what sits behind the full narrative for OceanaGold, which unpacks how OceanaGold’s cash engine could accelerate or stall as those choices play out.
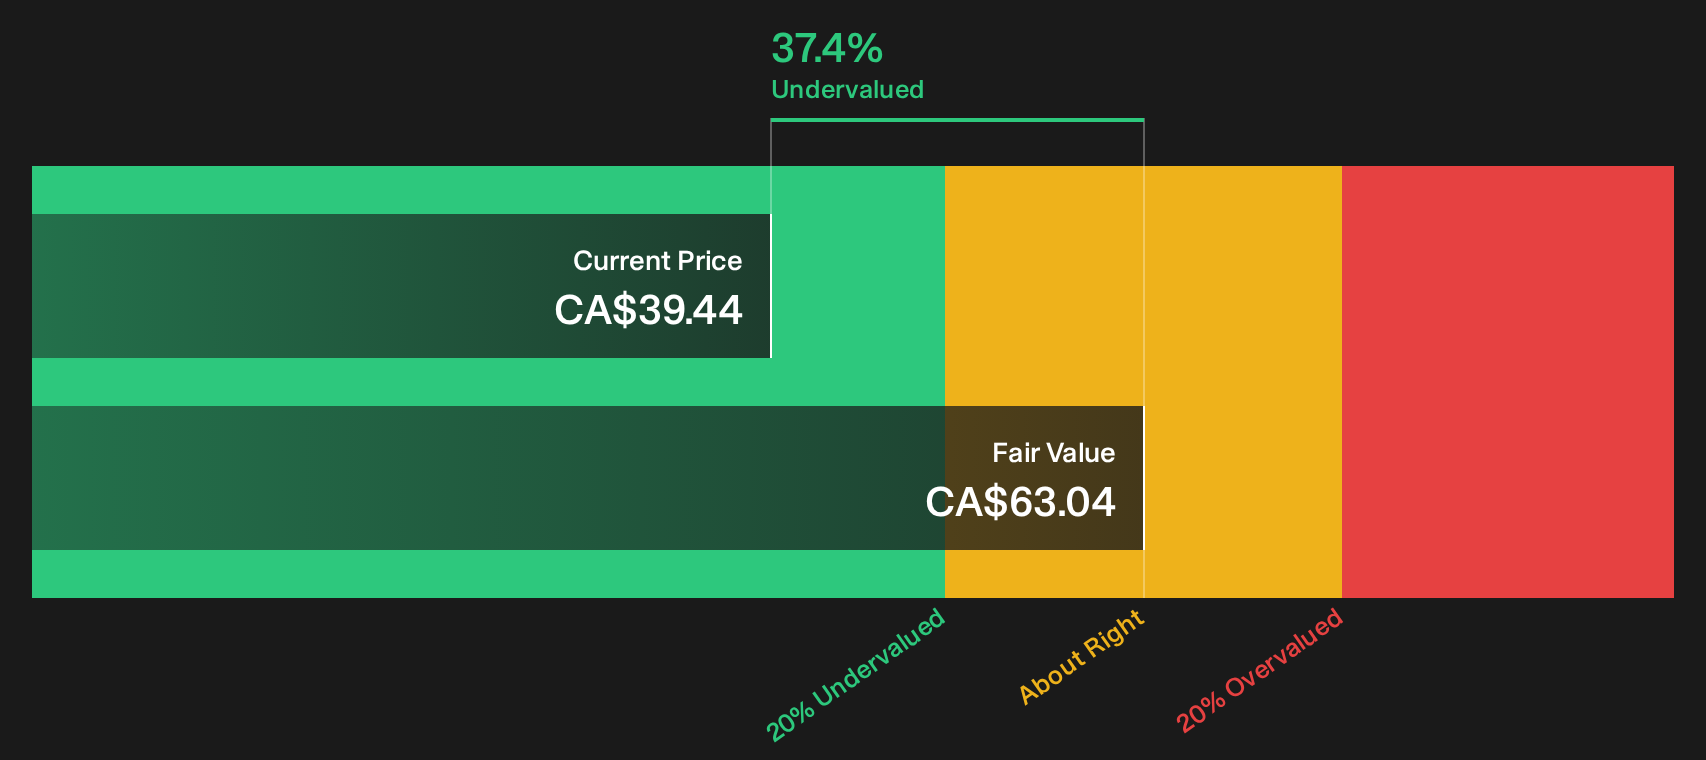
Savaria (TSX:SIS)
Overview: Savaria designs and installs home and commercial accessibility equipment and adapted vehicles, while also supplying patient handling products for healthcare settings.
Operations: Savaria generates about CA$739 million from Accessibility and adapted vehicles and CA$209 million from Patient Care across Canada, the US and Europe.
Market Cap: CA$2.1b
For the Undervalued Stocks Based On Cash Flows theme, Savaria matters because its Accessibility segment turns installed elevators, stairlifts and adapted vehicles into steady service, maintenance and retrofit cash flows that can support a discounted cash flow valuation anchored in long-term demand for aging and mobility solutions.
"Ongoing global demographic shifts, namely population aging and increased urban density, are expected to affect demand for home accessibility solutions (e.g., elevators, stairlifts), providing a potential backdrop for Savaria's revenue over time as these trends evolve.
What really moves the needle for Savaria now is how one quiet pressure on profitability plays out against those long-lived service revenues.
That quiet squeeze on profitability is exactly what the full narrative for Savaria unpacks, separating temporary margin drag from longer term earnings power as accessibility demand continues to accelerate.

Suncor Energy (TSX:SU)
Overview: Suncor Energy is an integrated Canadian producer that turns long life oil sands bitumen and offshore output into refined fuels and petrochemical products.
Operations: Suncor Energy generates about CA$26.9b from Oil Sands, CA$36.8b from Refining and Marketing, and CA$2.5b from Exploration and Production, offset by CA$9.5b of corporate eliminations.
Market Cap: CA$110.1b
For cash flow focused investors, Suncor Energy matters because its oil sands operations provide long lived production that can underpin years of operating surplus even as refining and marketing earnings move around.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels."
The real test for Suncor Energy’s cash flow story is what happens if one quiet constraint on that high throughput model finally bites into margins.
When that constraint starts to bite, the full narrative for Suncor Energy shows how reliability risks could collide with cash flow ambitions, while other moving parts quietly shift the earnings mix.

Seeking Fresh Alternatives Before They Fly
Market momentum shifts fast and the next breakout lists rarely stay under the radar for long. Scan these fresh ideas before prices get caught moving and consider your options promptly.
- Track cash rich, steady operators that may hold up when volatility spikes by running your filters through the list of solid balance sheet and fundamentals (7 results).
- Focus on compounding payouts from companies built around durable cash returns by zeroing in on the 1 dividend fortresses before yields change.
- Explore opportunities ahead of potential infrastructure buildout cycles by scanning the 39 power grid technology and infrastructure stocks while these grid modernisation stories are still less widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com