
Sunshine Silver Mining And Refining (SSMR) Could Be 18% Below Fair Value On Idaho Expansion
Sunshine Silver Mining & Refining (SSMR) has just expanded its mineral rights in Idaho’s Silver Valley by about 60% to roughly 38,000 acres, while launching a multi-year 45,000-meter surface drilling program.
For investors watching the ticker, Sunshine Silver Mining & Refining’s latest expansion comes after a 90 day share price return of 18.36%, even as the 30 day share price return has slipped 16.95% and the year to date share price return is down 8.28% from a recent level of US$15.73. This suggests that enthusiasm around growth potential is being weighed against fresh risk in the near term, while momentum over the past quarter remains intact.
Scan the silver space for other potential breakouts by comparing Sunshine Silver Mining & Refining with a hand picked 10 top silver producer stocks built around producers with similar exposure to the metal.
Sunshine Silver Mining & Refining has already logged a strong three month move, yet the pullback and large reported discount to some value estimates raise a sharper question. Is most of the upside already in the rearview, or does the current price still leave meaningful room on the table once the valuation work is done?
Most Popular Narrative: 18% Undervalued
Against the last close of $15.73, the prevailing narrative for Sunshine Silver Mining & Refining points to a fair value near $19.20, so the current pullback is being judged as a discount rather than a warning sign.
The Sunshine Mine resource sits at very high grades with an envisioned 24 year mine life. This provides sizeable potential silver volumes that can scale as feasibility work, drilling and mine development mature and could be supportive for future revenue and operating leverage.
See why 1 investors see Sunshine Silver Mining & Refining as 18% undervalued.
Result: Fair Value of $19.20 (UNDERVALUED)
Still, the story around Sunshine Silver Mining & Refining only holds if pre production timelines stay on track and if fresh funding does not cause heavy dilution.
Find out about the key risks to this Sunshine Silver Mining & Refining narrative.
Another View On Sunshine Silver Mining & Refining’s Valuation
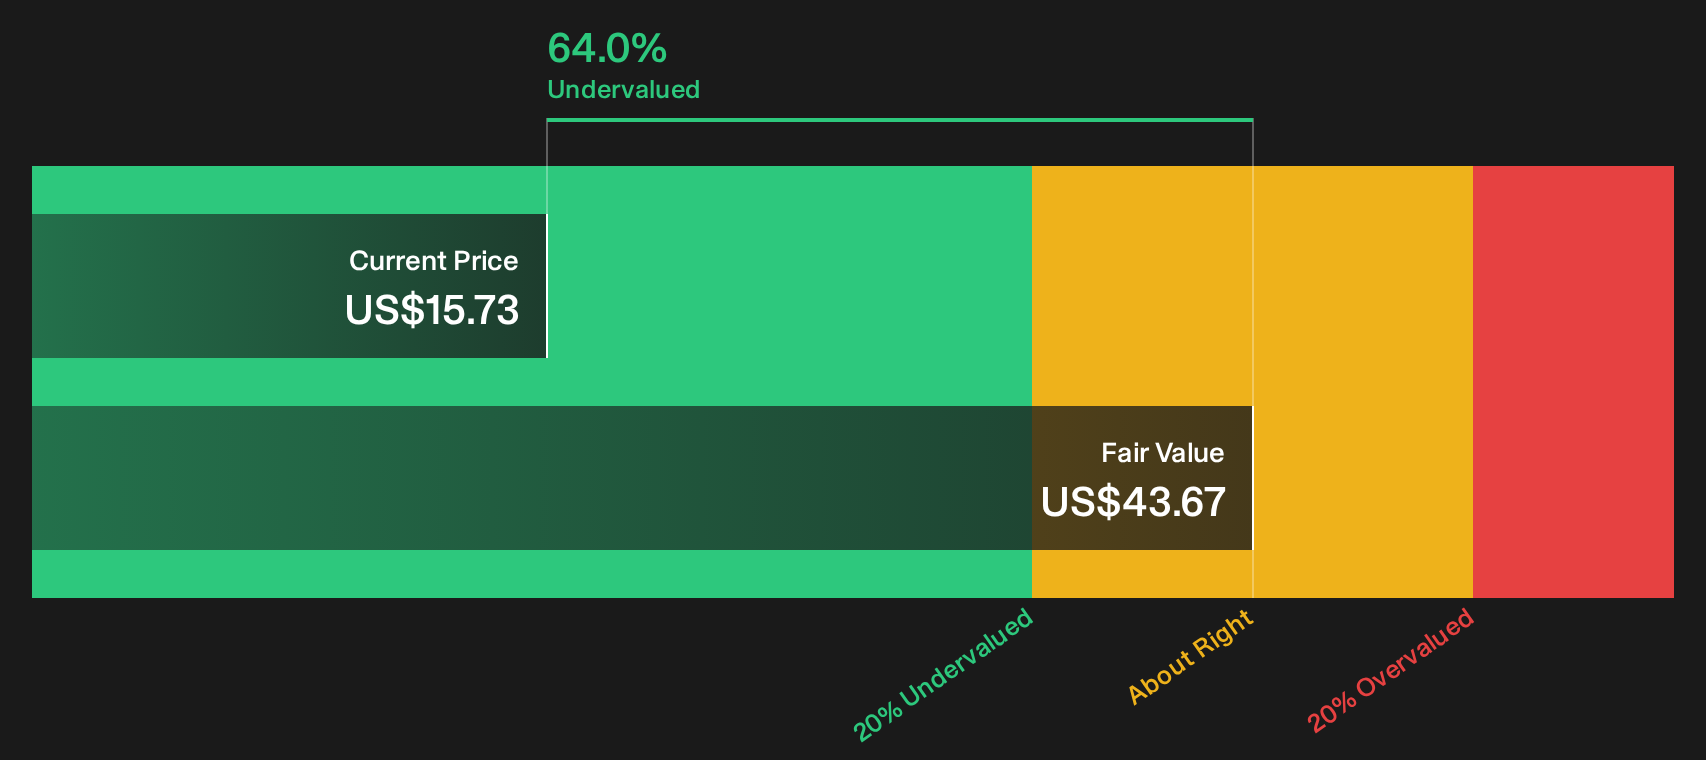
On one hand, Sunshine Silver Mining & Refining screens as deeply undervalued using the SWS DCF model, which pegs future cash flow value near $43.67 against the recent $15.73 share price. On the other hand, the stock trades on a rich 7x P/B compared with 2.4x for the wider US Metals and Mining group. This raises a key question: how comfortable are you paying a premium multiple for a project still before first production?
Investors who want to see how this cash flow view is built can go straight to the SWS DCF model breakdown here Look into how the SWS DCF model arrives at its fair value..
Next Steps
Sentiment around Sunshine Silver Mining & Refining is split, with optimism on potential value and concern around execution risk sitting side by side. Move quickly, review the numbers and let the full set of 4 key rewards and 2 important warning signs guide your own conclusion.
Looking for more investment ideas beyond Sunshine Silver Mining & Refining?
If Sunshine Silver Mining & Refining has your attention, broaden your watchlist with other clear-cut setups that could complement or challenge your current thinking.
- Scan for potential value opportunities that pair strong fundamentals with discounted prices by reviewing the 30 high quality undervalued stocks that match your risk tolerance.
- Focus on companies that prioritize resilience and balance sheet strength by working through the curated list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio.
- Look for underfollowed opportunities with quality metrics by checking the focused 16 high quality undiscovered gems before others catch on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com