
Dynatrace (DT) Could Be 1% Overvalued As Sopra Steria Alliance Lifts The Debate
Why Dynatrace’s Sopra Steria Alliance Matters Now
Sopra Steria’s new observability and AIOps practice with Dynatrace (DT) gives the software group a structured entry point deeper into large European IT estates across banking, insurance, telecoms, retail and government.
The partnership integrates the Dynatrace platform into Sopra Steria’s consulting, delivery and managed services model, with joint governance and dedicated certified teams designed to embed a single, real time view of infrastructure and applications directly into long term client relationships.
Recent moves suggest momentum is building in Dynatrace shares, with a 30 day share price return of 19.3% and a 90 day gain of 45.3%. However, total shareholder return over five years is still down 16.6%, so the shorter term rally contrasts with a weaker long run picture.
Scan other AI observability and infrastructure plays moving on similar themes with our curated 85 AI infrastructure stocks as you weigh what this Sopra Steria alliance could mean for Dynatrace.
Dynatrace now trades only slightly below average analyst targets, yet screens at a deeper intrinsic discount after a sharp 90 day run. Is the market wisely cautious, or just slow to re-rate the Sopra Steria effect?
Most Popular Narrative: 1% Overvalued
Dynatrace closed at $58.51 against a widely followed fair value of $58.18, leaving the story finely balanced and putting extra weight on how investors view its AI observability push and capital returns over the next few years.
The company's unified platform approach, particularly the growing success of Grail-powered log management (over 100% YoY log consumption growth and targeting $100M in annualized consumption), is driving multi-product adoption and higher customer stickiness, which should improve net retention rates, recurring revenue, and long-term earnings predictability.
See why 52 investors see Dynatrace as 1% overvalued.
Result: Fair Value of $58.18 (OVERVALUED)
Still, rising competition from hyperscalers and open source tools, plus longer, lumpier enterprise deal cycles, could quickly test the bullish Dynatrace narrative.
Find out about the key risks to this Dynatrace narrative.
Another View On Dynatrace’s Valuation
While the fair value narrative pegs Dynatrace right around $58, the SWS DCF model points to a future cash flow value closer to $70.60, which frames the current $58.51 price as undervalued. If cash flows track those assumptions, is the market underpricing the long haul here?
Look into how the SWS DCF model arrives at its fair value with Look into how the SWS DCF model arrives at its fair value.
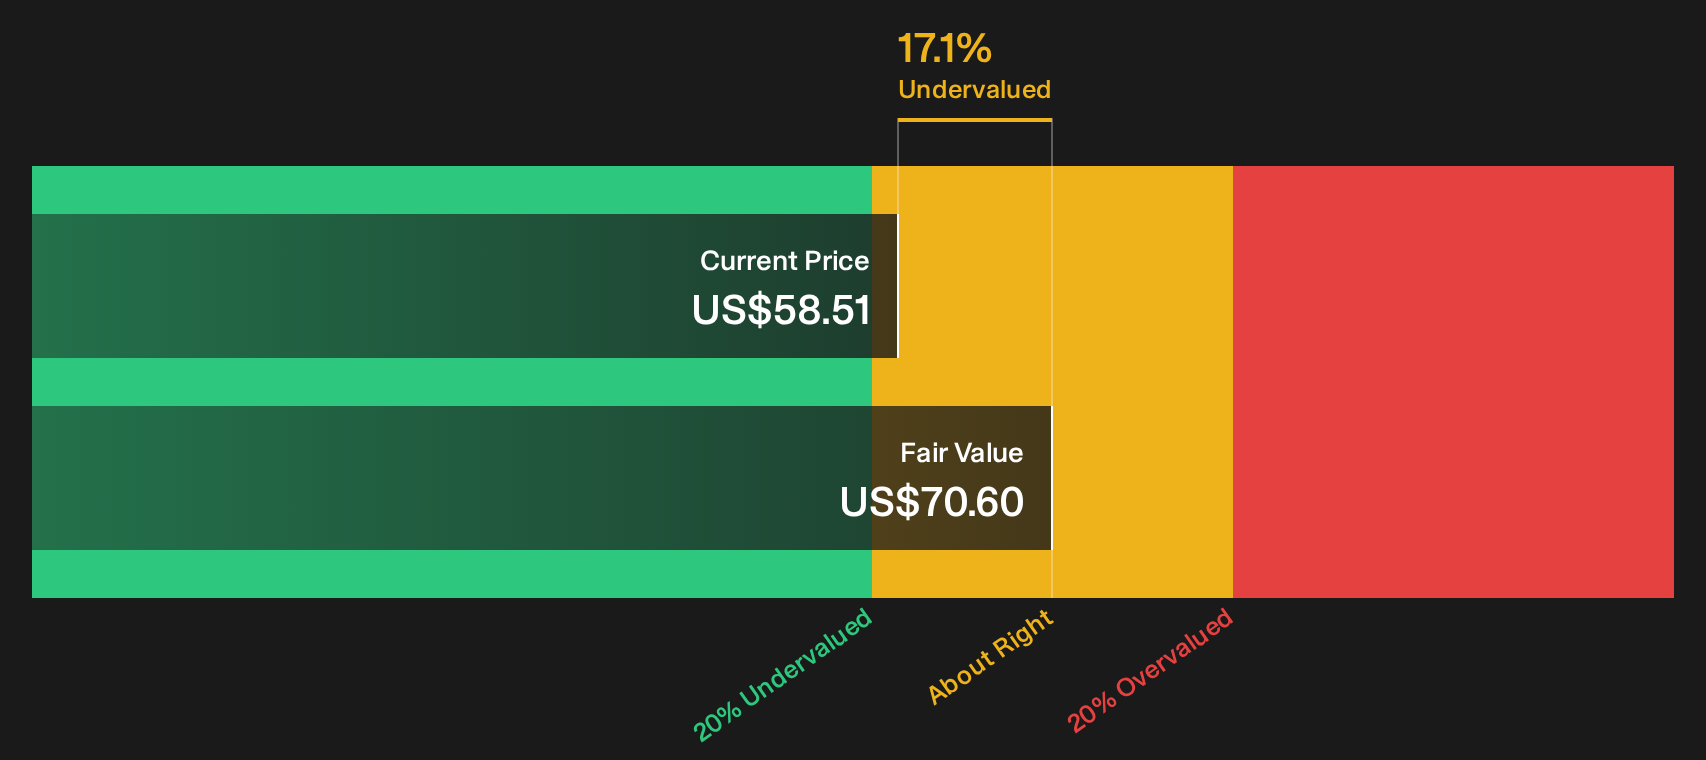
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dynatrace for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Dynatrace so far. Short term optimism, a fair value debate and a cash flow gap all point to doing your own homework quickly. To frame that view against both the upside potential and the concerns already flagged by other investors, start with 2 key rewards and 1 important warning sign.
Want More Ideas Beyond Dynatrace?
If Dynatrace has your attention, you can broaden the opportunity set and pressure test your thesis by lining it up against fresh ideas from the Simply Wall Street Screener.
- Target durable compounding by checking out a 31 resilient stocks with low risk scores that could help reduce portfolio shock when sentiment swings.
- Pursue quality at a discount through a 16 high quality undiscovered gems that may not yet be widely followed.
- Strengthen your core holdings by reviewing a list of solid balance sheet and fundamentals (23 results) that can help you sleep better when markets get noisy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com