
Does Enel (BIT:ENEL) Trade At A Premium After Its $760 Million Solar Deal?
Enel has delivered a powerful 80.4% gain over the past three years, yet the stock has recently cooled. That mix of strong long term returns and shorter term weakness puts fresh focus on whether today’s share price lines up with its earnings power. With the group also active on the deal front, investors are asking if the current valuation properly reflects what the utility’s profit engine can support.
- An 80.4% return over three years means long term holders have already banked a sizeable gain, so every extra euro in the share price now leans heavily on what Enel can sustainably earn.
- The recent US$760 million purchase of a 625MW US solar portfolio adds contracted cash flows and may support expectations for steadier earnings from long term power purchase agreements.
- Your read on Enel is one view; the desks covering it have another. See what analysts think Enel's shares could be worth.
The stock’s next move may depend on whether Enel’s current earnings justify the price investors are being asked to pay today.
If you are weighing Enel against other utilities with earnings in focus, it helps to compare it with a basket of 39 power grid technology and infrastructure stocks.
Where Does Enel Sit on Earnings?
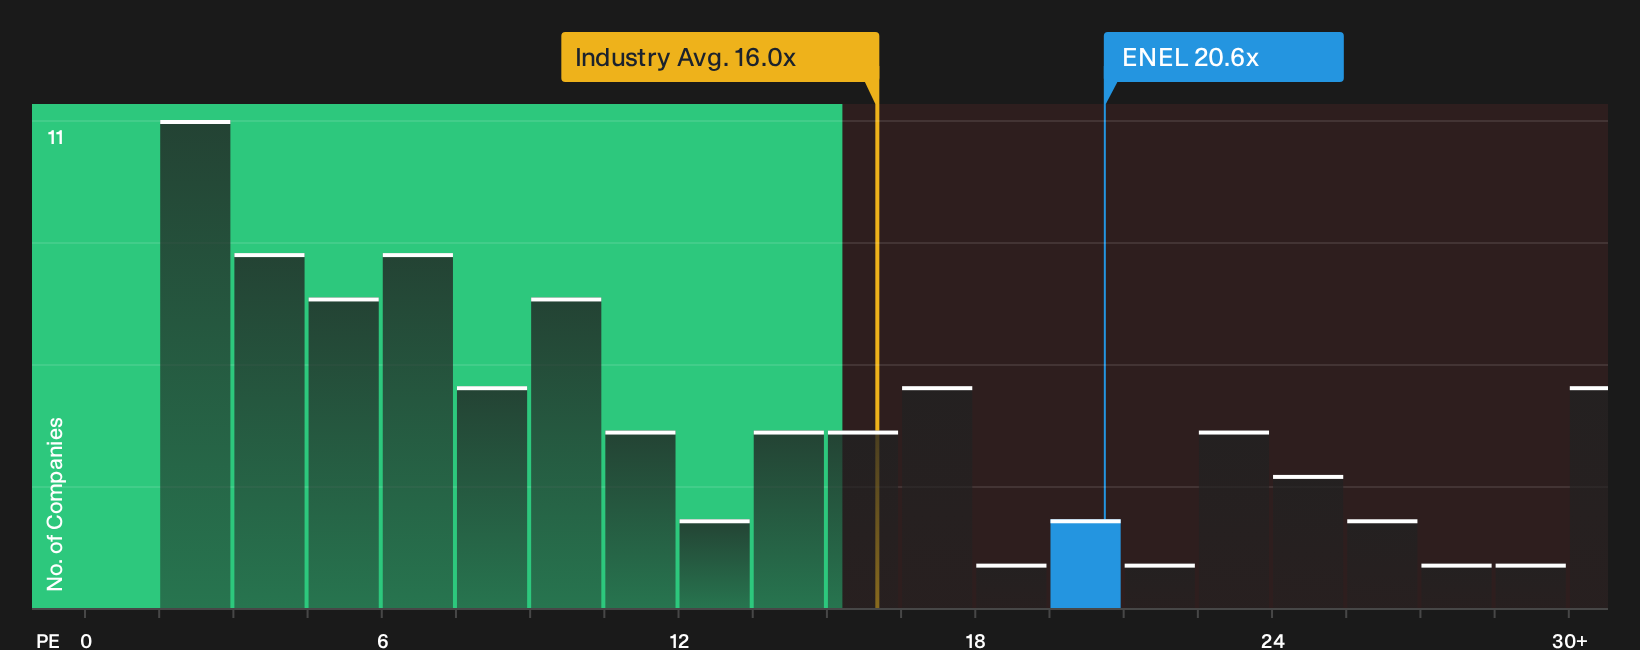
The P/E ratio fits Enel because earnings remain the key anchor for a regulated utility with steady contracted cash flows. On this measure, the stock trades on about 20.6x, which is higher than the Electric Utilities sector average of roughly 14.3x but lower than the peer group on about 27.3x.
That puts Enel close to the level suggested by a tailored fair multiple that factors in its size, risk profile and profit quality, so the current P/E looks broadly in line with what those fundamentals might support. Because the recent US$760 million US solar acquisition adds earnings backed by long term power purchase agreements, the market appears willing to pay a premium to the wider industry even though the shares do not command a peer level valuation. Explore the numbers behind Enel's P/E valuation.
The Enel Narrative: What Would Justify Today's Price?
Narratives for Enel pick up where the P/E puzzle leaves off and explain which paths for future growth, profitability and earnings would need to occur for the current share price to look meaningfully high or low. Each one is set up as a clear, testable view about Enel's underlying business rather than a fixed fair value snapshot, so you can see how that thesis holds up as new information arrives on the Community page.
One of the top community narratives on Enel: 14% undervalued
"Enel's significant investment in digitalization (e.g., smart grids, automation, BESS capacity now at 11.5GW) and grid modernization is yielding improved operational efficiency, evidenced by €1 billion in cash cost savings already realized toward its 2027 target..."
Discover why this Narrative puts Enel at 14% undervalued.
Enel's price tag is only one piece of the decision
Enel’s valuation story is only half the picture, because the research checks also raise specific cautions that could reshape how you judge the whole opportunity. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com