
Castellum (OM:CAST) Stock Looks About Right As Earnings Set The Pace
Castellum has delivered solid gains over the past few years, yet the share price has still not climbed back from a sizeable five year decline. With the stock now around SEK 126.75, the live question is whether that level is supported by the earnings that the property group is generating today.
- Over the last 5 years the share price has fallen 23.7%. This puts the current valuation debate squarely on whether the earnings profile can justify a recovery from that drop.
- The business model is built on rental income from a large property portfolio. Rent levels, occupancy and financing costs can all feed directly into the profit base that investors use when judging the P/E and other earnings multiples.
- Your read on Castellum is one view; the desks covering it have another. See what analysts think Castellum's shares could be worth.
For investors, the debate is whether Castellum's current price fairly reflects what its earnings suggest the stock should be worth.
If you are weighing whether Castellum's earnings fully support today’s share price, it can help to compare that question across 172 high quality undervalued stocks.
Where Does Castellum Sit on Earnings?
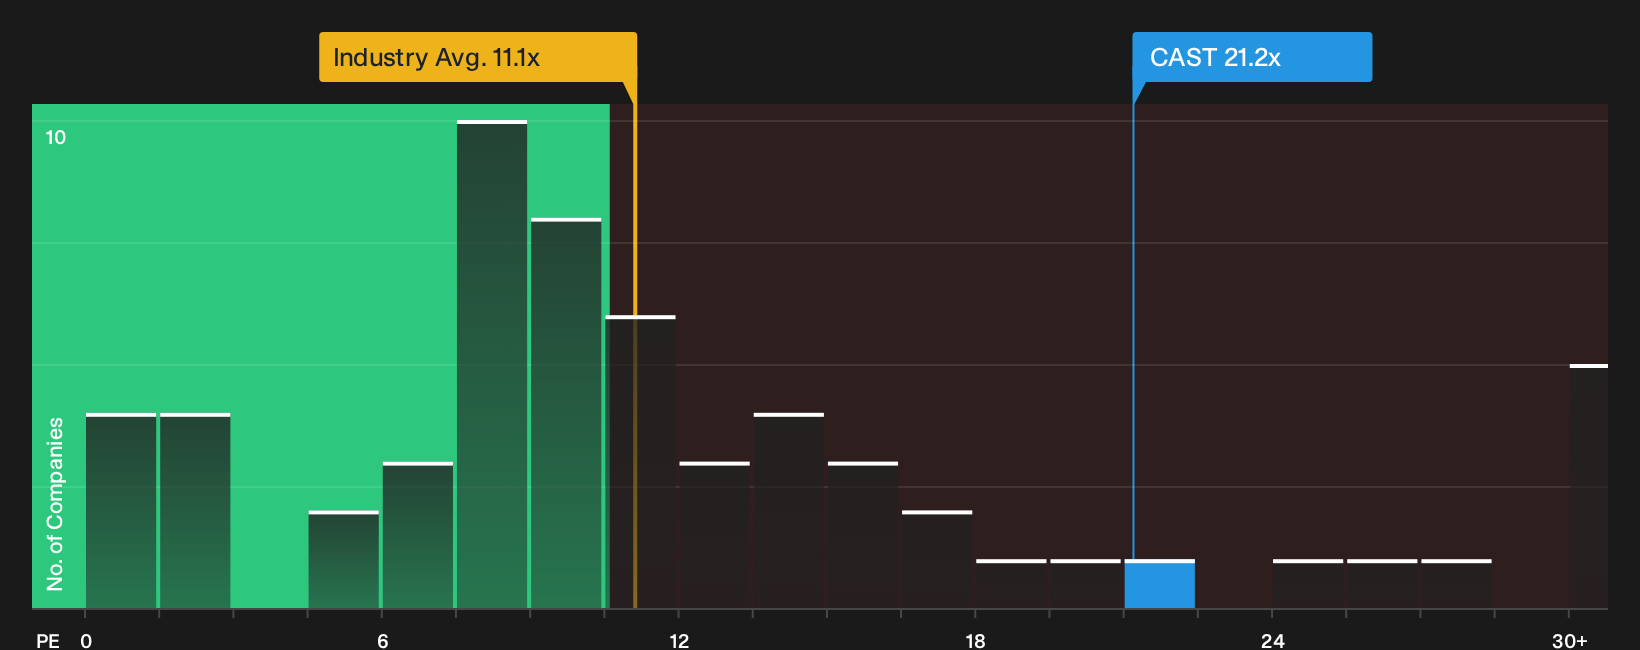
The P/E ratio fits Castellum reasonably well because this is a mature property owner where earnings power sits at the centre of the story. On this metric, the stock trades on roughly 21.2x earnings, compared with a Real Estate sector average of about 11.1x and a broader peer group around 10.6x, so you are paying a clear premium for each krona of profit.
A tailored fair P/E, which blends the company’s own earnings profile, risk and scale, points to a level very close to where Castellum trades today, so the current multiple sits only slightly above that marker. For anyone weighing the shares, the key question is whether the rental portfolio, balance sheet and cash generation are strong enough to keep justifying that roughly 21x tag rather than a lower sector type multiple. Explore the numbers behind Castellum's P/E valuation.
The Castellum Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Castellum pick up where the valuation question leaves off by explaining which potential paths for earnings, margins and rental income would need to occur for the stock to appear meaningfully higher or lower than today’s price. Each narrative presents a complete set of assumptions behind its estimate of fair value so you can compare those expectations with Castellum's actual results over time on the Community page.
Community views on Castellum split between those who see extra upside from current projects and buybacks and those who think the stock already reflects most of that story.
Bull case: 8% undervalued
"Castellum plans to reinvest proceeds from divested non-strategic properties into refurbishment, tenant improvements, and new project developments, anticipated to enhance property values and rental income over time..."
Discover why this Narrative puts Castellum at 8% undervalued.
Bear case: roughly fairly valued
"The persistent shift toward remote and hybrid work continues to erode demand for traditional office space in key Nordic metropolitan areas, with Castellum reporting higher vacancies and a deteriorating occupancy rate now at 90.3 percent..."
Explore why this Narrative puts Castellum at roughly fairly valued.
One more angle on Castellum that could change the story
Rental income and earnings only tell part of Castellum's story, because the people choosing projects, setting risk appetite and deciding how cash is shared are just as important. See who runs Castellum and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com