
Is Brown & Brown (BRO) Below Fair Value As Partnership And Leadership Changes Unfold?
Brown & Brown’s partnership move and leadership shift
Brown & Brown (BRO) is back in the spotlight after joining Financial Executives International’s Strategic Partnership Program, a move paired with a fresh leadership appointment in its North American employee benefits operation.
Brown & Brown’s share price has pulled back sharply in the short term, with the 7 day share price return down 6.3% and the 1 month share price return down 17.3%. By contrast, the 5 year total shareholder return of 13.7% points to a more resilient long run picture and suggests recent momentum has faded as investors reassess risk and near term expectations around the new partnership and leadership changes.
Capitalize on the reset in Brown & Brown by comparing it to hand picked insurers and financials in the 31 resilient stocks with low risk scores.Brown & Brown now trades well below recent analyst and intrinsic value estimates after the pullback. Is that discount justified by fresh uncertainty, or does it overshoot fair value based on current fundamentals?
Most Popular Narrative: 19% Undervalued
Against Brown & Brown’s last close of $61.70, the most followed narrative points to a fair value of $76.50, which frames the recent pullback as a steeper discount than the long term thesis implies.
Brown & Brown is rolling out AI enabled submission, policy checking and billing tools that are already saving tens of thousands of hours a year and automating more than 25% of the submission process in many programs. This can free producers and underwriters to handle more volume and support future organic revenue growth and operating margin resilience.
See why 29 investors see Brown & Brown as 19% undervalued.
Result: Fair Value of $76.50 (UNDERVALUED)
Still, the story around Brown & Brown could change quickly if producer departures accelerate or if CAT exposed property premiums keep shrinking and put pressure on key program revenues.
Find out about the key risks to this Brown & Brown narrative.
Another View on Brown & Brown’s valuation
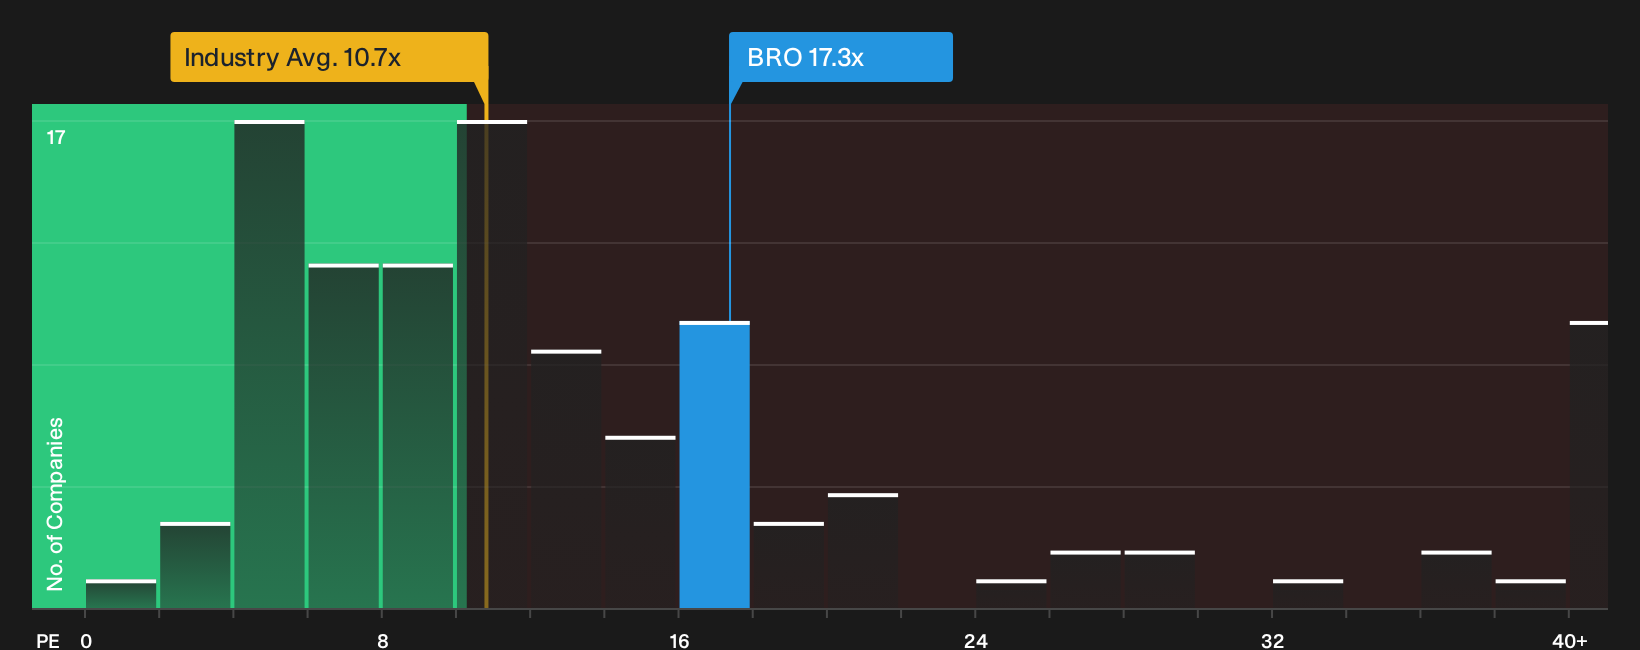
While the narrative leans on analyst fair value of $76.50, the current P/E of 17.3x tells a different story. Brown & Brown trades richer than the US Insurance industry at 10.7x, yet cheaper than peers at 28.8x and above its fair ratio of 12.6x. Is that a margin of safety or valuation risk?
For investors weighing what this gap means in practice, the valuation breakdown using this earnings multiple helps frame how much optimism is already in the price and how much room there is if sentiment cools or improves from here. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does this mixed sentiment around Brown & Brown leave you curious rather than convinced? Act while the information is fresh and weigh both sides through the 3 key rewards and 2 important warning signs.
Looking for more Brown & Brown investment ideas?
Do not stop at Brown & Brown. Fresh opportunities rarely wait, and the right shortlist can change how you think about risk, income, and upside across your portfolio.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive valuations through the 30 high quality undervalued stocks.
- Strengthen your income stream by checking out resilient payers with higher yields using the 7 dividend fortresses.
- Focus on financial resilience by reviewing a curated list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com