
SentinelOne (S) Is Back In The Spotlight, But What Is The Market Weighing?
SentinelOne (S) gained fresh attention after its shares rose about 5% as lower Treasury yields and easing U.S.-China frictions improved risk appetite for software stocks ahead of a high-profile summit.
The latest move also extends a strong run for SentinelOne. The 30-day share price return of 15.75% feeds into a 90-day gain of 61.10% and a year-to-date share price return of 64.62%. The 1-year total shareholder return of 32.49% and 3-year total shareholder return of 49.23% contrast with a 5-year total shareholder return that declined 55.68%, suggesting momentum has picked up recently even as longer term holders still sit on sizeable losses.
Surf 38 profitable AI stocks that aren't just burning cash, which pairs AI-driven growth stories like SentinelOne with stronger current profitability, to see how this recent sentiment shift compares across the sector.SentinelOne now trades within a narrow gap to the average analyst target, yet still at a clear discount to some intrinsic value estimates. Is this surge closing the opportunity or just starting to reflect fair value?
Most Popular Narrative: 60% Undervalued
On the most followed narrative, SentinelOne carries a fair value estimate of $24.25, only a touch above the last close at $24.10. This puts today’s move into context as investors weigh how much of the story is already reflected in the price.
Expansion beyond endpoint security into high-demand adjacent markets such as cloud security, identity, and data protection, including the Prompt Security acquisition for GenAI risk, unlocks significant cross-sell opportunities and is expected to elevate average contract value and diversify revenue streams, laying the groundwork for outsized multi-year revenue growth.
See why 95 investors see SentinelOne as 1% undervalued.
Result: Fair Value of $24.25 (UNDERVALUED)
Still, SentinelOne’s dependence on partners like hyperscalers and rising regulatory hurdles overseas could pressure margins and limit how quickly the growth narrative plays out.
Find out about the key risks to this SentinelOne narrative.
Another View On SentinelOne’s Valuation
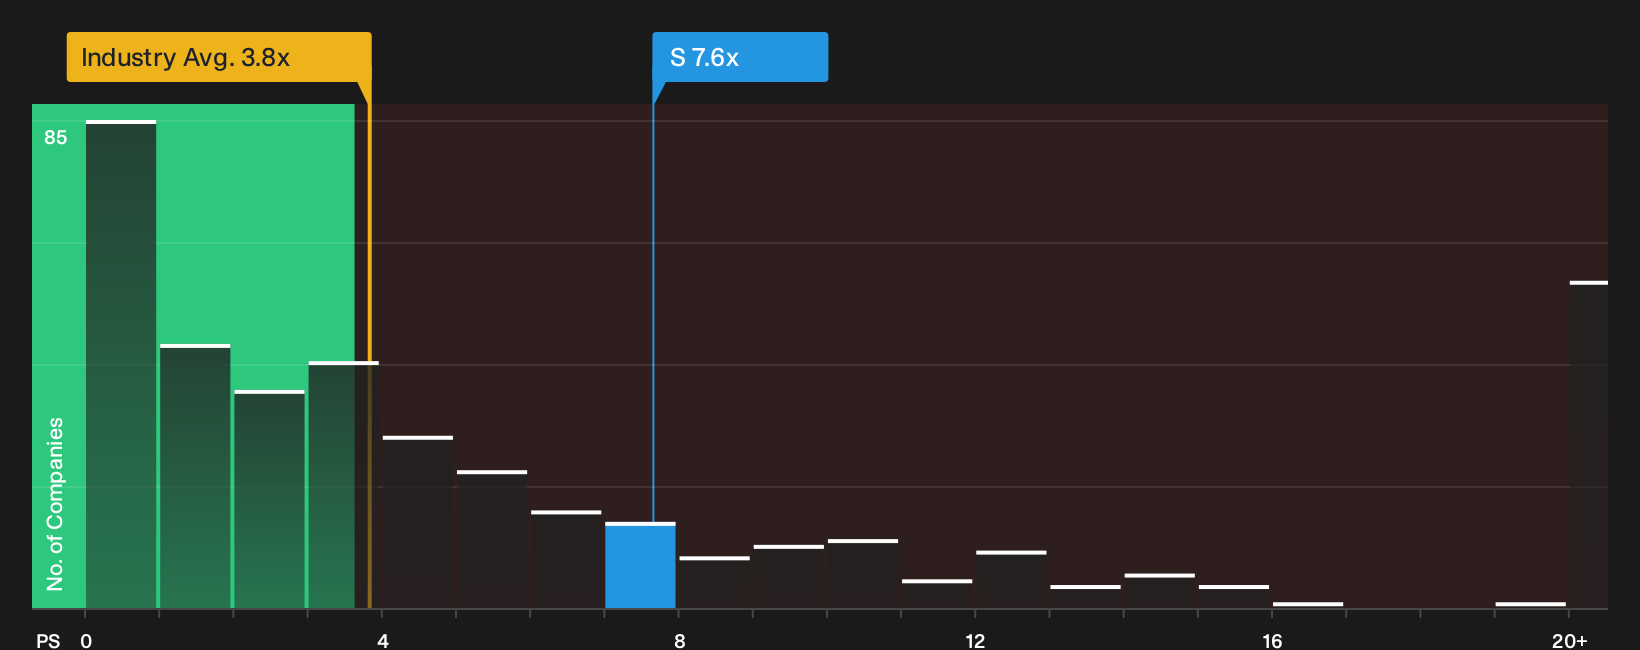
The first narrative leans on future cash flows and analyst forecasts, yet SentinelOne’s current trading level also reflects how much investors pay for each dollar of revenue. The stock changes hands at a P/S ratio of 7.6x, compared with 3.8x for the wider US Software group and a fair ratio estimate of 6x for this business.
That gap points to a richer pricing profile than both the sector and the fair ratio suggest. This can mean higher expectations and less room for error, even when DCF work flags upside. The key question for you is whether SentinelOne can support that premium over time, or whether the market pulls the multiple back toward the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed sentiment around SentinelOne has you undecided, move quickly to review both sides of the story and test your own thesis. Compare the 2 key rewards and 2 important warning signs with your expectations and decide where you stand.
Looking for more SentinelOne style investment ideas?
SentinelOne may already be on your radar, but you leave money on the table if you stop at a single stock when better fits could be waiting.
- Target potential mispricings by scanning a curated set of 30 high quality undervalued stocks that combine quality fundamentals with pricing that still looks appealing.
- Strengthen your defensive side by reviewing a list of solid balance sheet and fundamentals (23 results) that can help steady your portfolio when sentiment swings.
- Get ahead of the crowd by searching through 16 high quality undiscovered gems that already show strong financial footing before they hit the mainstream.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com