
GE Vernova (GEV) Could Be 25% Undervalued After Record Backlog And Electrification Wins
Recent news around surging AI power needs and record electrification orders has put GE Vernova (GEV) back in focus for investors watching grid and generation suppliers.
Against that backdrop, GE Vernova’s share price has pulled back meaningfully from its recent peak, yet the 90 day share price return has declined 12.31% while the year to date share price return of 40.07% and 1 year total shareholder return of 51.67% point to momentum that has been built on record backlog updates, data center electrification wins, and fresh long duration turbine service agreements such as the Egypt deal.
Scan other power grid and AI-infrastructure plays riding the same electrification theme as GE Vernova through our hand picked 39 power grid technology and infrastructure stocks today.
GE Vernova has already logged eye catching gains and a sharp pullback. The real tension now sits in the numbers: whether current valuation still leaves meaningful upside or has already absorbed most of the story.
Most Popular Narrative: 25% Undervalued
Against GE Vernova’s last close at $951.82, the most followed narrative anchors fair value at $1,269.77. This implies a sizable gap that the story argues is tied to earnings quality, cash generation, and AI driven electrification demand rather than just hype around recent share price moves.
Financially, the company is showing significant operating leverage. Free cash flow surged to $4.8 billion in Q1 2026 alone, exceeding the company’s entire FY2025 free cash flow generation. Operating margins have also improved sharply, moving from deeply negative levels in 2022 to positive mid-single digits today. Investors are betting that this margin expansion story is still in its early stages, with further gains expected as manufacturing utilization improves and higher-margin service revenue becomes a larger portion of the mix.
See why 57 investors see GE Vernova as 25% undervalued.
Result: Fair Value of $1,269.77 (UNDERVALUED)
Still, GE Vernova’s story can break if AI data center demand slows, or if the loss making Wind segment consumes more cash and drags on returns.
Find out about the key risks to this GE Vernova narrative.
Another View: GE Vernova Through Cash Flows
There is a very different reading of GE Vernova once cash flows are put at the center. The SWS DCF model places future cash flow value at $840.09 per share, below the current $951.82 price, which screens as overvalued rather than discounted on this measure.
For investors weighing which lens to trust, the question is whether earnings quality and growth can close that DCF gap or whether the market is already paying up for the AI power story.
Look into how the SWS DCF model arrives at its fair value.
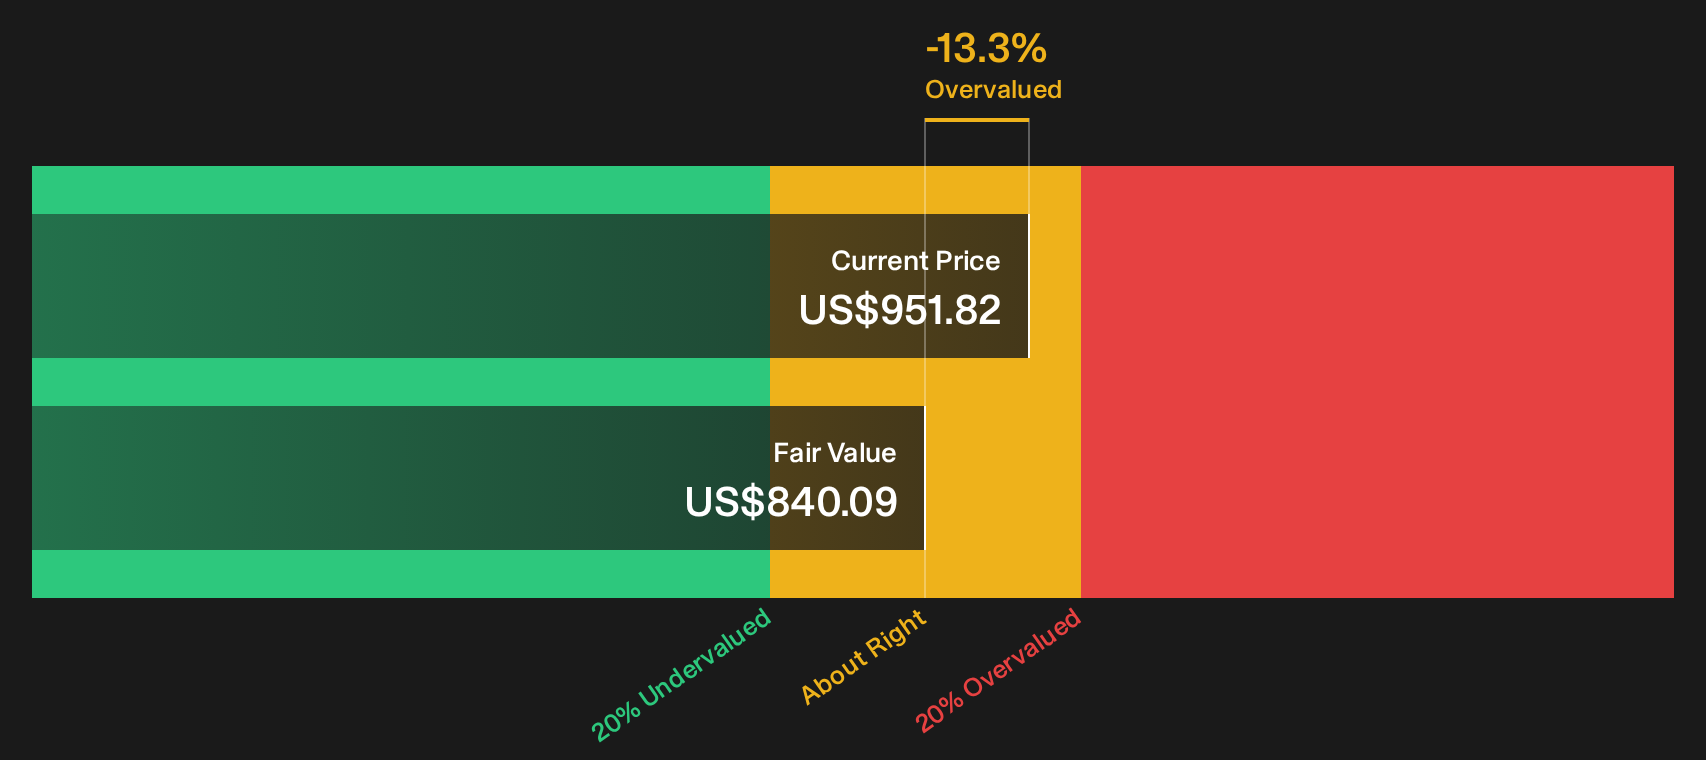
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out GE Vernova for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around GE Vernova can make the story feel crowded, so move fast. Pull up the full risk and reward breakdown, and weigh the 5 key rewards and 1 important warning sign.
Looking for more GE Vernova style investment ideas?
If GE Vernova has your attention, do not stop at a single opportunity. Broaden your watchlist now with focused lists that surface clear, data backed ideas.
- Explore potential upside by filtering for quality companies trading below estimated value with the 30 high quality undervalued stocks.
- Support portfolio resilience by focusing on businesses with clean finances and healthy fundamentals using the list of solid balance sheet and fundamentals (23 results).
- Identify earlier stage opportunities by scanning a curated set of smaller, higher risk investments via the 9 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com