
Will BECCS Supply Deal Change Alfa Laval Stock Narrative
- Alfa Laval was selected by Saipem to supply Ziepack gas gas interchangers and several plate and frame heat exchangers for Stockholm Exergi's BECCS plant, a bioenergy carbon capture facility in Europe that aims to capture, liquefy and store up to 800,000 tonnes of CO2 annually.
- The contract underlines Alfa Laval's role as a core equipment supplier for large scale carbon capture processes, linking its heat transfer portfolio directly to projects that depend on high efficiency and reliable heat recovery in energy transition infrastructure.
- This section examines how Alfa Laval's role in this large BECCS heat transfer contract could influence the broader investment narrative.
Scan other potential beneficiaries of large scale carbon capture build outs by reviewing the hand picked 19 nuclear energy infrastructure stocks that sit closest to this Alfa Laval BECCS theme.
Alfa Laval Investment Narrative Recap
To own Alfa Laval, you need to believe the push for energy efficiency, decarbonization and water treatment keeps translating into a healthy mix of equipment and higher margin service work. The Stockholm Exergi BECCS award fits that belief, but by itself it does not change the near term picture. It mainly reinforces that Alfa Laval kit is being specified into complex carbon capture projects.
The key short term catalyst remains order momentum in energy transition and marine environmental solutions. The largest risk is still delayed project decisions coupled with exposure to cyclical sectors like oil and gas and marine. Cost inflation, higher S&A and competition in heat exchangers and heat pumps could also pressure margins if order intake slows.
The BECCS contract lines up cleanly with the broader energy transition theme that already underpins Alfa Laval. Management has been pushing into areas like hydrogen plate technology, cryogenics and heat pumps. A high profile carbon capture win illustrates how that product set can be pulled through into large EPC led projects. For you, it is another reference site rather than a standalone financial swing factor today.
Service growth and digitalization remain crucial. The recurring service stream already sits above 30% of group sales and 40% in Marine, which matters because BECCS and similar assets require long term maintenance and optimization. If Alfa Laval can attach multi decade support contracts to more of these projects, that would help counterbalance risks from lumpy capital orders, currency swings and any future softness in traditional marine pumping or oil and gas work.
What The Current Alfa Laval Forecasts Assume
Alfa Laval's narrative projects SEK 91.2b revenue and SEK 11.6b earnings by 2029. That profile is based on analysts' assumption of 9.0% yearly revenue growth and an earnings increase of about SEK 3.4b from SEK 8.2b today.
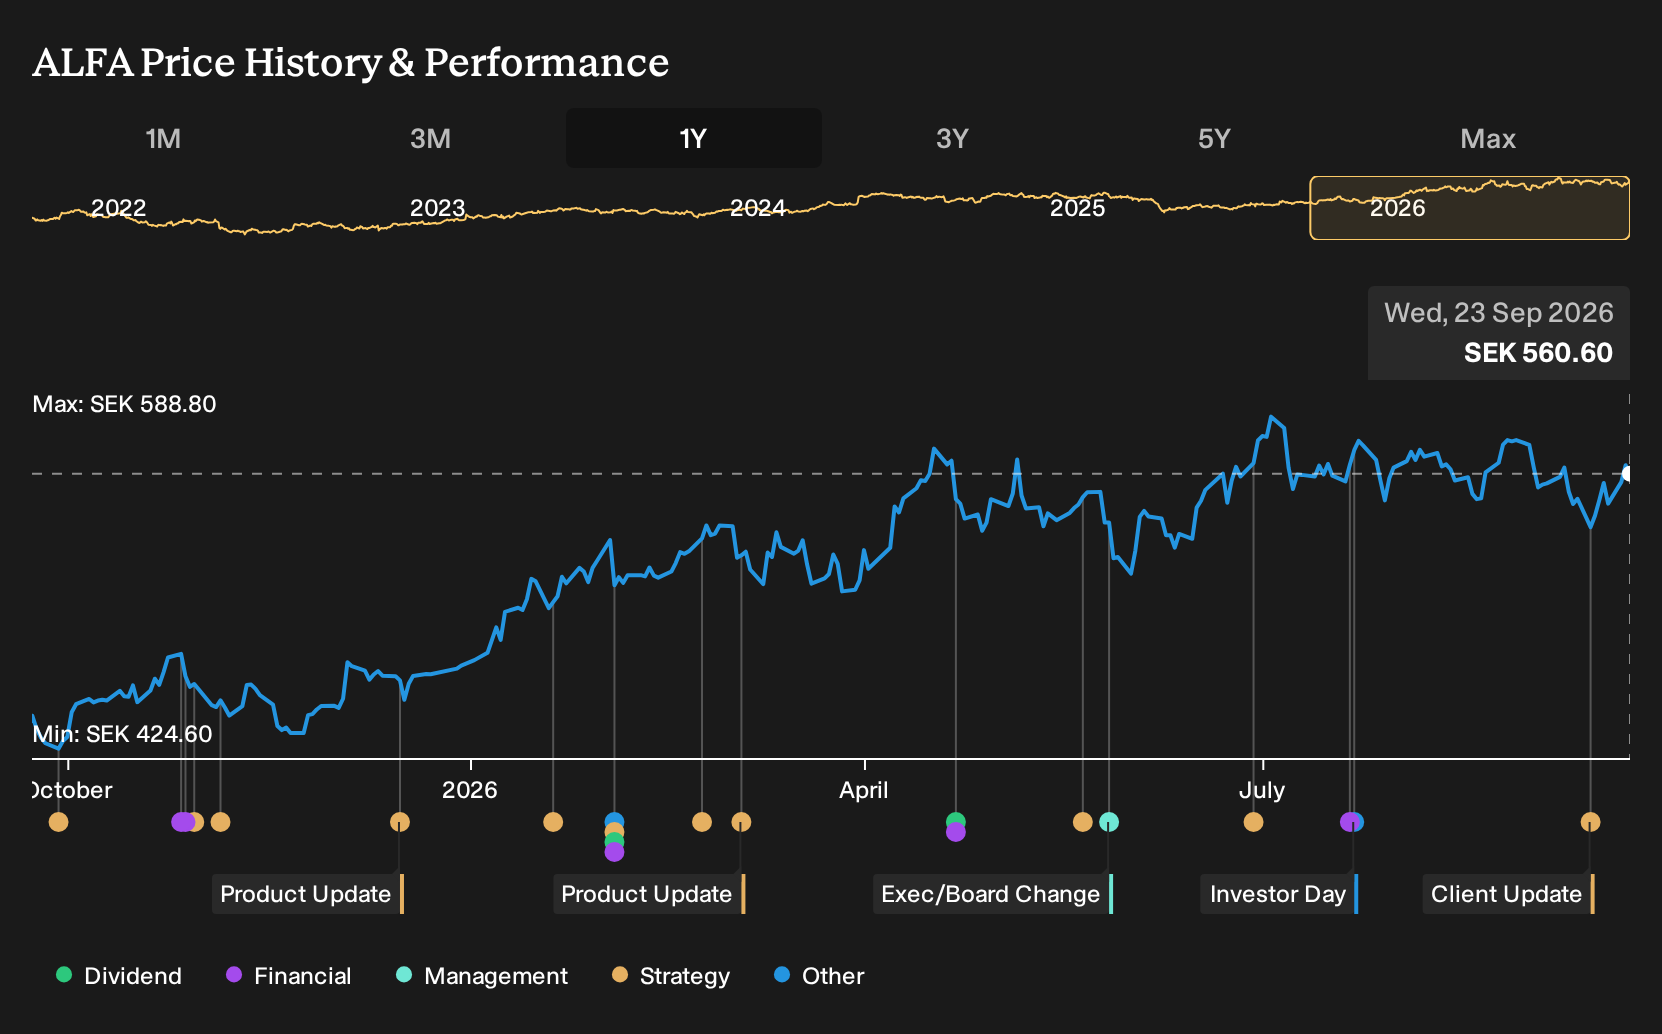
Uncover why Alfa Laval's fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on the risk that faster decarbonization makes Alfa Laval’s legacy fossil fuel equipment less relevant. The most cautious analysts were only pencilling in SEK 84.6b revenue and SEK 10.5b earnings by 2029 before this BECCS news. That is a much more pessimistic story. Use that gap as a prompt to explore different forecasts and decide which narrative appears closer to your own expectations.
Explore 4 other Alfa Laval fair value estimates, including one that suggests as much as 30% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Alfa Laval research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Alfa Laval. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alfa Laval's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alfa Laval?
If the Alfa Laval story has you thinking about how to spread risk and find other angles on energy transition and industrial themes, the Simply Wall St Screener can help you scan the wider market quickly.
- For investors who want a margin of safety first, consider companies that screen well on valuation and quality using our hand picked 172 high quality undervalued stocks.
- If capital preservation and balance sheet strength matter most to you, filter for businesses with robust finances through the list of solid balance sheet and fundamentals (198 results).
- For those willing to take on more risk in search of outsized potential, narrow the field to a focused 130 elite penny stocks with strong financials that still meet basic financial quality checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com