
Should Earnings Decline Require Action From Concentrix (CNXC) Investors?
- Concentrix reported that Executive Vice President of Customer Success, Cormac Twomey, stepped down from his role in December 2025 and then provided limited transition consulting support for 60 days.
- Analysts now expect Concentrix to post a 2.5% year-over-year decline in EPS to $2.71 and slightly lower quarterly revenue, which is putting more attention on cost control, client demand trends, and execution around AI and integration priorities.
- Next, we consider how Concentrix's investment narrative could be affected by the expected earnings softness and revenue pressure.
Concentrix Investment Narrative Recap
For Concentrix, the big picture you need to buy into is a customer experience platform that can turn AI, GenAI assistants, and the Webhelp integration into steadier earnings power over time. In the near term, the key swing factor is execution on cost control and margin repair while revenue growth expectations remain modest and the business is still loss making.
The latest earnings softness and revenue pressure matter mainly because they keep the focus on whether Concentrix can improve profitability fast enough to support its dividend, cover interest on its sizeable debt load, and reduce volatility in results. The Twomey transition itself looks manageable and does not materially change that near term risk reward equation.
The most relevant update alongside this leadership change is the market’s expectation for a 2.5% EPS decline to US$2.71 on slightly lower revenue for the August 2026 quarter. This highlights where the story is tightest. Concentrix is working with slim top line momentum while carrying meaningful debt and an unprofitable bottom line over the last year.
Against that backdrop, the execution bar on AI offerings, iX Hello monetisation, and Webhelp synergies remains high. Any stumble on integrating operations or keeping big clients engaged would weigh on both margins and cash generation at a time when interest costs are already a concern. For you as a shareholder, the central question is how comfortable you are with that balance of execution risk and improvement potential.
Concentrix's narrative projects US$10.2b revenue and US$1.9b earnings by 2029. Analysts are assuming revenue will remain fairly flat over the next 3 years, while this path implies an earnings increase of about US$3.2b from earnings today of a US$1.3b loss.
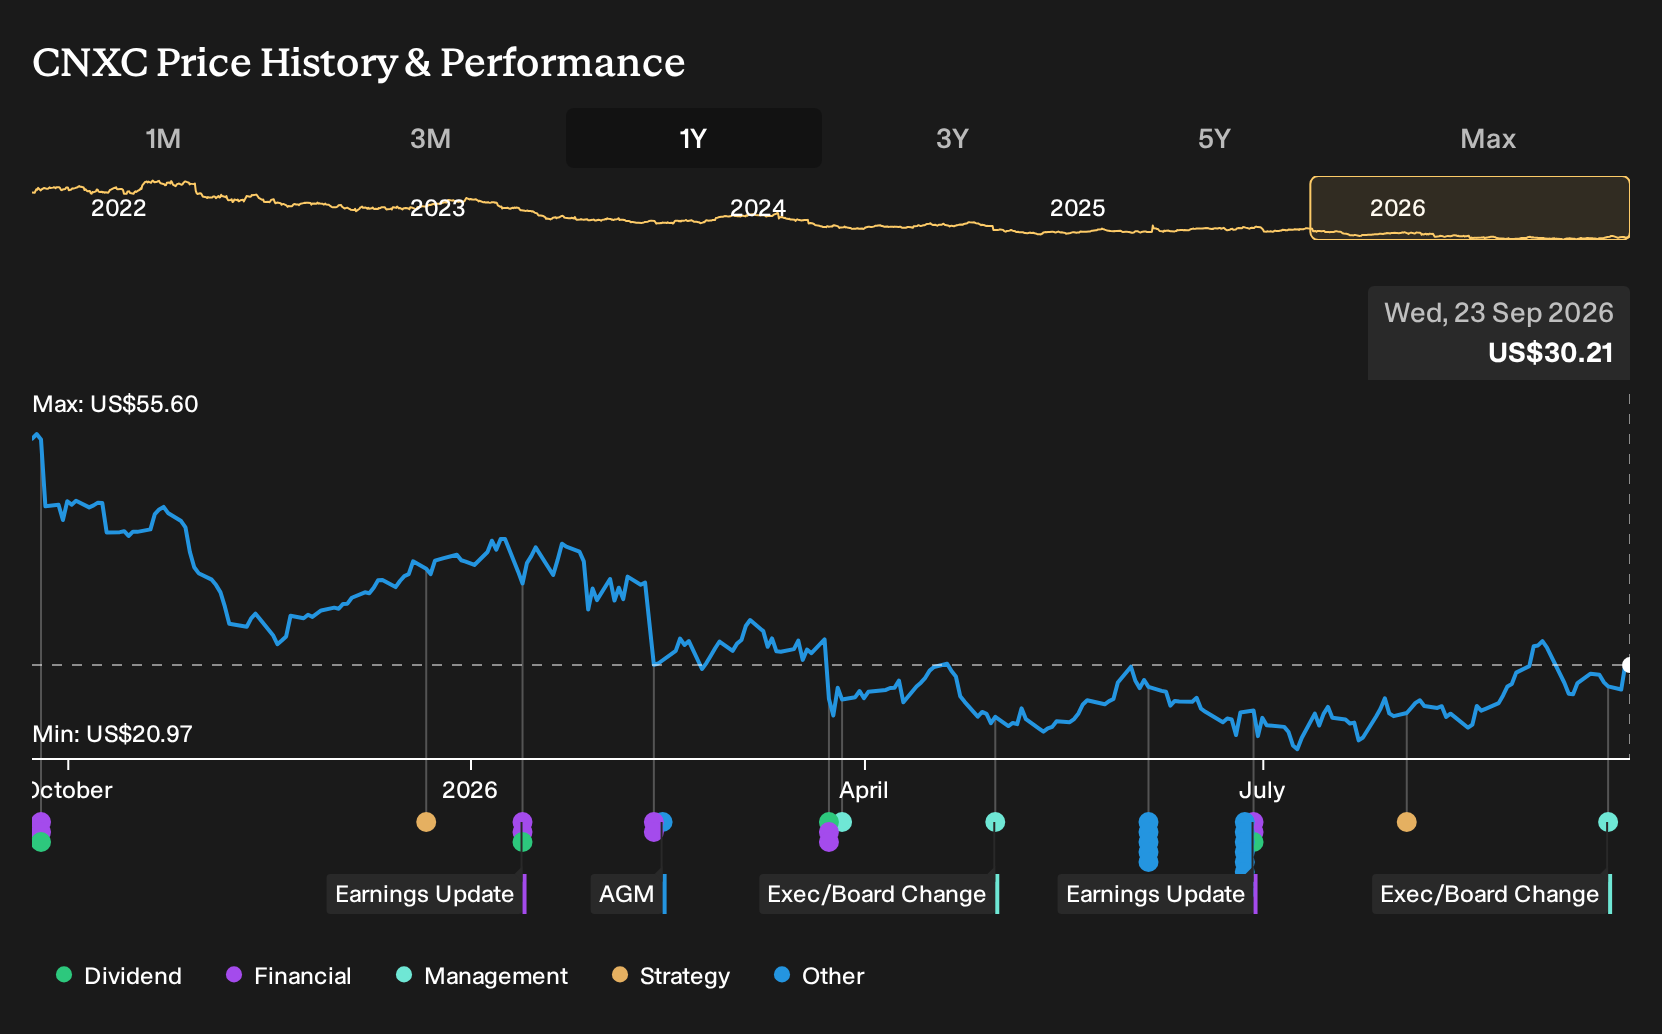
Uncover how Concentrix's fair value indicates a 17% potential upside to its current price, which could narrow quickly if Concentrix executes on its earnings repair plan.
Exploring Other Perspectives
For Concentrix, the bearish angle centers on slower ramp up of high margin AI software. The lowest analysts were already modeling only about US$10.2b of revenue and roughly US$1.5b in earnings by 2029, versus US$1.9b consensus. With the Twomey exit now on the table, those more cautious stories may continue to evolve.
Explore 3 other Concentrix fair value estimates, including one that suggests it could be worth just $30.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Concentrix research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Concentrix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Concentrix's overall financial health at a glance.
Looking for more investment ideas beyond Concentrix?
Once you have a view on Concentrix, it can help to widen the lens and compare it with other companies that share similar qualities, whether that is valuation support, balance sheet strength, or income potential. The Simply Wall St Screener gives you a structured way to do that without getting lost in endless tickers.
- If you want potential value with quality fundamentals, scan a curated list of 16 high quality undiscovered gems that might not yet be widely followed.
- For investors who care most about financial resilience, you can filter for companies with robust finances using a targeted list of solid balance sheet and fundamentals (23 results).
- If reliable income streams matter to you, you can focus on higher yielding payers by reviewing our hand picked 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com