
Quest Diagnostics (DGX) Apple Health Push Leaves Valuation Question Open
Quest Diagnostics (DGX) is back in focus after announcing an Apple Health integration that lets iPhone and iPad users order a US$119 preventive lab panel checking more than 50 biomarkers.
Quest Diagnostics’ Apple Health tie-up lands after a strong run, with the share price up 12.98% over 90 days and 34.07% year to date. A 26.91% 1-year total shareholder return and 100.25% 3-year total shareholder return point to momentum that recent reimbursement headlines have only briefly interrupted.
Capitalize on Quest Diagnostics’ consumer lab momentum by reviewing hand-picked healthcare peers with similar cash flow and balance sheet profiles in the list of solid balance sheet and fundamentals (23 results).After a US$233 share price and a strong multi year run, Quest Diagnostics now sits in a tight spot between reimbursement risk and new consumer demand. Investors may question whether that balance still justifies the current valuation.
Most Popular Narrative: 6% Undervalued
Quest Diagnostics trades at a last close of $233 against a widely followed fair value estimate of $247.40. The narrative leans toward modest upside if the core drivers play out as expected.
The continuing shift toward preventive healthcare and wellness, supported by Quest Diagnostics’ roughly US$300 million consumer business that is growing at about 30% and is expected by management to grow more than 20% annually over the next 3 to 5 years with margins above the corporate average, is setting up a larger recurring revenue base and higher earnings contribution from cash-pay testing.
See why 19 investors see Quest Diagnostics as 6% undervalued.
Result: Fair Value of $247.40 (UNDERVALUED)
Still, the narrative around Quest Diagnostics can break quickly if Medicare reimbursement cuts bite harder than expected or if wage inflation erodes those targeted cost savings.
Find out about the key risks to this Quest Diagnostics narrative.
Another View On Quest Diagnostics’ Valuation
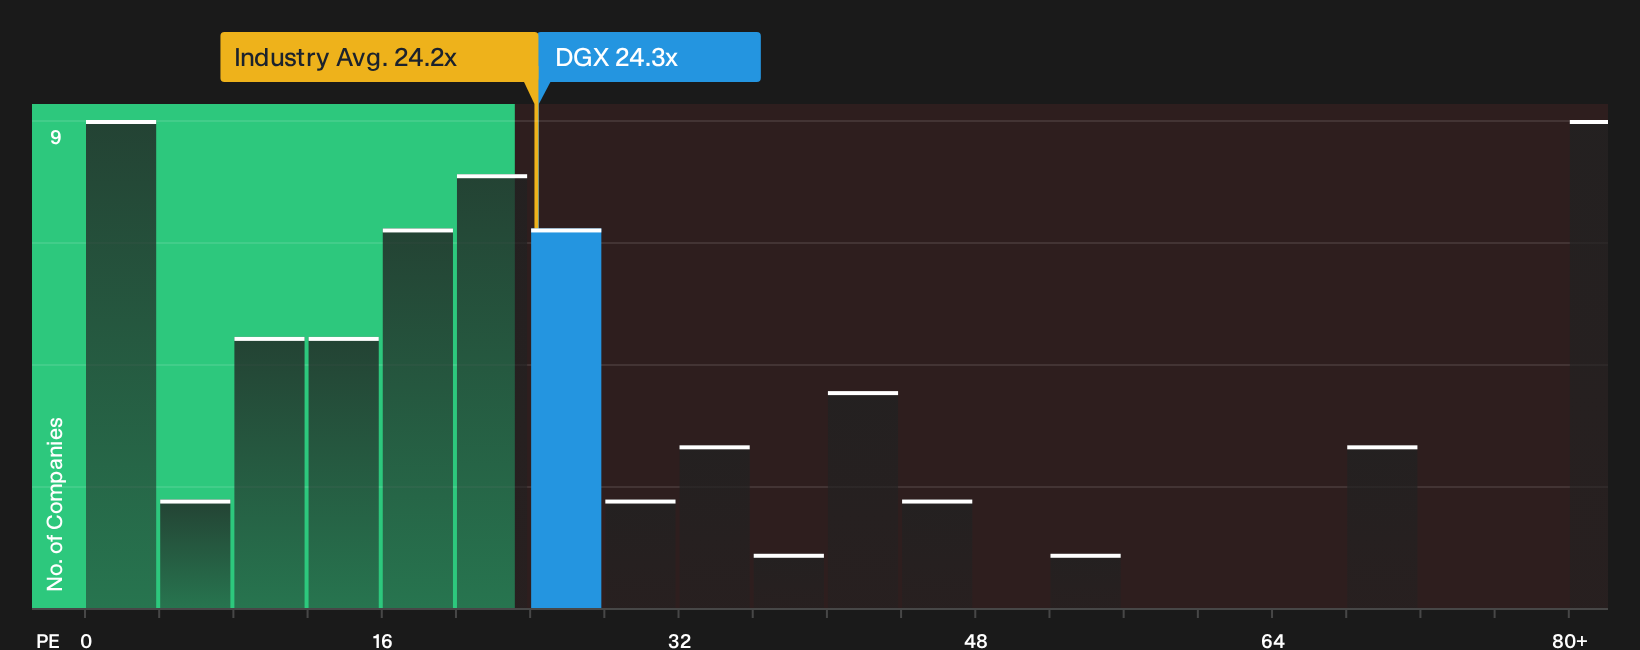
On simple pricing, Quest Diagnostics looks slightly expensive. The shares trade on a P/E of 24.3x, which sits just above both the US Healthcare industry at 24.2x and the peer average at 24.2x, while the fair ratio is 26.8x. Is that gap a cushion, or a signal that expectations already run hot?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Quest Diagnostics and its valuation story make this a moment to move fast, review the key data points and stress test your own thesis. To weigh both the potential upside and the downside risk, start by walking through the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Quest Diagnostics?
Do not stop with Quest Diagnostics. Take a few minutes to scan fresh opportunities with strong fundamentals so you are not relying on a single story.
- Target resilient cash generators by reviewing companies with robust financial strength in the list of solid balance sheet and fundamentals (23 results).
- Hunt for potential value opportunities by scanning financially sound businesses that our models flag as attractively priced in the 30 high quality undervalued stocks.
- Strengthen your income stream by assessing companies screened for higher yields and solid payout support in the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com