
UroGen Pharma (URGN) Stock Looks About Right As Sales Catch Up
UroGen Pharma has seen its stock rally sharply over recent years, which puts fresh focus on whether the current share price lines up with the revenue the business is actually producing. For a biotech still building its commercial footprint, the key issue is how much investors are paying today for each dollar of sales.
- Over the past 3 years, UroGen Pharma has delivered a 191.3% share price gain, which puts a lot of weight on whether the valuation now matches its sales profile.
- The company is working to scale its commercial operations, which can support higher revenue relative to fixed costs and directly shape how much investors are willing to pay for its sales base.
- The analysts covering UroGen Pharma have run their own numbers. See what analysts think UroGen Pharma's shares could be worth.
The issue now is whether UroGen Pharma's current share price is justified by its sales when set against the Fair Ratio benchmark.
If you are weighing UroGen Pharma against other opportunities that tie valuation closely to sales, it can help to compare it with companies in the 30 high quality undervalued stocks
.Does UroGen Pharma Look Fairly Valued on Sales?
P/S is usually a cleaner lens for UroGen Pharma because the business is still loss making, so earnings-based measures like P/E do not tell you much about what the market is paying for its commercial progress.
On this yardstick, UroGen Pharma trades on a P/S of 10.8x. That sits below the Biotechs industry average of 12.9x and above the peer group at 4.7x, which indicates that investors are paying a premium to similar stocks that is not extreme for the sector as a whole.
The Fair Ratio, which blends the company’s own growth profile, margins, risk and size into a tailored benchmark, points to a level that is close to where the shares currently trade. That places the stock roughly in line with what this model would flag for its sales base. Anyone looking at UroGen Pharma now is therefore weighing their conviction on future commercial execution against a valuation that already acknowledges its progress. Explore the numbers behind UroGen Pharma's P/S valuation.
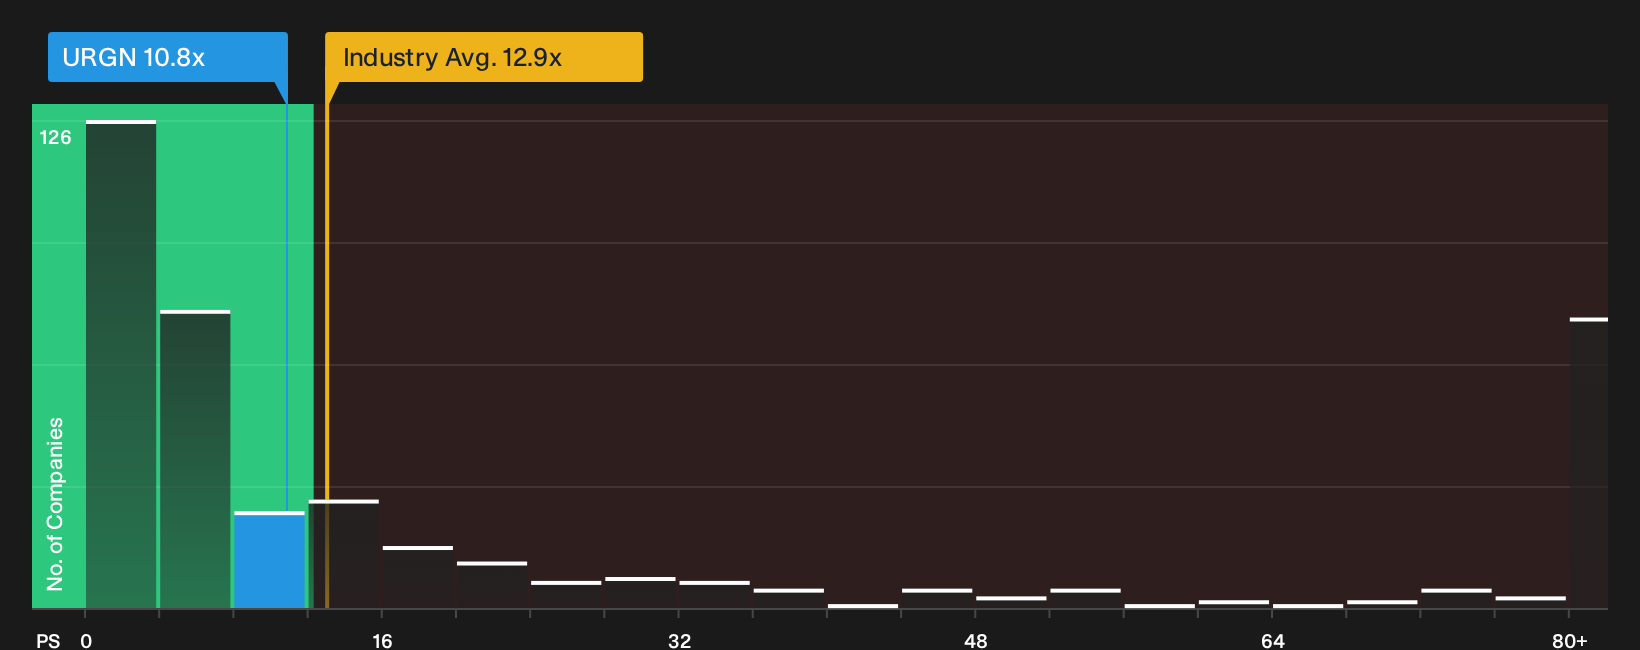
The UroGen Pharma Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where UroGen Pharma's P/S discussion leaves off by explaining which potential paths for future growth, margins and eventual earnings would need to occur for the stock to appear materially stronger or weaker than its current level. Each narrative treats UroGen Pharma's fair value as a hypothesis about the business that can be tracked over time rather than a one-off snapshot. These narratives are available on the stock's Community page for readers to follow.
One of the top community narratives on UroGen Pharma: 13% undervalued
"Heightened regulatory scrutiny, pricing pressures, and potential delays in drug approvals threaten revenue growth and could compress future margins..."
Discover why this Narrative puts UroGen Pharma at 13% undervalued.
The UroGen Pharma share price is only one part of your decision
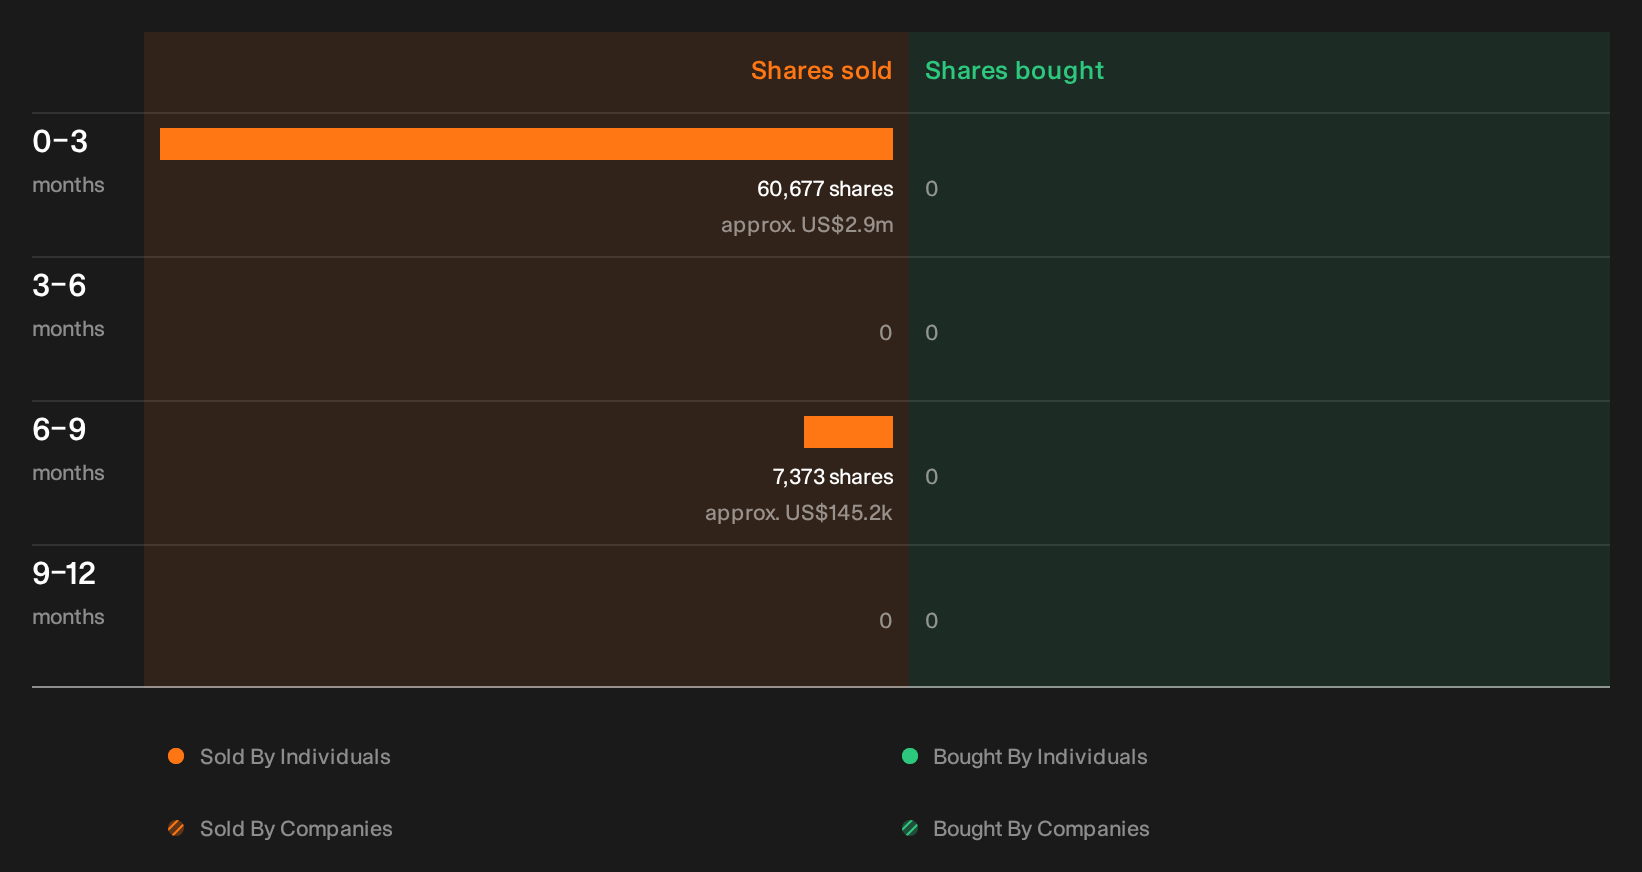
Price and sales tell you what the market thinks today, but recent share disposals by people inside UroGen Pharma can hint at how those closest to the business are acting. See the recent insider selling flagged for UroGen Pharma.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com