
Is Portuguese Rafale Cooperation Altering The Investment Case For Safran Stock?
- Dassault Aviation, on behalf of RAFALE partners including Safran, signed a Memorandum of Understanding with AED Cluster Portugal to explore industrial cooperation tied to the Portuguese Air Force F-16 fleet renewal and the RAFALE bid.
- The MoU links Safran and other RAFALE partners more closely to Portuguese aerospace suppliers, which could reshape future workload distribution, the localisation of high value activities, and the long term defence revenue mix.
- We will now examine how Safran's investment narrative could be influenced by deeper RAFALE industrial cooperation with Portuguese defence suppliers.
Look beyond Safran and this RAFALE-linked MoU by reviewing a curated set of defence and aerospace suppliers in our 229 resilient stocks with low risk scores.
Safran Investment Narrative Recap
To own Safran, you need to believe in resilient demand for civil propulsion and aftermarket services, plus steady growth in European defense, while management handles high CapEx and integration work without eroding returns. The RAFALE MoU in Portugal points to incremental industrial upside, but the near term story still leans on engine output, shop visits, and execution on large programs.
The main short term swing factor remains supply chain reliability around LEAP and other propulsion lines. That is where delivery slippage could affect both revenue and margins. The biggest risk remains the same. Persistent labor or component issues, together with heavier R&D and acquisition integration, could keep profitability below what the current P/E multiple already implies.
The upcoming Safran appearance at Morgan Stanley's 14th Annual Laguna Conference on 15 September 2026 is likely to be the clearest near term information catalyst linked to this RAFALE development. Investors will be watching how management frames defense demand, European programs, and any detail on export campaigns such as Portugal within the broader Equipment and Defense segment.
Conference commentary can also update how supply chain pressures, civil aftermarket momentum, and integration of acquired assets are progressing relative to earlier guidance. Any shift in tone on execution risk, CapEx intensity, or cash generation will matter at a time when the stock trades on a relatively full P/E and is still viewed as slightly below some intrinsic value estimates.
Safran's narrative projects €45.4b revenue and €6.1b earnings by 2029. This implies 10.6% yearly revenue growth and an earnings increase of €2.2b from €3.9b today.
Uncover why Safran's fair value indicates a 14% potential upside to its current price that could narrow quickly.
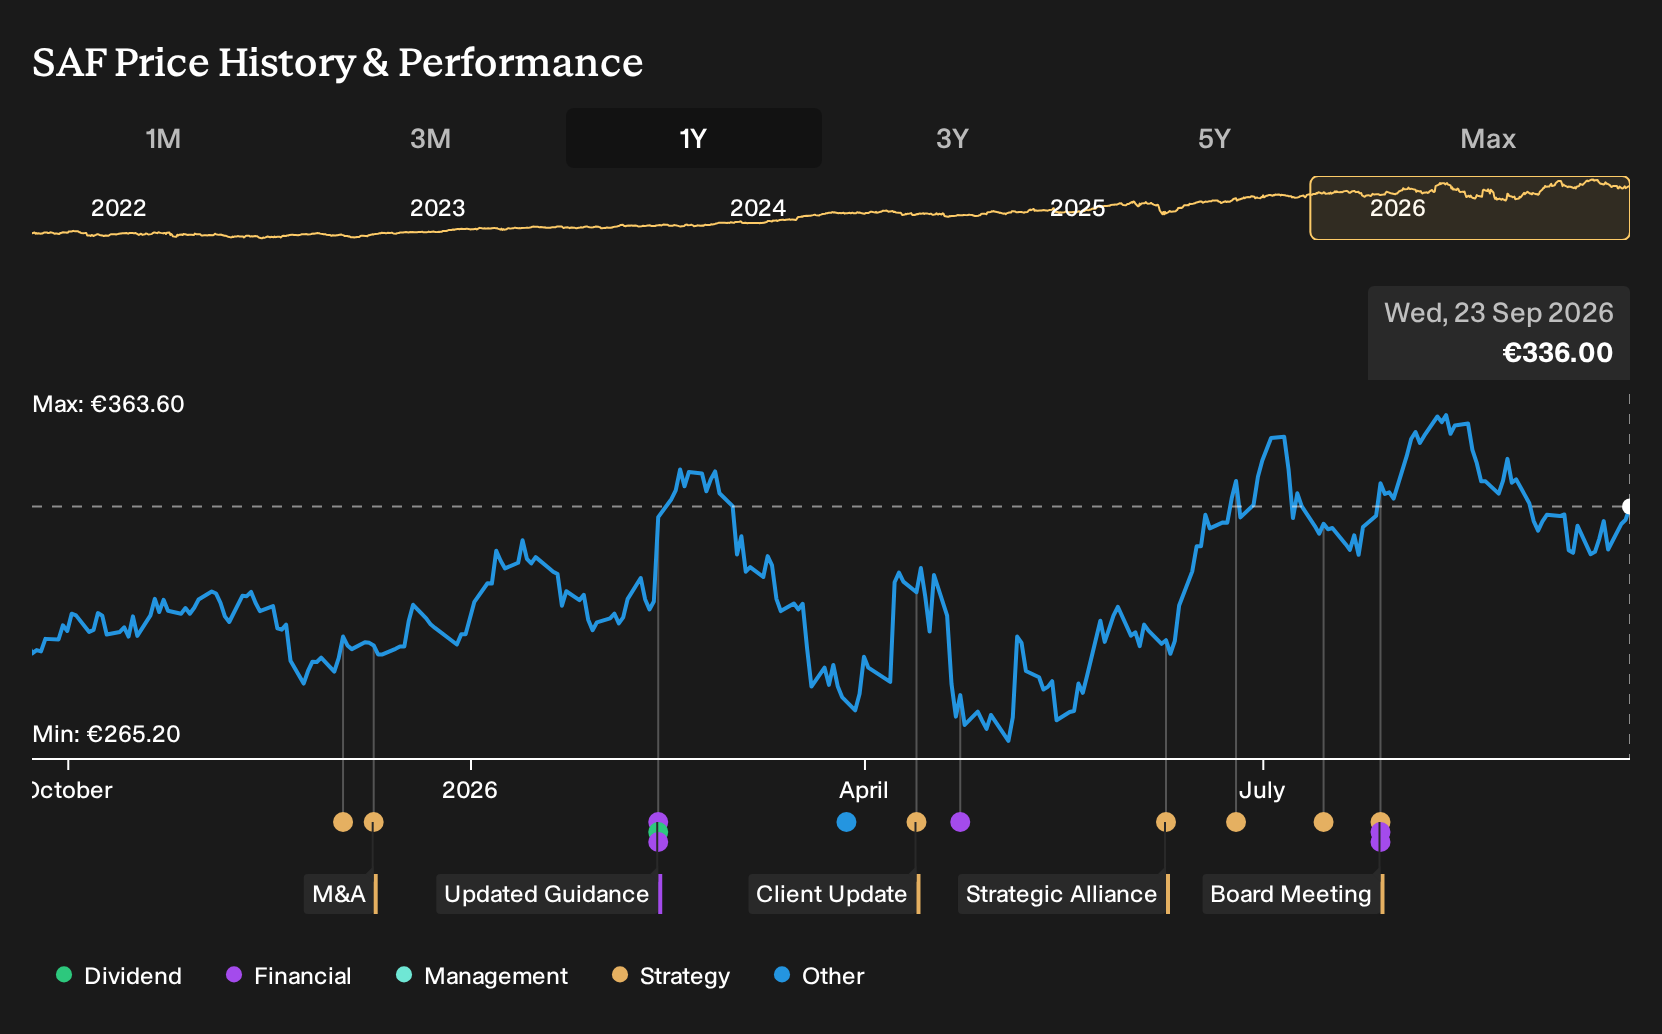
Exploring Other Perspectives
Some of the most optimistic analysts focus on Safran’s defense capacity build out rather than just civil engines. Before this MoU, the bullish camp was already modeling roughly €47.9b of 2029 revenue and €7.2b of earnings. You now have a fresh defense data point that could nudge those narratives, so explore a range of views.
Explore 4 other Safran fair value estimates, including one that suggests up to a 14% increase from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Safran research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Safran. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Safran's overall financial health at a glance.
Looking For More Investment Ideas Beyond Safran?
If Safran is just one piece of your watchlist, it can help to scan for other businesses that match your risk, income, and value preferences using the Simply Wall St Screener.
- For investors who want strong balance sheets and fundamentals to underpin their thesis, start with a list of solid balance sheet and fundamentals (198 results) that can handle shocks without stretching their finances.
- If the goal is to hunt for underappreciated opportunities, focus on 172 high quality undervalued stocks that combine quality metrics with pricing that still looks reasonable on key ratios.
- Those who care most about income potential can anchor their watchlist around 161 dividend fortresses that target yields above 5% while aiming to keep payouts supported by underlying cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com