
Air Products And Chemicals (APD) Could Be 17% Undervalued As Chip Supply Deal Lifts Outlook
Air Products and Chemicals (APD) just signed a long-term deal to supply high-purity gases and infrastructure to a leading US semiconductor manufacturer, committing about US$250 million to new facilities in Arizona.
Recent trading tells a mixed story. Air Products and Chemicals’ share price has pulled back over the past month with a 30‑day share price return of down 6.29%, yet the year‑to‑date share price return of 14.57% and 1‑year total shareholder return of 8.20% point to momentum that has cooled rather than reversed, as investors digest the semiconductor deals and shifting expectations around the company’s earnings power.
Scan how Air Products and Chemicals fits into the broader picks powering factories and fabs by reviewing the hand-curated 85 AI infrastructure stocks shaping the backbone of advanced manufacturing and semiconductor growth.
Bulls see Air Products and Chemicals turning semiconductor wins and raised analyst earnings estimates into a stronger long run story. Bears point to recent share price softness and a reported net loss. Which case does the current valuation lean toward?
Most Popular Narrative: 17% Undervalued
Against the last close of $286.97, the most followed narrative puts Air Products and Chemicals’ fair value at about $345, which points to a meaningful valuation gap that hinges on how well management turns its industrial gas and clean energy pipeline into earnings and cash flow under a 7.7% discount rate.
Capital discipline and portfolio optimization, including the decision not to proceed with the Louisiana Clean Energy Complex and several other clean energy projects and the related plan to lower annual capex toward about US$2.0b to US$2.5b with roughly US$1.5b focused on traditional industrial gas projects, may free cash for higher return uses and support future return on capital and free cash flow.
See why 75 investors see Air Products and Chemicals as 17% undervalued.
Result: Fair Value of $345.11 (UNDERVALUED)
Still, the story around Air Products and Chemicals can break if hydrogen and ammonia projects run into cost overruns or if helium pricing and supply remain under pressure.
Find out about the key risks to this Air Products and Chemicals narrative.
Another View: What Multiples Say About Air Products and Chemicals
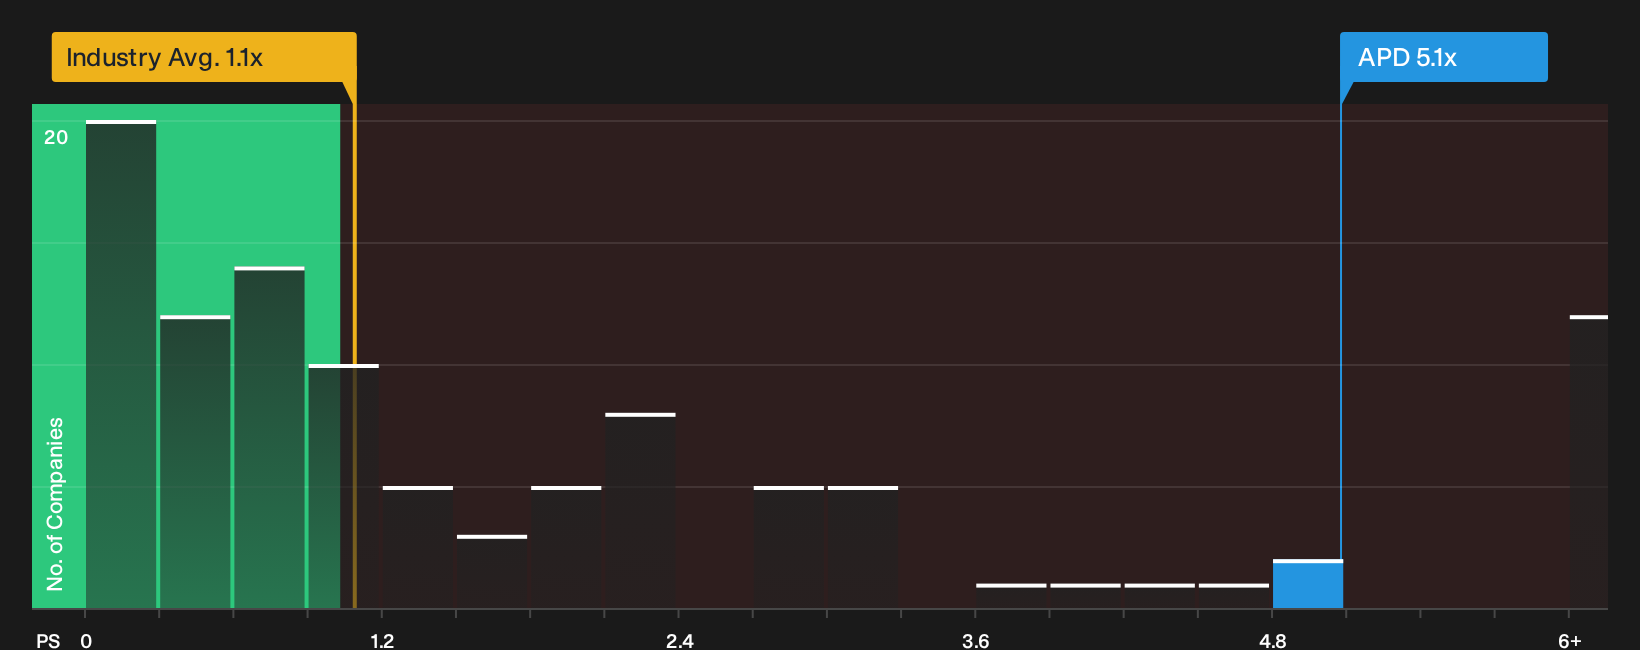
While the SWS DCF model points to Air Products and Chemicals trading below an estimated future cash flow value of $358.06, the simpler sales based yardstick tells a different story. The stock changes hands at a P/S ratio of 5.1x, compared with a US Chemicals industry average of 1.1x and a fair ratio of 2.4x that the market could eventually lean toward. That kind of gap suggests investors are paying a premium for each dollar of revenue, so how comfortable are you with that pricing if expectations around future earnings or projects shift?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Air Products and Chemicals can leave the picture feeling unfinished, so move quickly, test the numbers yourself, and pressure test both sides of the argument using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Air Products and Chemicals?
If Air Products and Chemicals has your attention, do not stop here. Put other opportunities on your radar and give yourself more options before the market moves.
- Spot potential bargains early by checking the 30 high quality undervalued stocks that pair solid fundamentals with appealing pricing.
- Prioritize resilience and sleep easier at night by scanning the 31 resilient stocks with low risk scores built around stronger balance sheets and lower risk profiles.
- Hunt for future standouts by reviewing the 16 high quality undiscovered gems that most investors are not watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com