
Barrick Mining (TSX:ABX) Dropped, So What Is Driving Attention Now?
Barrick Mining (TSX:ABX) has moved to deepen its use of artificial intelligence by selecting Avathon’s Physical AI and Autonomy Platform to connect data and decision-making across its North American mining operations.
Recent trading has been choppy for Barrick Mining, with the share price at CA$59.85 after a 1-day move that declined 3.17%, a 30-day share price return that fell 10.18%, and a 90-day gain of 14.90% that points to building momentum following a softer year to date. At the same time, the 1-year total shareholder return of 30.84% and very large 3-year and 5-year total shareholder returns suggest long term holders have seen strong value creation, even as fresh AI initiatives and mixed quarterly headlines keep shorter term sentiment moving around.
Scan beyond Barrick Mining and see how other producers are using automation and data to reshape their operations with our curated list of 36 elite gold producer stocks
Bulls see Barrick Mining’s AI push and long term returns as evidence that the recent pullback is a chance to add exposure. Skeptics point to volatility and project risk. Which story does the valuation actually support?
Most Popular Narrative: 9% Undervalued
Compared with the last close at CA$59.85, the most followed narrative anchors Barrick Mining’s fair value at CA$65.74. This frames today’s price as leaving a valuation gap that only closes if key projects and capital returns play out as outlined.
Barrick's robust balance sheet and disciplined capital return strategy enable continued shareholder-friendly actions (dividends, buybacks) without diluting equity. Future catalysts, such as successful financing for Reko Diq and new exploration results, could further unlock value, improving investor return profiles and narrowing the gap between asset and market value.
See why 115 investors see Barrick Mining as 9% undervalued.
Result: Fair Value of CA$65.74 (UNDERVALUED)
Still, if political issues at key African sites flare up or ESG and permitting costs rise faster than expected, the Barrick Mining upside story could fracture.
Find out about the key risks to this Barrick Mining narrative.
Another View: Barrick Mining Through The Cash Flow Lens
While the prevailing story casts Barrick Mining as 9% undervalued at a fair value of CA$65.74, our DCF model paints a cooler picture. On that framework, the estimated future cash flow value is CA$49.41, below the current CA$59.85 price. Which signal do you trust more when cash flows and sentiment disagree?
Our DCF output is only as strong as the assumptions that feed it, so it is worth seeing exactly how the moving parts fit together in the SWS DCF model. Look into how the SWS DCF model arrives at its fair value.
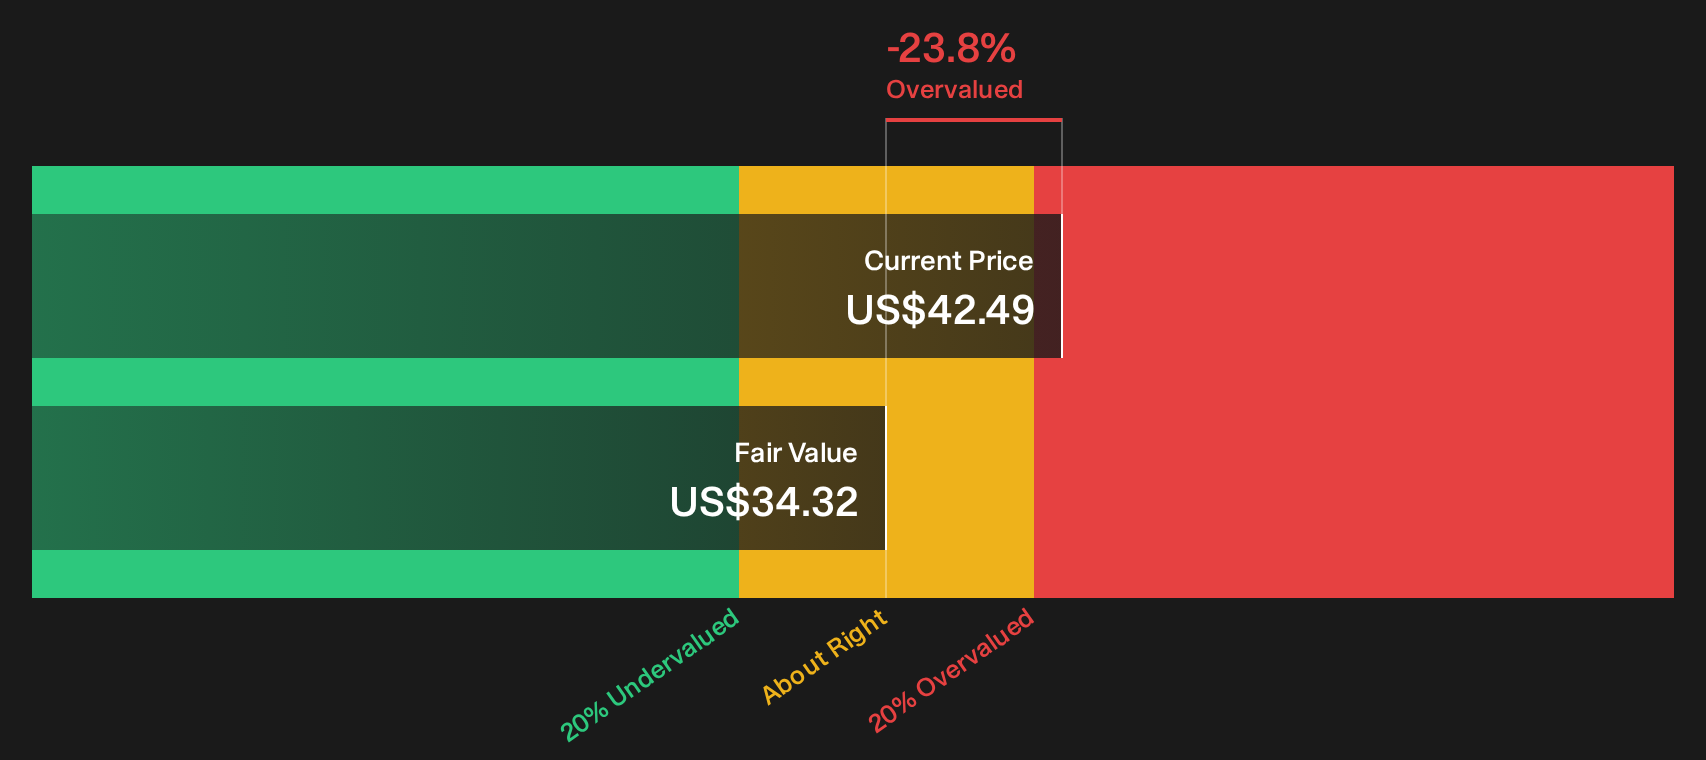
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barrick Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Barrick Mining only matter if you let them. Act while views are still split and weigh both sides using the 4 key rewards and 2 important warning signs.
Looking for more ideas beyond Barrick Mining?
If you only stop at Barrick Mining, you might miss cheaper quality, steadier income streams, or underfollowed potential that fits your goals even better.
- Target dependable cash generators and stress test your watchlist against a list of solid balance sheet and fundamentals (7 results).
- Hunt for mispriced opportunities by scanning a focused 6 high quality undervalued stocks tailored to solid fundamentals.
- Lock in income leads by comparing yield-heavy candidates across a curated 1 dividend fortresses built for payout reliability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com