
Does Priority Review Change The Bull Case For Intellia Therapeutics Stock (NTLA)?
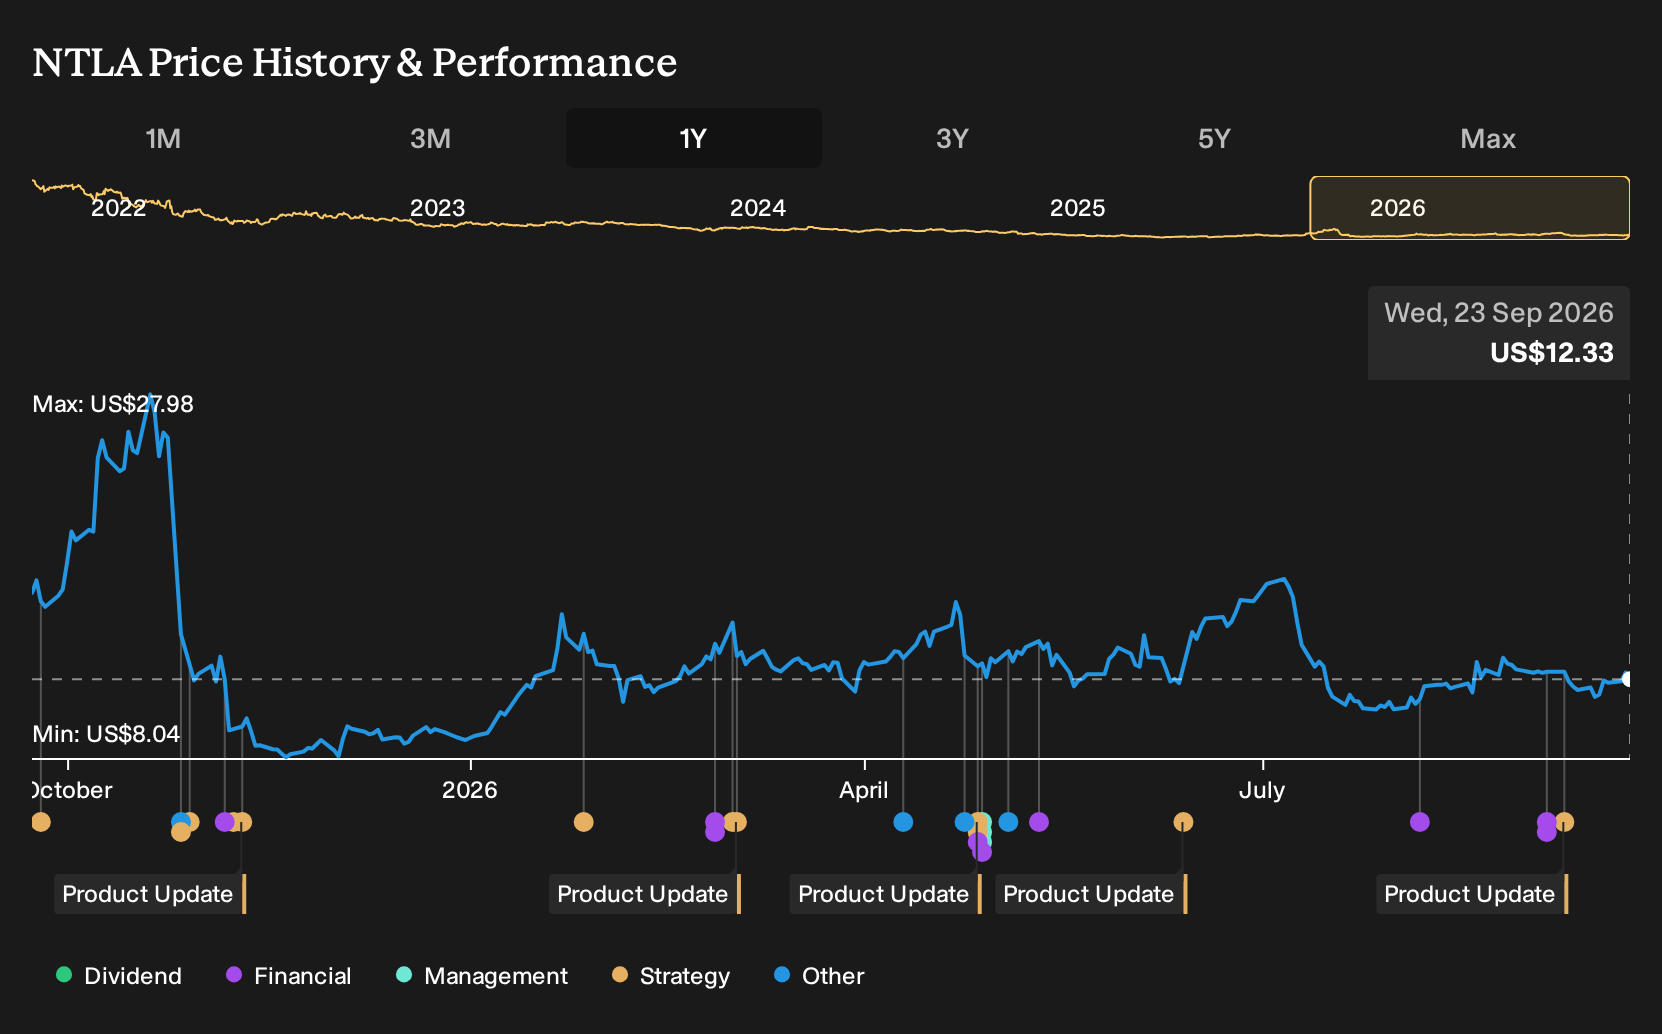
- Intellia Therapeutics reported that the FDA previously accepted its Biologics License Application for lonvo-z in hereditary angioedema and granted the gene editing therapy Priority Review, with no advisory committee planned. This reflects the regulator's comfort with the submitted Phase 3 package and existing global designations.
- This regulatory progress moves Intellia Therapeutics closer to potential commercialization of an in vivo CRISPR treatment. This development could reshape its revenue mix, operating cost profile, and reliance on partnerships once pricing, reimbursement, and real world use patterns become clear.
- We will now examine how Intellia Therapeutics' investment narrative could shift given lonvo-z's Priority Review status and advancing regulatory profile.
Scan beyond Intellia Therapeutics and this gene editing milestone by reviewing hand picked 38 healthcare AI stocks that are already tackling major medical problems with advanced data and biology platforms.
Intellia Therapeutics Investment Narrative Recap
To own Intellia Therapeutics, you need to believe its in vivo CRISPR platform can convert today’s heavy R&D and losses into a viable product portfolio. The lonvo z Priority Review sharpens that bet. It concentrates attention on a single near term regulatory outcome while the rest of the pipeline and partnerships remain earlier stage and less visible to you.
The biggest near term swing factor is whether Intellia can reach commercial scale before funding pressure and past dilution become a bigger drag. The firm still reports a loss of roughly US$400 million and is not forecast to turn profitable soon. If payer pushback or competition slows lonvo z uptake, the cash burn and execution risk remain central concerns.
Among recent developments, the company’s guidance that its cash runway extends into the first half of 2027 appears most relevant alongside the lonvo z update. Priority Review shortens the regulatory clock, which makes the existing funding window more important for building a basic commercial setup without repeatedly returning to equity markets.
For you, that pairing of runway and regulatory momentum frames the near term catalyst. Lonvo z progress could start to rebalance Intellia Therapeutics away from pure R&D spend toward initial product revenue, while the extended runway gives management time to execute. If timelines slip or launch economics disappoint, the same fixed cost base and limited diversification amplify the downside risk.
Intellia Therapeutics' current analyst story points to US$644.6 million in revenue and US$117.5 million in earnings by 2029, based on expectations for revenue to grow 121.3% per year. That trajectory implies a swing in earnings of about US$517.5 million, from a loss of US$400.0 million today to the 2029 consensus figure.
Discover why Intellia Therapeutics' fair value points to a 94% potential upside to its current price, which may narrow quickly.
Exploring Other Perspectives
One alternate view on Intellia Therapeutics leans hard into the risk that lonvo-z, as a onetime treatment, could leave revenue flat once early demand is met. The most bearish analysts were working off only US$18.6 million of 2029 revenue and US$3.3 million of earnings, a sharp contrast to consensus, and those forecasts came before this Priority Review news. That gap shows how widely opinion can differ. Use it as a cue to compare several narratives before deciding what this update might change in your own view.
Explore 2 other Intellia Therapeutics fair value estimates, including one that suggests it could be worth just $23.94!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Intellia Therapeutics research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Intellia Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intellia Therapeutics' overall financial health at a glance.
Looking for more investment ideas beyond Intellia Therapeutics?
Once you have a view on Intellia Therapeutics, it can help to widen the lens and compare it with other opportunities that fit your risk tolerance, time horizon, and income needs. The Simply Wall St Screener is built for exactly that kind of side by side work, so you can stress test your thesis instead of looking at this stock in isolation.
- If you are hunting for mispriced quality, scan a curated set of 30 high quality undervalued stocks that combine solid fundamentals with support from our valuation checks.
- If resilience matters more than headlines, filter for a 31 resilient stocks with low risk scores and see which businesses line up with your comfort level on balance sheet strength and earnings volatility.
- If you prefer durable financial footing as your starting point, focus on a list of solid balance sheet and fundamentals (23 results) that already pairs stronger finances with straightforward business models.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com