
Has Natera (NTRA) Run Ahead Of Fair Value After Its Japan Signatera Approval?
Natera (NTRA) is back on investors’ radar after Japan’s drug regulator cleared its Signatera test as a companion diagnostic in muscle-invasive bladder cancer, opening a fresh commercial path in that market.
Natera’s latest approval in Japan comes on top of a strong tape, with the share price now at $390.79 and a 30 day share price return of 19.25% feeding into a 70.77% year to date share price gain. Recent product data in lung cancer, conference appearances in mid September and two PMDA green lights within three months have coincided with what is now a 138.42% 1 year total shareholder return and a 3 year total shareholder return above 7x, signalling powerful momentum rather than a one day reaction to the MIBC news.
Spot 38 healthcare AI stocks that, like Natera, are pursuing data-driven breakthroughs in cancer detection and treatment.Natera now trades above the average analyst target while still screening at a discount to some intrinsic value estimates. Is that a sign of undue caution, or a market that remembers the risks of a fast run up?
Most Popular Narrative: 13% Overvalued
Natera’s most followed valuation story pegs fair value at $344.33, below the last close at $390.79, which frames today’s rally as richer than its modeled cash flow and earnings path.
Expanding clinical validation through large-scale trials (DARE, IMvigor011, PROCEED/FIND, etc.) and broadening indications is expected to lead to further payer adoption and reimbursement, especially for new tumor types and expanded Medicare coverage; this should drive higher ASPs and gross margins.
Investment in new product launches (e.g., Fetal Focus NIPT, Signatera Genome, AI-based biomarkers) and a robust R&D pipeline positions Natera to capture growth from long-term trends in personalized medicine and early detection, underpinning future revenue expansion.
See why 17 investors see Natera as 13% overvalued.
Result: Fair Value of $344.33 (OVERVALUED)
Still, Natera’s story can break if reimbursement tightens or if competitors win share in oncology and prenatal testing more quickly than expected.
Find out about the key risks to this Natera narrative.
Another View on Natera’s Valuation
The first story says Natera looks 13% overvalued relative to a $344.33 fair value. Our DCF model tells a very different story. On that framework, the shares sit about 34% below an estimated cash flow value of $591.70, which tilts the risk reward picture in the opposite direction.
The gap between analyst targets and the SWS DCF model raises a practical question. Which set of assumptions about margins, capital needs, and terminal value do you trust more when you decide how much volatility to accept for potential upside, and how much safety margin you really have on Natera here?
Look into how the SWS DCF model arrives at its fair value.
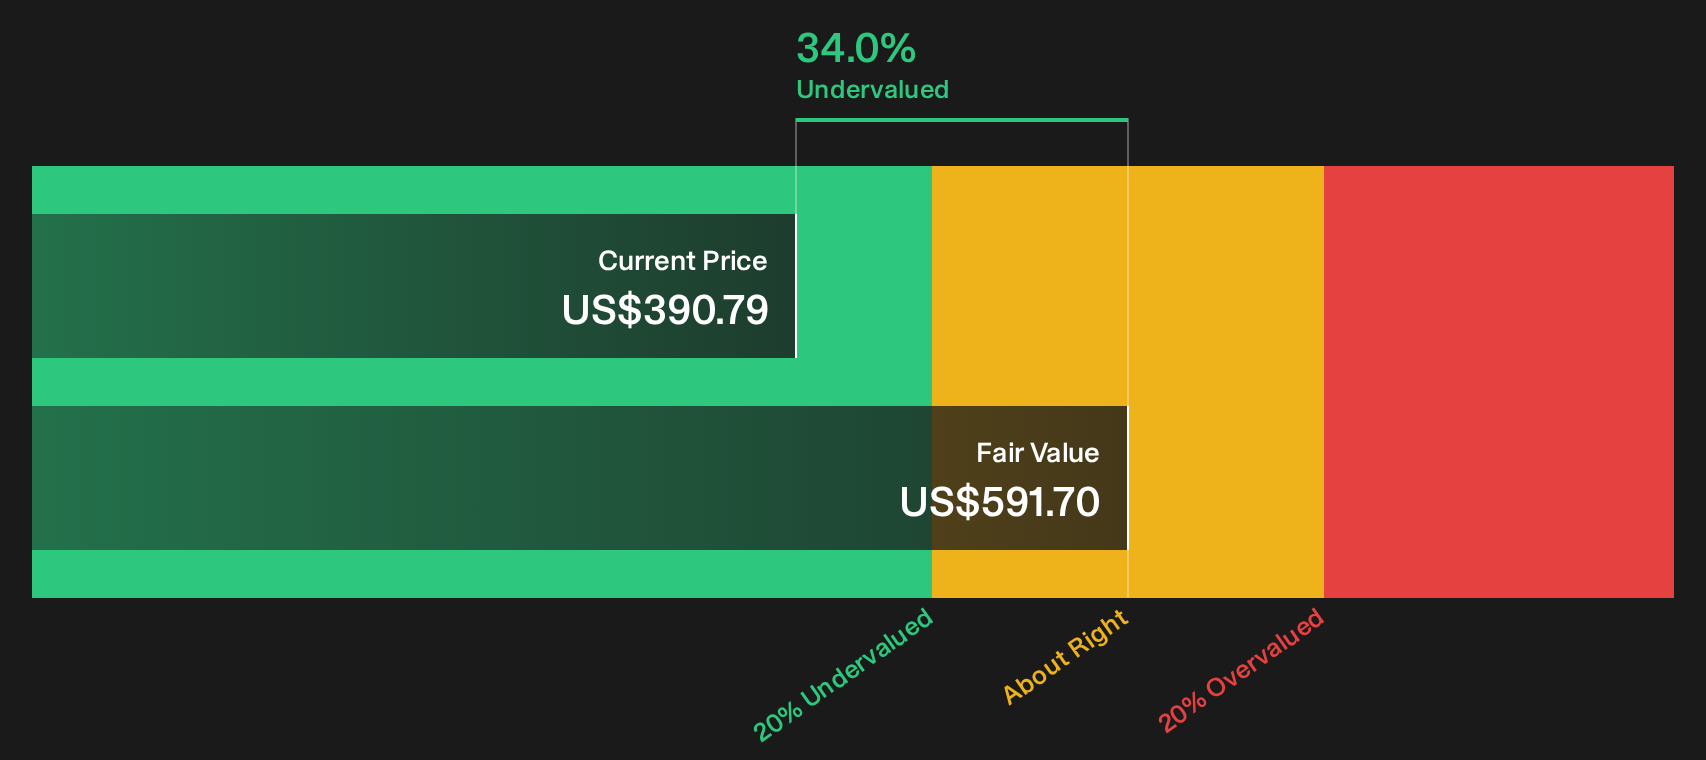
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Natera for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of optimism and caution around Natera feels familiar, treat it as a prompt to pull the numbers yourself and stress test the thesis against your own risk tolerance, starting with the 3 key rewards.
Looking for more investment ideas beyond Natera?
Do not stop with Natera. Use this momentum to refresh your watchlist with other clear stories where the numbers and business quality both matter.
- Target reliable compounding by scanning for companies with resilient balance sheets and steady fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Hunt for quality at a discount by reviewing the 16 high quality undiscovered gems that the market has not fully priced in yet.
- Lock in potential income streams by focusing on resilient payers using the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com