
Generac Holdings (GNRC) Could Be 32% Undervalued As Data Center Demand Drives Its Story
Generac Holdings (GNRC) has moved sharply in recent sessions, with the stock down about 3% at the latest close, yet still higher over the past week and year.
For context, Generac Holdings now trades at US$199.42, with the share price down 3.27% on the day but still showing a 13.88% 7 day share price return and a 41.33% year to date share price return. The 1 year total shareholder return sits at 19.16% and the 3 year total shareholder return at 83.14%, pointing to longer term momentum that contrasts with a recent 90 day share price decline of 32.44% and a 5 year total shareholder return that is down 50.95%.
Scan beyond Generac Holdings and compare this price swing with other power and infrastructure plays on our curated list of 39 power grid technology and infrastructure stocks.
Bulls point to Generac Holdings’ rising annual revenue and net income, while bears highlight sharp recent share price swings and a weak 5 year return. Which side does the current valuation evidence support next?
Most Popular Narrative: 32% Undervalued
Generac Holdings last closed at $199.42, compared with a widely followed fair value narrative of $292.38 that is built on detailed growth and margin assumptions using a 9.82% discount rate.
Accelerating demand for backup power solutions in data centers driven by AI adoption and global digitalization has resulted in a structural supply deficit for large commercial generators. Generac's rapid entry and >$150 million backlog position it to capture significant revenue growth and operating leverage over the next several years, with further potential upside as the company expands capacity to address 2027+ demand.
See why 25 investors see Generac Holdings as 32% undervalued.
According to this narrative, that $292.38 fair value hinges on several moving parts. Revenue is assumed to rise at about 19.9% a year, net profit margin is expected to move from 5.8% to 11.6%, and earnings are projected to reach $888.5 million by around 2029. Those forecasts are then discounted back to today using the 9.82% rate to arrive at a present value that sits well above the current share price.
The story is not one sided. Analysts see upside from Generac Holdings data center backlog, expanding capacity to serve hyperscalers, and ongoing demand for backup power and home energy management. On the other hand, they flag pressure from a weaker residential solar market, reliance on outage driven generator demand, and execution risk around large capital commitments and diesel exposure at a time when regulations and customer preferences may keep shifting.
That tension shows up in the range of views. Targets around the $292.38 mark rest on confidence in higher earnings power. More cautious perspectives focus on concentration in a few large contracts, the need for non hyperscaler orders to support planned capacity, and the drag from clean energy segments that are still working toward stronger profitability.
Result: Fair Value of $292.38 (UNDERVALUED)
Still, two pressure points could unsettle that 32% undervalued story for Generac Holdings: prolonged residential solar weakness and any stumble executing the capital heavy data center build out.
Find out about the key risks to this Generac Holdings narrative.
Another View: What Multiples Say About Generac Holdings
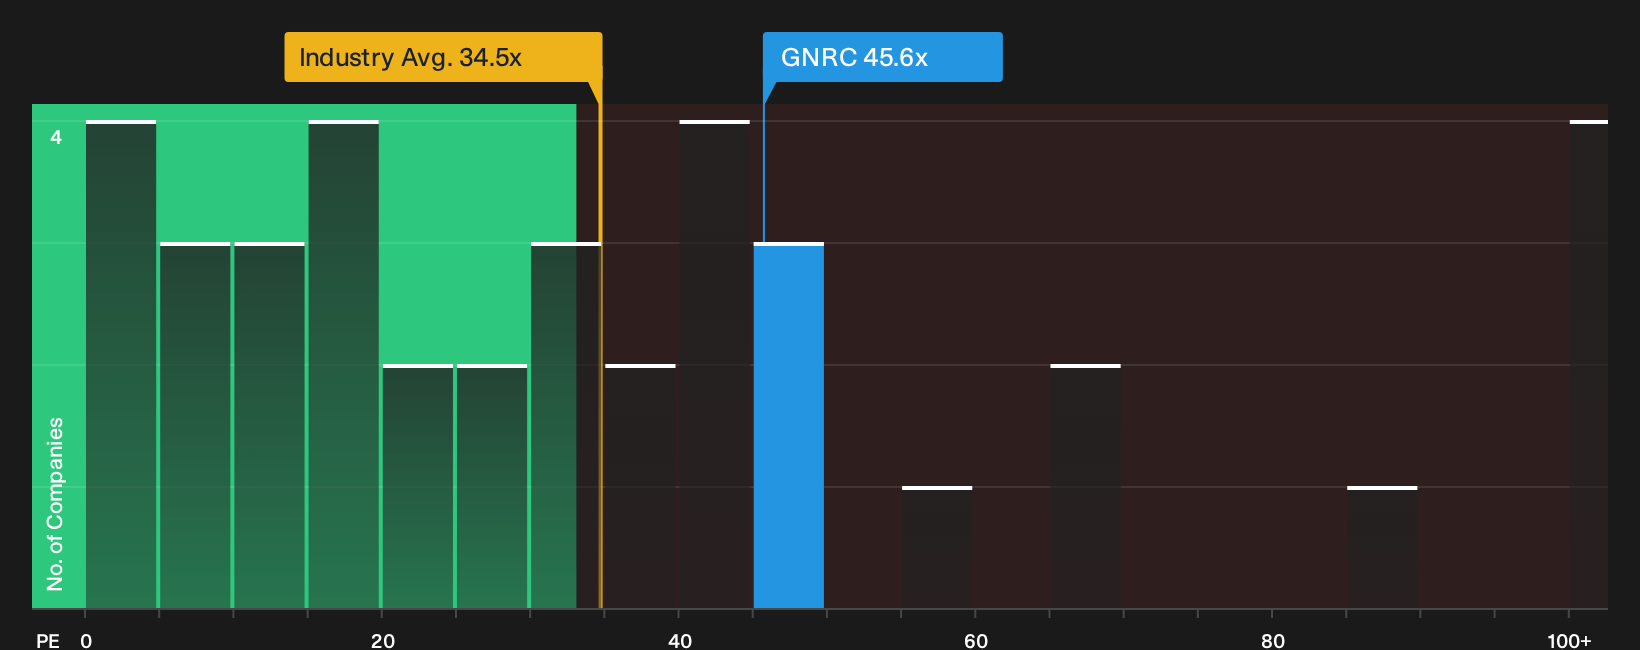
A different lens on Generac Holdings comes from its P/E ratio. The stock trades on 45.6x earnings, which is richer than the US Electrical sector at 34.5x, the peer average at 40.3x, and the 40.1x fair ratio that the market could move toward over time.
This gap suggests investors are already paying a premium for the growth story. The key question is whether future execution and earnings delivery will be strong enough to keep that premium intact.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strong views are forming around Generac Holdings after the recent moves and valuation debate. Check the numbers yourself, weigh the risks, and see why some investors highlight 3 key rewards
Looking for more ideas beyond Generac Holdings?
If Generac Holdings has you thinking more broadly about where to put fresh capital to work, do not stop with just one opportunity. Use the Simply Wall Street Screener to quickly surface new prospects that match your style, so you are not leaving potential ideas on the table.
- Target quality at a discount by scanning for companies that pass strict fundamentals checks and trade below intrinsic estimates with the 30 high quality undervalued stocks.
- Prioritise resilience by hunting for businesses with strong balance sheets and healthy financial footing through the list of solid balance sheet and fundamentals (23 results).
- Spot tomorrow's potential standouts early by tracking under the radar stocks with robust metrics using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com