
How Investors May Respond To Citi (C) Card Data Ad Platform
- Citigroup launched Citi Commerce Media, a new platform in its U.S. Consumer Cards business that uses first party transaction data across 6.5 billion annual card purchases to help brands target customers and measure advertising outcomes.
- The planned acquisition of rewards platform Kard suggests Citigroup is pushing deeper into data driven advertising and loyalty, tying card spending, media exposure and closed loop measurement into a single commercial engine.
- We will look at how this push into transaction driven media through Citi Commerce Media could influence Citigroup's broader investment narrative.
Scan other banks that are building data-rich ecosystems around payments and media by zeroing in on 16 high quality undiscovered gems that could be earlier in the same playbook as Citigroup.
Citigroup Investment Narrative Recap
For an investor to own Citigroup, the belief has to be that a global, transaction driven platform can steadily compound earnings as the bank simplifies, cuts stranded costs and leans into fee heavy services. The short term swing factor is execution on digital and data products like Citi Commerce Media, which aim to convert Citi's 70 million US card customers into a higher margin ecosystem.
The biggest risk remains that high transformation and compliance costs, plus pressure from fintech competitors, keep returns on equity stuck at low double digits. The recent burst of funding activity and the planned 2027 note redemption largely sits in the background here, since it mainly tunes the balance sheet rather than resets the operating story.
The most relevant new development alongside Citi Commerce Media is Citigroup's move to redeem €1.5b of 0.500% fixed or floating notes due 2027 in October 2026, while issuing a wide spectrum of new callable senior debt across maturities out to 2056. You are watching an active refinancing machine at work.
For holders of the stock, this matters less as a headline and more as context for the catalyst and risk mix. A cleaner funding stack can support the case that digital platforms, transaction services and wealth management can flow through to steadier earnings. Any misstep, whether on execution of Commerce Media or on regulatory demands, would still sit on top of a very leveraged capital structure.
Citigroup's narrative projects US$106.2b revenue and US$21.9b earnings by 2029. That profile implies 9.1% yearly revenue growth and a US$5.4b earnings increase from US$16.5b today.
Uncover how Citigroup's fair value indicates a 17% potential upside to its current price. This upside could narrow quickly if sentiment shifts in Citigroup's favor.
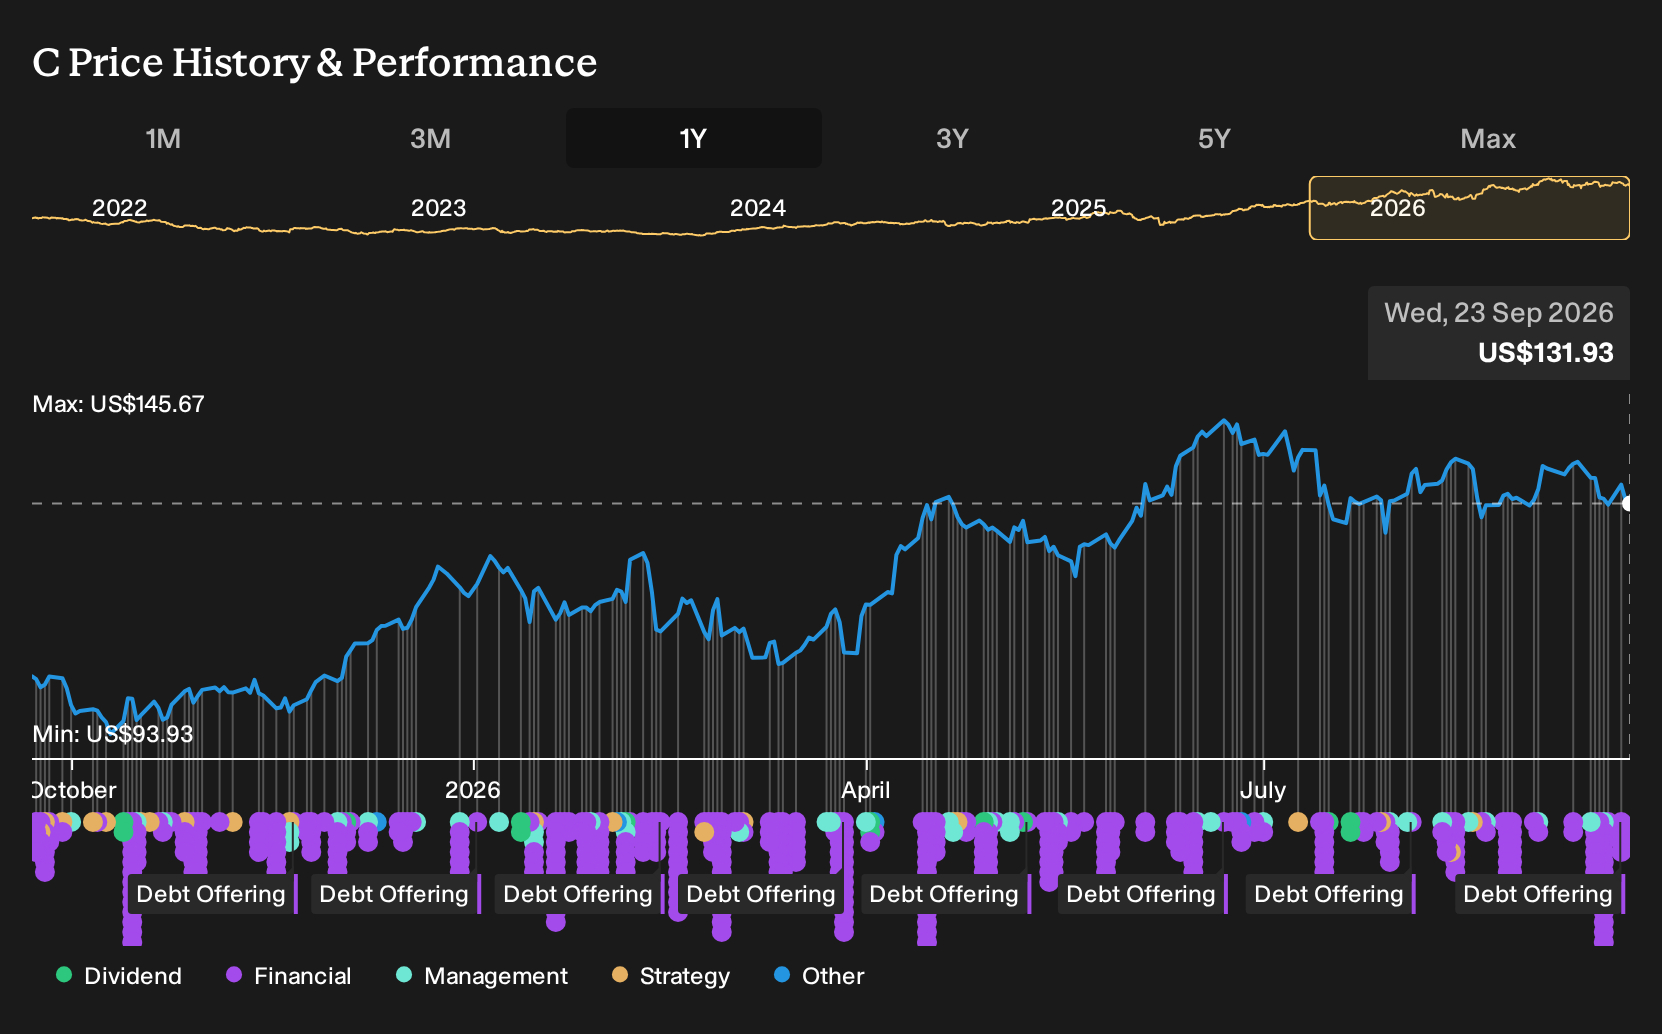
Exploring Other Perspectives
One alternate view puts the spotlight on costs rather than Citi Commerce Media’s upside. The most bearish analysts already assumed revenue of about US$104.6b and earnings near US$21.1b by 2029, with a 10.8x P/E. That is a cooler story than consensus, and the new media and refinancing moves could push opinions in either direction.
Explore 4 other Citigroup fair value estimates, including one that suggests it could be worth just $154.00.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Citigroup research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Citigroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Citigroup's overall financial health at a glance.
Looking for more investment ideas beyond Citigroup?
Once you have a handle on Citigroup, it often helps to compare it with a few other businesses that match your preferred style, whether that is value, income, or resilience.
- If you want potential mispriced opportunities with strong fundamentals, start by scanning our 30 high quality undervalued stocks that already clear strict quality and balance sheet checks.
- For investors who care most about steady cash returns, focus on income candidates through our 7 dividend fortresses that target companies with higher yields.
- If capital preservation ranks highest for you, narrow your watchlist using a 31 resilient stocks with low risk scores that screens for businesses with sturdier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com