
Cracker Barrel (CBRL) Stock Jumps As Margins Hold While Traffic Slips
The market finally gave Cracker Barrel Old Country Store a break. The stock jumped about 4.5% to US$47.52 on Wednesday, a sharp move for a chain that has been better known lately for traffic pressure and thin profitability than for upside surprises.
What moved the needle was not booming sales. Quarterly revenue landed at US$849.3m and basic earnings per share came in at just US$0.55, modest numbers for a casual dining and retail hybrid. The real story is that adjusted profitability held up better than many feared in the face of weak comparable restaurant volumes and a still tight cost base.
Is Cracker Barrel Old Country Store now a quietly mispriced comeback story, or just an expensive way to own 1% net margins and a rich P/E against weaker profit trends? Compare that story with the valuation analysis for Cracker Barrel Old Country Store
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs. Q4 2025): US$849.3m vs. US$868.0m (declined 2.2%)
- Net Income (Q4 2026 vs. Q4 2025): US$12.2m vs. US$6.8m (up 80.7%)
- Basic EPS (Q4 2026 vs. Q4 2025): US$0.55 vs. US$0.30 (up 80.0%)
- Same Restaurant Sales (Q4 2026 vs. Q4 2025): declined 2.1% vs. grew 2.6% (traffic down 6.1%, average check up 4.2% in Q4 2026)
Tired of scrolling through paragraphs of earnings commentary and raw figures for Cracker Barrel Old Country Store? See the full financial picture, including how the valuation compares with the recent results in the company report for Cracker Barrel Old Country Store.
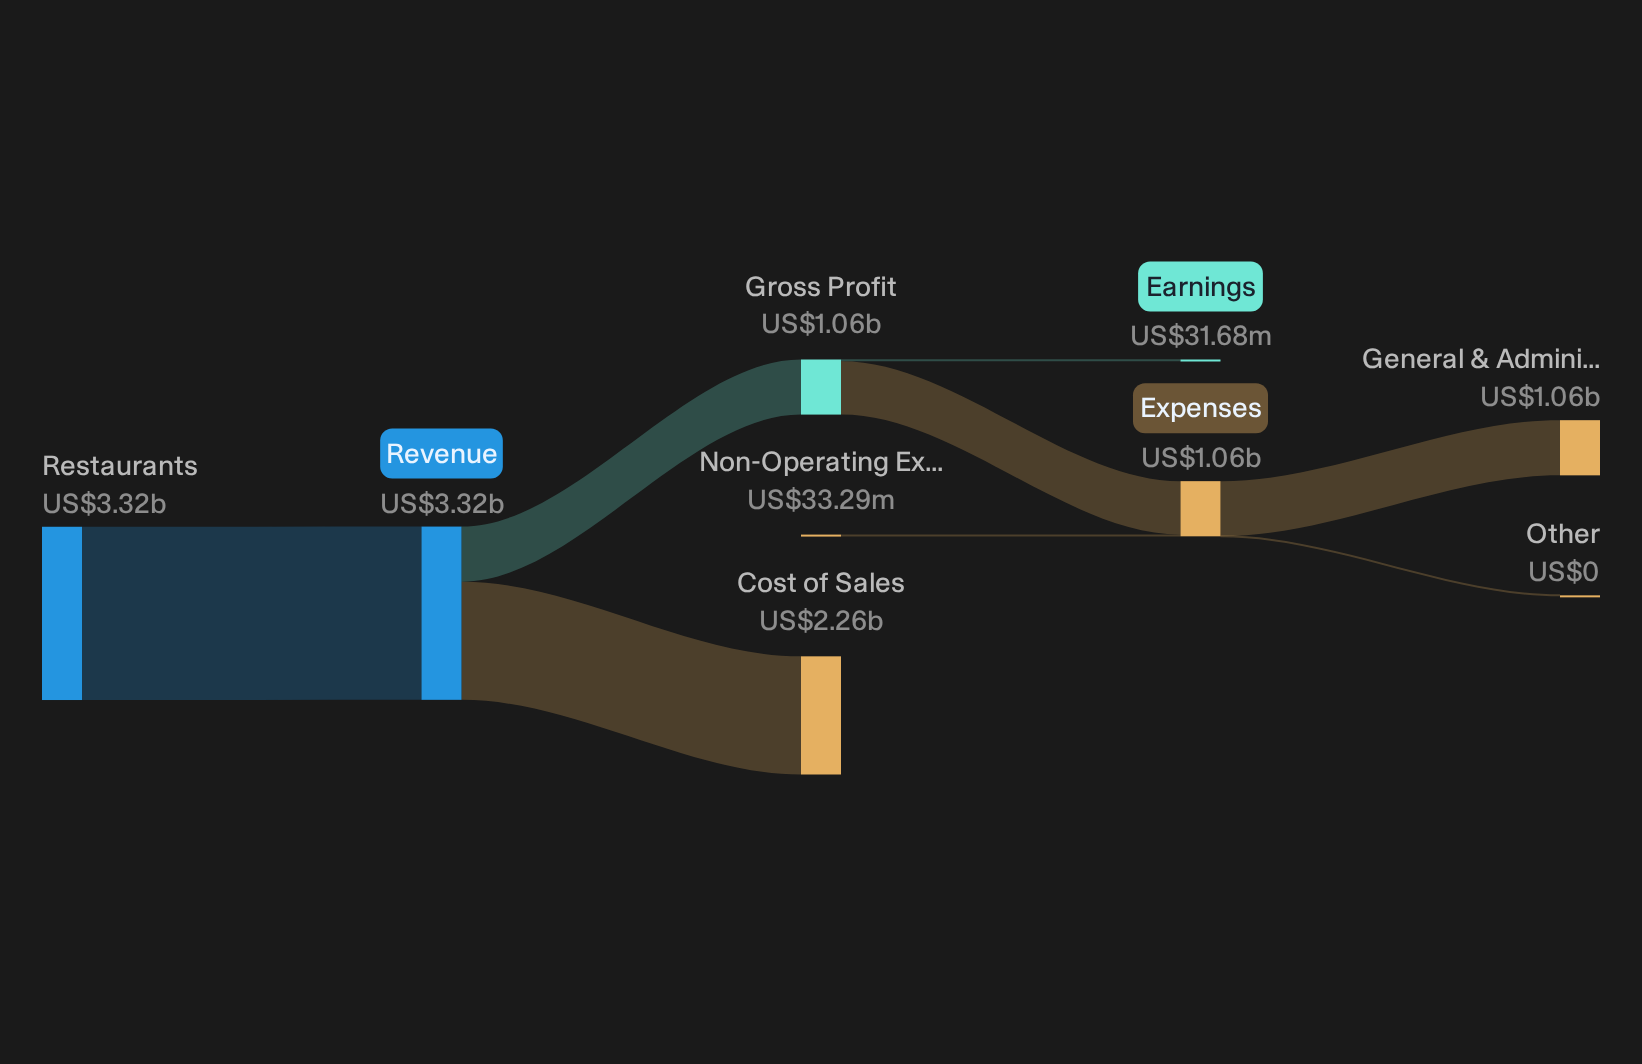
Evaluating Cracker Barrel’s Turnaround Milestones
Bulls argue Cracker Barrel is in a real operational reset, with efficiency gains, a cleaner balance sheet, and more engaged guests starting to show up in the numbers. The latest quarter gives that view partial support. Adjusted EBITDA reached US$62.1m and 7.3% of revenue, which confirms margin work is gaining traction, even after stripping out a one time tariff tailwind and legal noise. Cost of goods at 28.8% of sales, down from 30.5%, lines up with the promised back of house redesign and sourcing focus.
Traffic is where the story fails its own test for now. Comparable restaurant sales declined 2.1% on a 6.1% fall in guest counts, and average check only offset part of the hole. Retail comps grew 0.7% and loyalty penetration above 40% of tracked sales support the engagement claim, but do not yet show broad top line reacceleration.
Reveal where the surface looks calm but the models quietly diverge, and see what the street is really penciling in for Cracker Barrel Old Country Store over the next few years with the full analyst estimates for Cracker Barrel Old Country Store.Cracker Barrel Bears Still See Traffic And Mix Gaps
Critics argue Cracker Barrel Old Country Store runs a structurally challenged model where weak guest counts and rising costs keep net margins stuck around 1%. The latest quarter does not fully disprove that view. Comparable restaurant sales declined 2.1% on a 6.1% traffic drop, so pricing and mix around a 4.2% higher check did not restore volume.
Operational work helped adjusted EBITDA reach US$62.1m at 7.3% of revenue, yet that result leaned on a US$15.0m tariff refund and still rode commodity inflation of about 3.1% and higher labor at 37.5% of sales. Guidance for fiscal 2027 points to revenue growth and adjusted EBITDA of US$180m to US$200m with no new units, but that ambition rests on comp growth from a base where guest counts are still falling. Bears looking for hard evidence of durable traffic health did not get it this quarter.
After guest counts fall, while one-time tariff refunds and an elevated debt load support earnings optics, review our independent risk analysis for Cracker Barrel Old Country Store which shows 3 important warning signsStay Ahead With Simply Wall St
If the mix of thin margins, traffic pressure, and one time tariff support at Cracker Barrel Old Country Store has your curiosity up, register for free with Simply Wall St and add it to a Watchlist so you can track price against fair value and wait for your preferred entry point. After you build or adjust a position, keep your focus with the Portfolio Command Center that cuts through noise and surfaces only the most important developments for your holdings. For a longer view, compare your thinking with thousands of others through the Community and see how different investors are interpreting the same numbers. That mix of tools helps you spot hidden catalysts and risk signals early so you can act before the wider market catches up.
Seeking Alternatives Beyond Cracker Barrel?
Fresh ideas move first, and late money often chases the last breakout while early entries ride real momentum under the radar for now. Scan these curated lists and get in early.
- Hunt for cash rich opportunities that could be quietly re rating while attention stays elsewhere with a curated set of 30 high quality undervalued stocks.
- Track companies powering AI’s plumbing before they go from overlooked to flying on new demand by scanning the hand picked 85 AI infrastructure stocks.
- Target dependable income plays that might keep paying investors even when sentiment drops by reviewing a focused group of 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com