
How AI Testing Growth At Aehr Test Systems Stock Has Changed Its Investment Story
- Aehr Test Systems has attracted fresh attention in 2026 as investors focus on its AI related semiconductor burn in and test platforms, backed by a reported record backlog of about US$100.6 million and a fiscal 2027 revenue outlook of US$130 million to US$150 million.
- The surge of interest highlights that Aehr Test Systems’ exposure to AI processors, silicon photonics and power devices also brings customer concentration risk and sensitivity to semiconductor capital spending cycles.
- The focus is now on how Aehr Test Systems’ expanding AI semiconductor test role could reshape the investment narrative that investors rely on.
Scan beyond Aehr Test Systems and size up other AI exposed chip stocks with our hand picked 85 AI infrastructure stocks.
Aehr Test Systems Investment Narrative Recap
To own Aehr Test Systems today, you need to believe its AI focused burn in and test platforms can convert the reported US$100.6 million backlog and emerging silicon photonics, GaN and memory work into sustained system and consumables demand. The recent surge in attention does not change that the near term swing factor is how quickly those queued orders turn into shipped equipment and follow on WaferPak volumes.
The flip side is execution risk in a very concentrated customer base that is heavily tied to AI processors and data center capex. Any pause in spending, qualification delay or technology shift could hit utilization just as Aehr Test Systems is running with expanded capacity, higher fixed costs and ongoing legal expenses.
The most relevant piece of context for this year’s enthusiasm is the combination of that record backlog and the fiscal 2027 revenue outlook of US$130 million to US$150 million. Those figures anchor expectations around how large the installed FOX and Sonoma base might become and how much recurring consumables revenue could build on top of it if customers keep qualifying new AI and photonics devices.
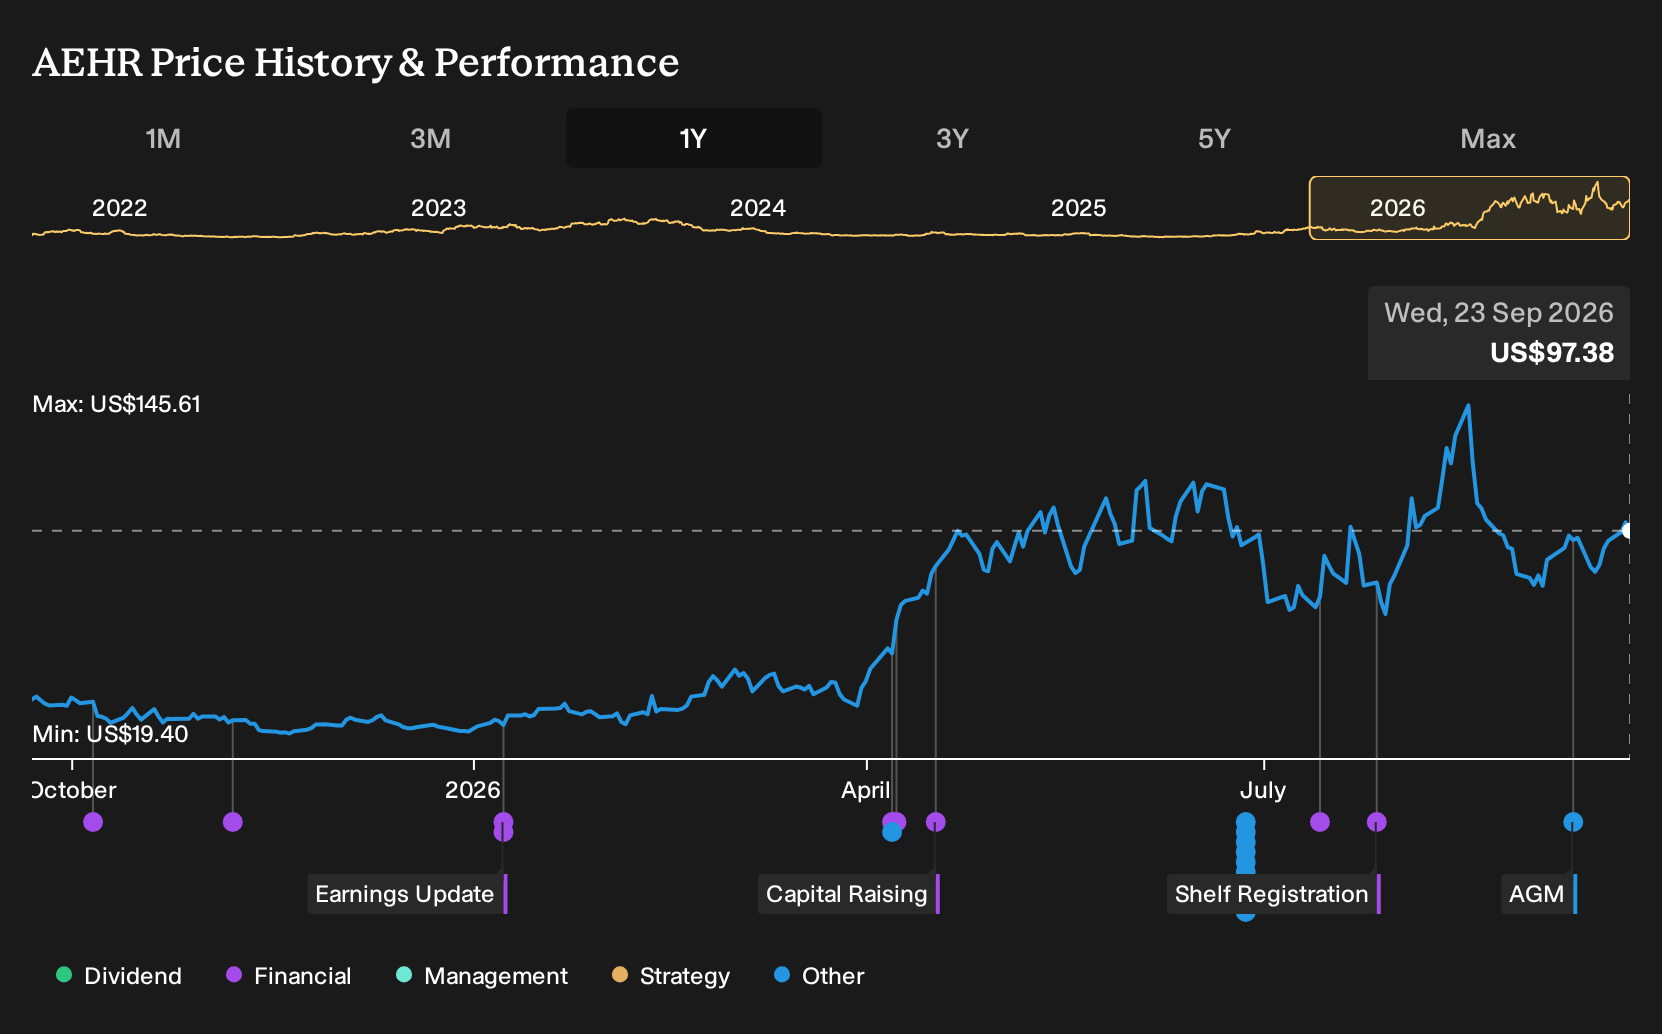
For you as an investor, the key question is how that outlook balances against the current premium P/B multiple and a share price that has already moved sharply in 2026. With earnings still negative and the business investing ahead of demand in Fremont, Southeast Asia and Taiwan, the catalyst path now runs through clean execution on existing AI and optical orders, plus evidence that newer areas like GaN power and memory can start to contribute.
Aehr Test Systems Analyst Assumptions In Focus
Aehr Test Systems' narrative projects US$270.6 million revenue and US$83.4 million earnings by 2029. This rests on analysts assuming 75.6% yearly revenue growth and an earnings swing of about US$90.5 million from a loss of US$7.1 million today to that future profit level.
Uncover why Aehr Test Systems' fair value signals a 33% potential upside to its current price, a discount that could narrow faster than many investors anticipate.
Exploring Other Perspectives
Now contrast that bullish backlog story with the lowest Aehr Test Systems analysts, who worry more about customer concentration. They still pencilled in around US$291.9 million revenue and US$96.7 million earnings for 2029 before this 2026 surge, which is actually more optimistic than consensus. That gap shows how widely views can differ, so consider several perspectives before deciding what this news might mean for you.
Explore 4 other Aehr Test Systems fair value estimates, including one that suggests as much as 86% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Aehr Test Systems research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Aehr Test Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aehr Test Systems' overall financial health at a glance.
Looking For More Ideas Beyond Aehr Test Systems?
If the Aehr Test Systems story has sharpened your thinking about AI exposed hardware, use that momentum to broaden your watchlist with other companies that match your risk, income, and quality preferences.
- If you are comfortable with higher volatility in exchange for potential upside, scan for smaller high potential opportunities through our 9 elite penny stocks with strong financials.
- If resilience and balance sheet strength matter most to you, sort for financially robust businesses using our list of solid balance sheet and fundamentals (23 results).
- If you want income on top of price moves, focus on cash return potential with our 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com