
Impinj (PI) Draws Fresh Valuation Focus, Is Most Of The Upside Already Priced In?
Impinj (PI) continues to attract attention after recent share price moves, with the stock last closing at US$177.63. Investors are weighing that valuation against the firm’s RAIN RFID platform and its reported financial profile.
Recent trading has been choppy, with a 10.32% 1-month share price return and a 32.24% 90-day share price move contrasting with a slight year-to-date decline. At the same time, a 3-year total shareholder return above 200% suggests longer term momentum in Impinj remains influential for sentiment.
Scan beyond Impinj’s recent surge and compare it with hand-picked peers using the 85 AI infrastructure stocks.
After a rapid climb and with Impinj now close to some analyst targets, investors are asking whether most of the easy upside has already played out or whether the recent move still leaves meaningful headroom on valuation.
Most Popular Narrative: 2% Undervalued
Impinj is trading at $177.63 against a widely followed fair value estimate of about $180.89, so the current price roughly lines up with that narrative while still implying a small valuation gap that bulls are watching closely.
M800 and Gen2X platform enhancements, including improved readability, faster inventory counting, and unique enterprise use cases (like loss analytics), are driving higher gross margin product mix and expanding the company's addressable market by enabling new categories such as food, high-value apparel, and hard-to-read items. Sustained adoption of these products bolsters future gross margins and earnings.
See why 18 investors see Impinj as 2% undervalued.
Result: Fair Value of $180.89 (UNDERVALUED)
Still, the Impinj story cuts both ways. Reliance on a small group of large customers and recent year over year revenue softness are both capable of undermining that fair value narrative.
Find out about the key risks to this Impinj narrative.
Another View: Impinj Looks Expensive On Sales
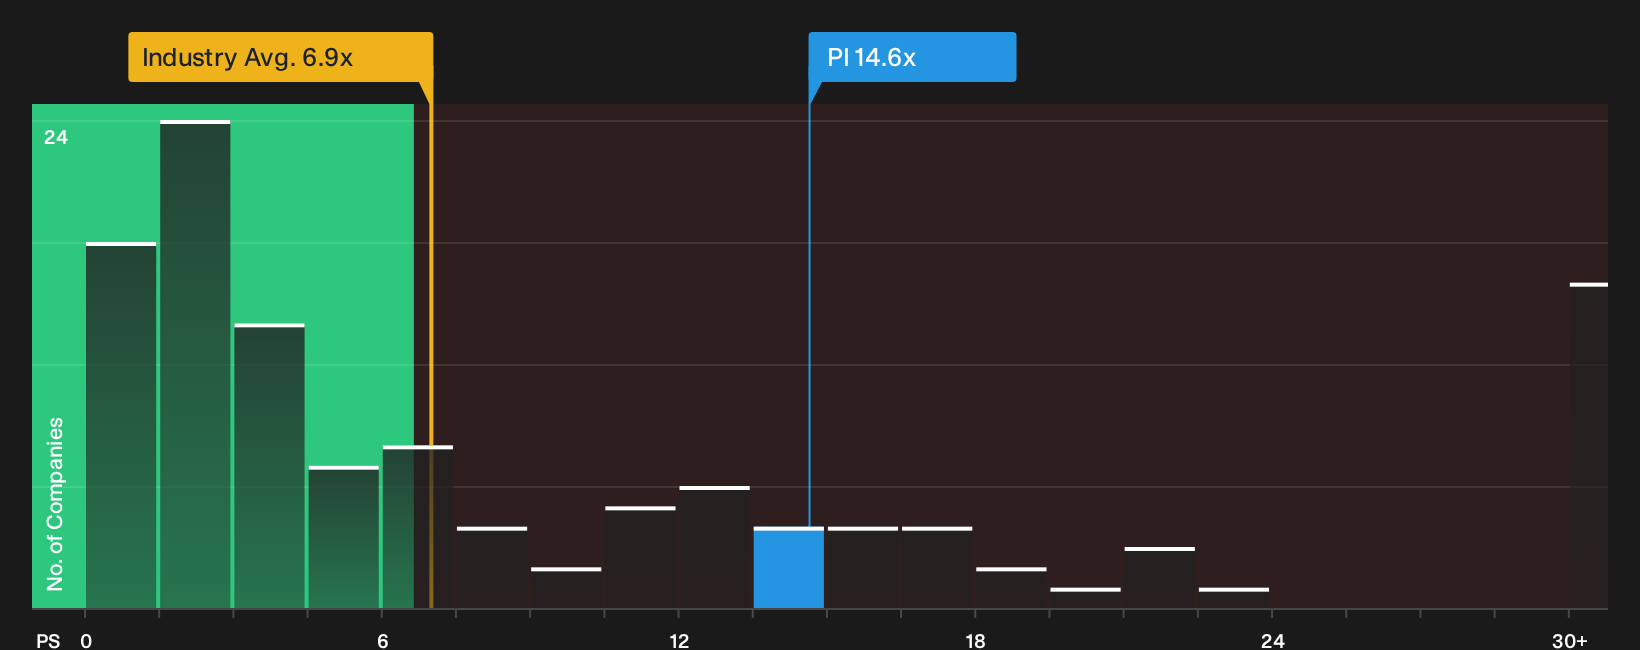
The earlier narrative leans on future earnings to argue Impinj is only slightly undervalued. Using a simple P/S cross-check, the picture looks less forgiving. At about 14.6x sales, the stock trades at more than double its fair ratio of 6x.
That gap is also wide versus the US Semiconductor group at 6.9x and a peer average of 6.1x. In plain terms, buyers today are paying a premium price for each dollar of Impinj revenue, so the key question is whether personal assumptions justify paying more than twice what the market could move toward as a fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Impinj valuations so far. If you want to move quickly and build your own take on the upside case, start by checking 1 key reward.
Looking for more Impinj style investment ideas?
If you like the Impinj setup but want a broader watchlist, use the Simply Wall Street Screener to hunt for fresh opportunities before others catch on.
- Target potential value opportunities by scanning a curated 30 high quality undervalued stocks that blends quality fundamentals with discounted prices.
- Prioritise resilience and sleep-at-night holdings using a 31 resilient stocks with low risk scores built around business strength and lower risk profiles.
- Spot early-stage potential by reviewing a focused 9 elite penny stocks with strong financials that screens for smaller companies with stronger financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com