
Gentherm (THRM) Dropped, So What Is Driving Attention Now?
Gentherm (THRM) received shareholder approval at a special meeting on September 10, 2026 to amend its Articles of Incorporation and increase authorized common shares tied to a pending merger agreement.
Gentherm shares have come under pressure around the merger related vote, with the share price down 10.7% over the past month and 7.2% over the last week, even though the 1 year total shareholder return is slightly positive while the 3 and 5 year total shareholder returns are deeply negative. This points to fading long term momentum despite the latest corporate catalyst.
Scan how other auto and medical suppliers are priced against Gentherm by reviewing our hand picked 30 high quality undervalued stocks.
Bulls point to Gentherm’s recent revenue and net income growth and the pullback as an entry, while bears focus on weak multi year returns and a low value score. Which side does current pricing actually support?
Most Popular Narrative: 23% Undervalued
Gentherm last closed at $35.22, while the most widely followed narrative assesses fair value at $45.71. The stock is framed as undervalued relative to that anchor and tied to a set of specific growth drivers and risks.
Accelerating adoption of comfort and wellness features (like pneumatic lumbar, massage, and climate-controlled seating) by mainstream, high-volume vehicle platforms, demonstrated by new multi-year awards from Ford, GM, Hyundai, and multiple Chinese OEMs, suggests higher content-per-vehicle and robust revenue growth ahead as these features become industry standard rather than luxury-only.
See why 2 investors see Gentherm as 23% undervalued.
The narrative applies an 8.75% discount rate and assumes revenue growth of 11.81% with profit margins reaching 7.33%. This produces a fair value estimate of $45.71 that sits well above both the current share price and Gentherm’s 1 year total return profile. That gap, combined with the company’s forecast 60.1% annual earnings growth and a projected 40.3% return on equity in three years, underpins the view that current pricing does not fully reflect the earnings and cash flow path embedded in the model.
At the same time, the same storyline flags execution issues such as recent margin pressure, one off losses of $23.8m affecting the latest 12 month results, a relatively low current return on equity of 3.7%, and a management team with a short average tenure of 1.7 years. Those factors help explain Gentherm’s low value score of 2, the decline of 23.6% per year in earnings over the past five years, and the weak multi year shareholder returns, even as the discounted cash flow framework still points to upside from $35.22.
Putting it together, Gentherm is framed as a business with improving revenue and net income growth, a diversified portfolio across Automotive and Medical, and a discounted share price relative to a $45.71 fair value. However, there are real risks tied to Asia exposure, customer concentration, and earnings quality that investors need to weigh against the recent merger developments and buyback plans.
Result: Fair Value of $45.71 (UNDERVALUED)
Still, Gentherm’s heavy reliance on a concentrated group of auto customers and its weaker Asian footprint could quickly challenge this upside story if contract wins or regional traction disappoint.
Find out about the key risks to this Gentherm narrative.
Another View: Gentherm Through The P/E Lens
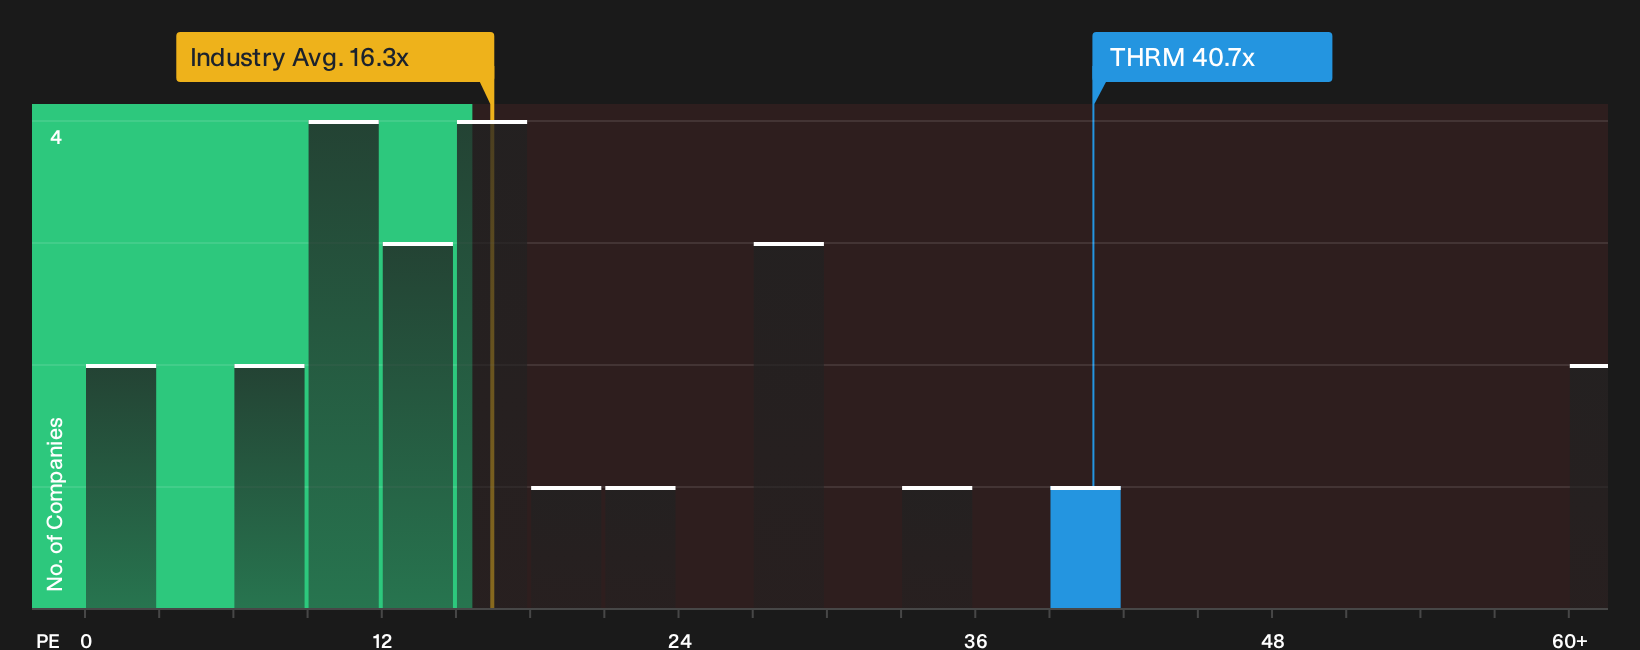
Gentherm might look cheap on the narrative fair value of $45.71, but the current P/E of 40.7x tells a tougher story. That multiple is far above the US Auto Components industry at 16.3x and only slightly higher than its fair ratio of 39.2x, which suggests limited room for error if expectations slip.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Gentherm is clearly split today, with pressure on the share price but a merger story and growth forecasts in the background. Act while the data is fresh and weigh the upside against the downside by reviewing the 2 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Gentherm?
If Gentherm has your attention but you want a wider bench of opportunities, now is the moment to line up a few fresh candidates before others do.
- Target potential upside in smaller companies by scanning a 9 elite penny stocks with strong financials that filters for stronger financial profiles instead of pure speculation.
- Hunt for quality at a discount by reviewing a 30 high quality undervalued stocks that focuses on solid cash flows and balance sheet strength.
- Prioritise resilience first by using a 31 resilient stocks with low risk scores designed to surface businesses with lower risk scores and steadier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com