
Regeneron Pharmaceuticals (REGN) Could Be 4% Undervalued Following Class Action Filing
Regeneron Pharmaceuticals (REGN) is back in focus after investors were hit with news of a securities class action related to its Phase III Fianlimab Libtayo trial disclosures and alleged flaws in the study’s statistical assumptions.
At a share price of US$801.82, Regeneron Pharmaceuticals has seen short term momentum cool after a recent 3.2% one month share price decline. This contrasts with the 90 day share price return of 29.3% and 1 year total shareholder return of 39.7%, which point to stronger underlying interest, with the class action filing adding a fresh layer of risk perception to that recent performance.
Pressure test the Regeneron Pharmaceuticals story against peers by scanning 30 resilient stocks with low risk scores that have held up better when legal or clinical surprises hit the headlines.
After a sharp run over 90 days and a fresh legal overhang, Regeneron Pharmaceuticals at around US$801 a share forces a choice: pay up for resilience now, or wait and risk missing any valuation support already in the price.
Most Popular Narrative: 4% Undervalued
Regeneron Pharmaceuticals is trading at US$801.82 against a most-followed fair value estimate of US$833, which implies modest upside while the class action noise circles the story.
Regeneron's broad and advancing pipeline, including recent or upcoming pivotal data in immunology, oncology (notably Lynozyfic and odronnextamab), genetic medicines, and obesity, positions the company to benefit from demographic-driven increases in demand for advanced therapies and from the rise in personalized and precision medicine, supporting future revenue growth and pipeline-driven earnings upside.
See why 85 investors see Regeneron Pharmaceuticals as 4% undervalued.
Result: Fair Value of $833 (UNDERVALUED)
Still, the narrative around Regeneron Pharmaceuticals could shift quickly if EYLEA pressure intensifies or further pipeline setbacks deepen concerns about long term earnings power.
Find out about the key risks to this Regeneron Pharmaceuticals narrative.
Another View On Regeneron Pharmaceuticals Valuation
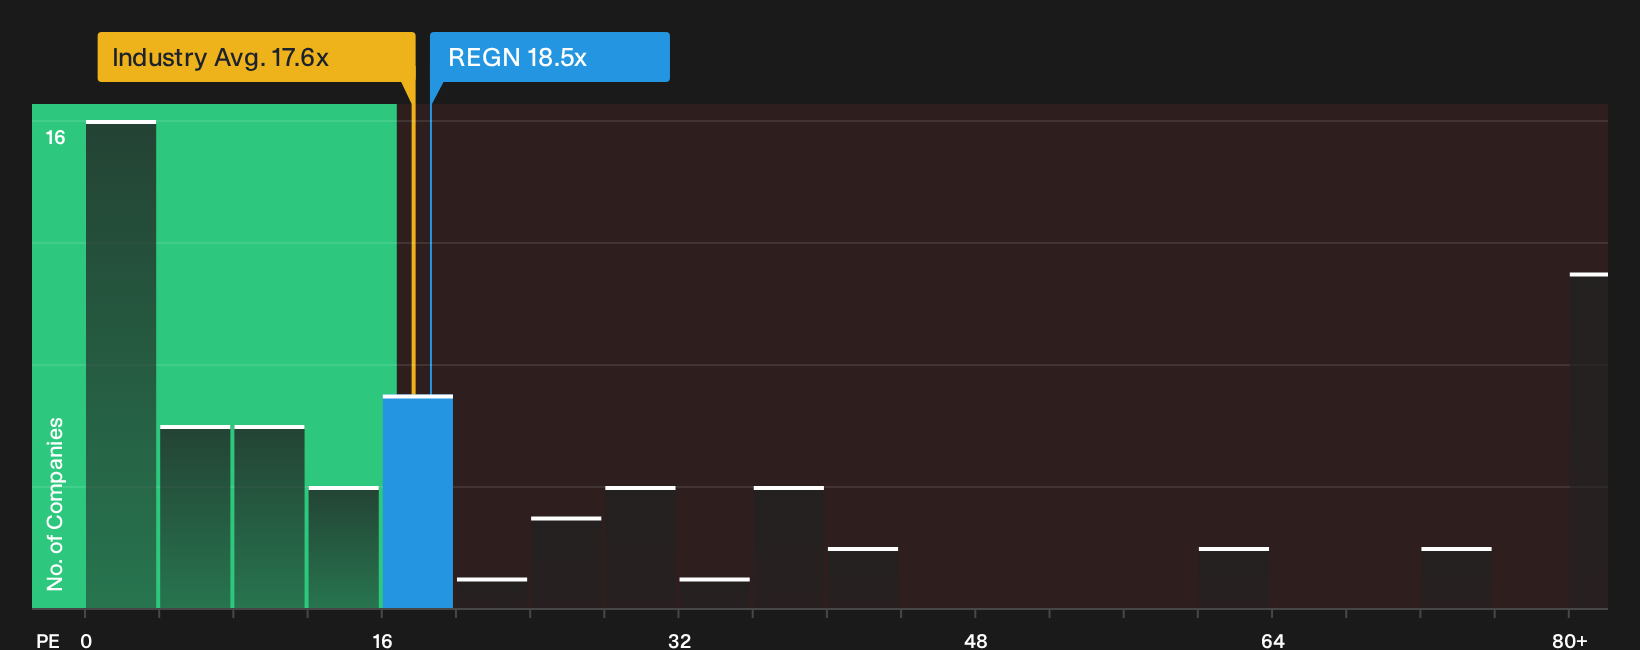
On simple P/E math, Regeneron Pharmaceuticals tells a different story. The stock trades on 18.5x earnings, which is slightly above the US Biotechs average of 17.6x, yet materially below both the peer average of 27.7x and an estimated fair ratio of 28.3x. That gap suggests the market is either building in extra execution risk or leaving room for a re-rating. Which side of that trade do you think is more realistic?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the cautious optimism in this piece really holds up for Regeneron Pharmaceuticals once you strip it back to the raw numbers? Move fast, review the underlying drivers yourself, and see what investors are focusing on in the 2 key rewards.
Looking for more investment ideas beyond Regeneron Pharmaceuticals?
Use the momentum from your Regeneron Pharmaceuticals research and put a wider watchlist to work, so you do not miss the next opportunity that fits your playbook.
- Target dependable cash flows and balance sheets by scanning our list of solid balance sheet and fundamentals (23 results) to help anchor a more resilient portfolio.
- Hunt for potential mispricings with the 16 high quality undiscovered gems that many investors may not be watching yet.
- Stack your watchlist with return-focused ideas by checking the 7 dividend fortresses that combine income potential with disciplined payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com