
Should Earnings Estimate Upgrade Require Action From SL Green Realty Stock Investors?
- SL Green Realty Corp. declared cash dividends on common and Series I preferred stock payable on October 15, 2026, to holders of record on September 30, 2026, with annualized payouts of $2.47 and $1.625 per share respectively.
- The reaffirmed common and preferred distributions highlight SL Green Realty's focus on returning capital to investors while managing Manhattan office exposure through its REIT structure and balance sheet choices.
- This article examines how SL Green Realty's dividend affirmation and earnings estimate upgrade may reshape the broader investment narrative around Manhattan offices.
Scan beyond SL Green Realty to compare its latest dividend move with a curated 7 dividend fortresses that are also returning cash to shareholders right now.
SL Green Realty Investment Narrative Recap
To own SL Green Realty, you need to believe Manhattan office demand for high quality space remains resilient enough for occupancy and rents to support a still highly leveraged balance sheet. In the near term, the key swing factor is leasing and asset recycling, which feed directly into cash generation and flexibility around debt and redevelopment projects.
The fresh dividend affirmation does not radically change that picture. It underlines management’s current view on cash availability, but interest costs, tenant churn and execution risk on projects like office to residential conversions remain the main watchpoints. If leasing or asset sales soften, dividends could sit in tension with balance sheet priorities.
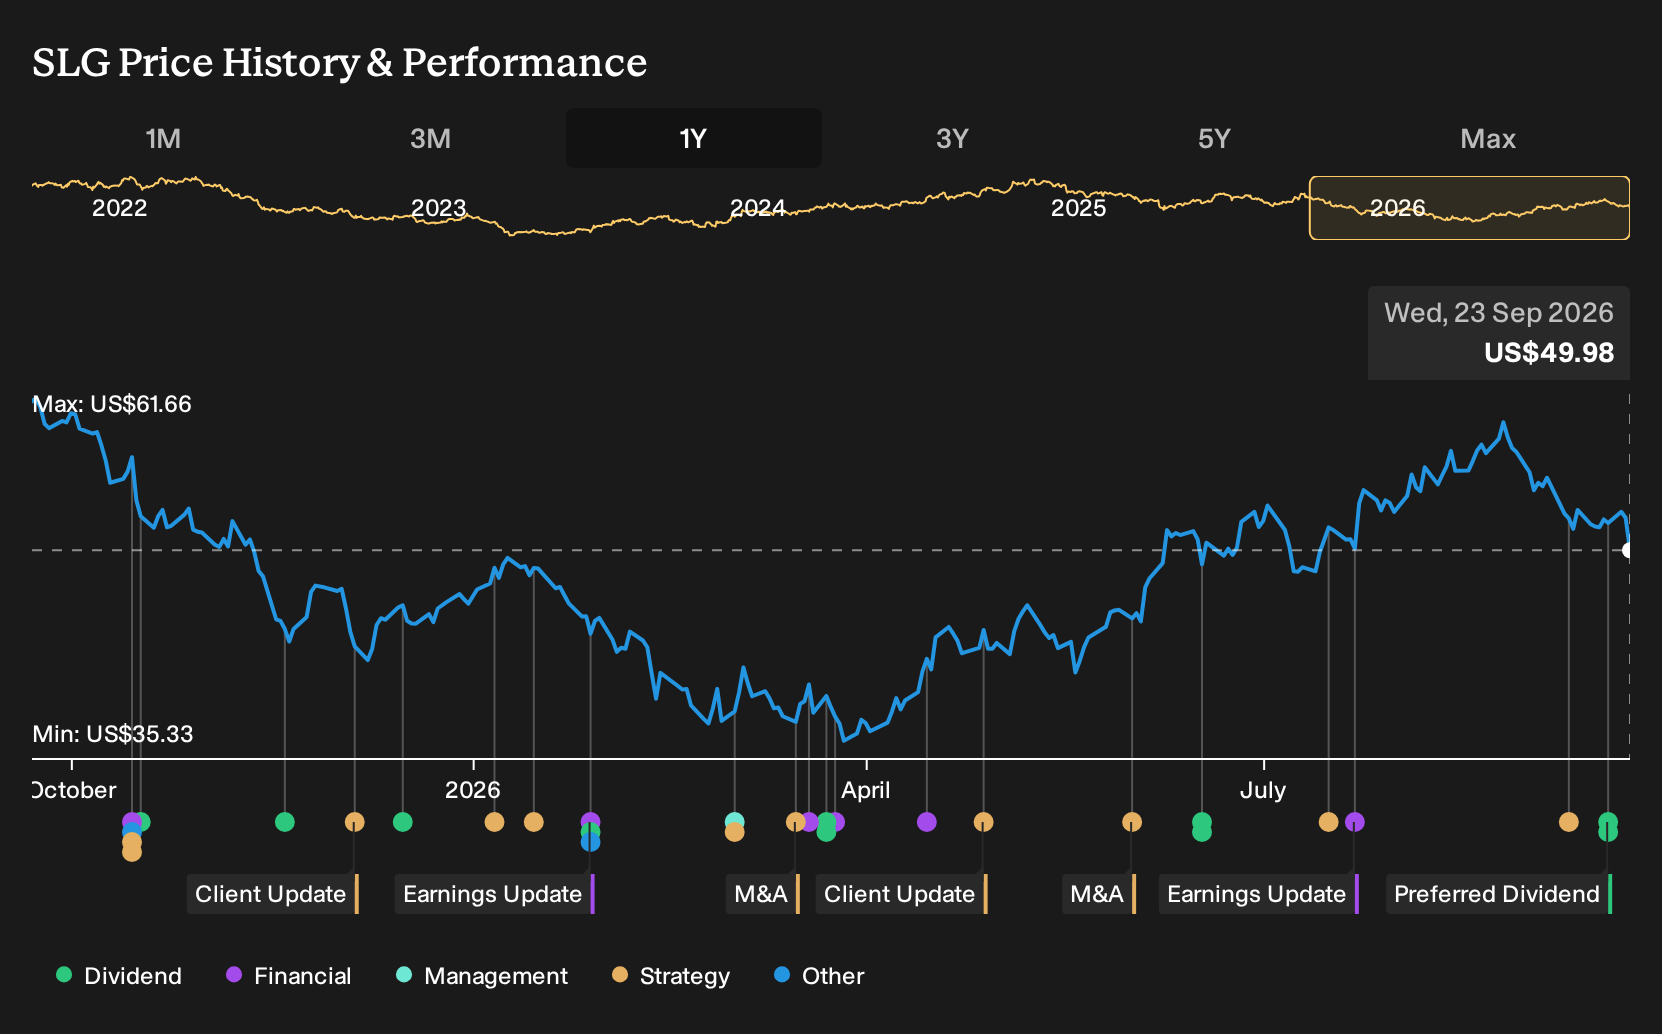
The common dividend declaration of $0.6175 per share, or $2.47 annualized, is the clearest piece of news for you to weigh. It signals that SL Green Realty is continuing to return cash even while the business is unprofitable and interest payments are not well covered by earnings, according to existing analysis.
That decision keeps income on the table for shareholders, yet it also keeps the spotlight on funding, refinancing and asset sale execution. With the dividend previously flagged as not well covered by free cash flow, the key questions now center on leasing momentum, proceeds from dispositions, and how quickly those can ease pressure from higher cost debt.
SL Green Realty's current analyst narrative points to forecast revenue of US$649.5 million and earnings of US$1.7 million by 2029. This outlook is built on an assumed annual revenue decline of 13.3%, and a move from a loss of US$192.1 million in earnings today to a small profit that requires an earnings swing of about US$193.8 million over that period.
Uncover why SL Green Realty's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One big swing factor that more optimistic analysts focus on is the potential Times Square casino. Before this dividend news, the most bullish forecasts already penciled in revenue of about US$685.2 million and earnings of US$93.3 million by 2029, far above consensus. That gap shows how widely views on SL Green Realty can differ, and why it can help to explore several narratives before deciding how this latest dividend call fits your own expectations.
Explore 2 other SL Green Realty fair value estimates, including one that suggests there could be as much as 56% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own with SL Green Realty.
- A great starting point for your SL Green Realty research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SL Green Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SL Green Realty's overall financial health at a glance.
Looking for more investment ideas beyond SL Green Realty?
Once you have a view on SL Green Realty, it can help to put it in context by scanning other opportunities with different risk profiles, income streams and balance sheet setups.
- If you want potential income plus resilience, review a curated set of steady payers through our 7 dividend fortresses that have track records of distributing cash to shareholders.
- For investors focused on quality at a reasonable price, compare SL Green Realty with a 29 high quality undervalued stocks that combines solid fundamentals with pricing that may not fully reflect those strengths.
- When capital preservation ranks high on your checklist, filter for defensively positioned companies using a 30 resilient stocks with low risk scores that screens for businesses with lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com