
Spire (SR) Could Be 19% Undervalued Despite Its Recent Pullback
Spire (SR) has been drawing fresh attention after recent share performance metrics showed mixed signals for investors. The stock closed at US$77.39, with returns over the past month and the past 3 months both in decline.
Short term momentum for Spire looks soft, with the share price down 6.1% over the past month and 7.0% year to date. However, longer term total shareholder returns of 2.2% over one year and more than 50% over three and five years suggest the recent pullback follows a period of stronger performance.
Scan for other utilities showing similar pullbacks with solid multiyear returns by reviewing the hand picked 30 resilient stocks with low risk scores alongside Spire.
For Spire, the recent slide clashes with steady multiyear returns and positive revenue and net income trends. Is this pullback about the utility’s fundamentals or a swing in sentiment, and what could that imply for valuation going forward?
Most Popular Narrative: 19% Undervalued
On the most followed narrative, Spire screens as undervalued, with an implied fair value of $95 against a last close of $77.39. That gap rests on a view that the utility can convert regulated expansion into steadier cash flows over time.
Significant and ongoing investments in infrastructure modernization and system resilience, supported by constructive regulatory frameworks and reliable cost recovery mechanisms, are growing Spire's regulated asset base, which should result in higher allowed returns and gradual increases in net income.
See why 0 investors see Spire as 19% undervalued.
Result: Fair Value of $95 (UNDERVALUED)
Still, the bullish Spire narrative depends on steady gas demand and constructive regulators, and both electrification policies and tougher rate decisions could challenge that outlook.
Find out about the key risks to this Spire narrative.
Another View: What Spire’s P/E Says
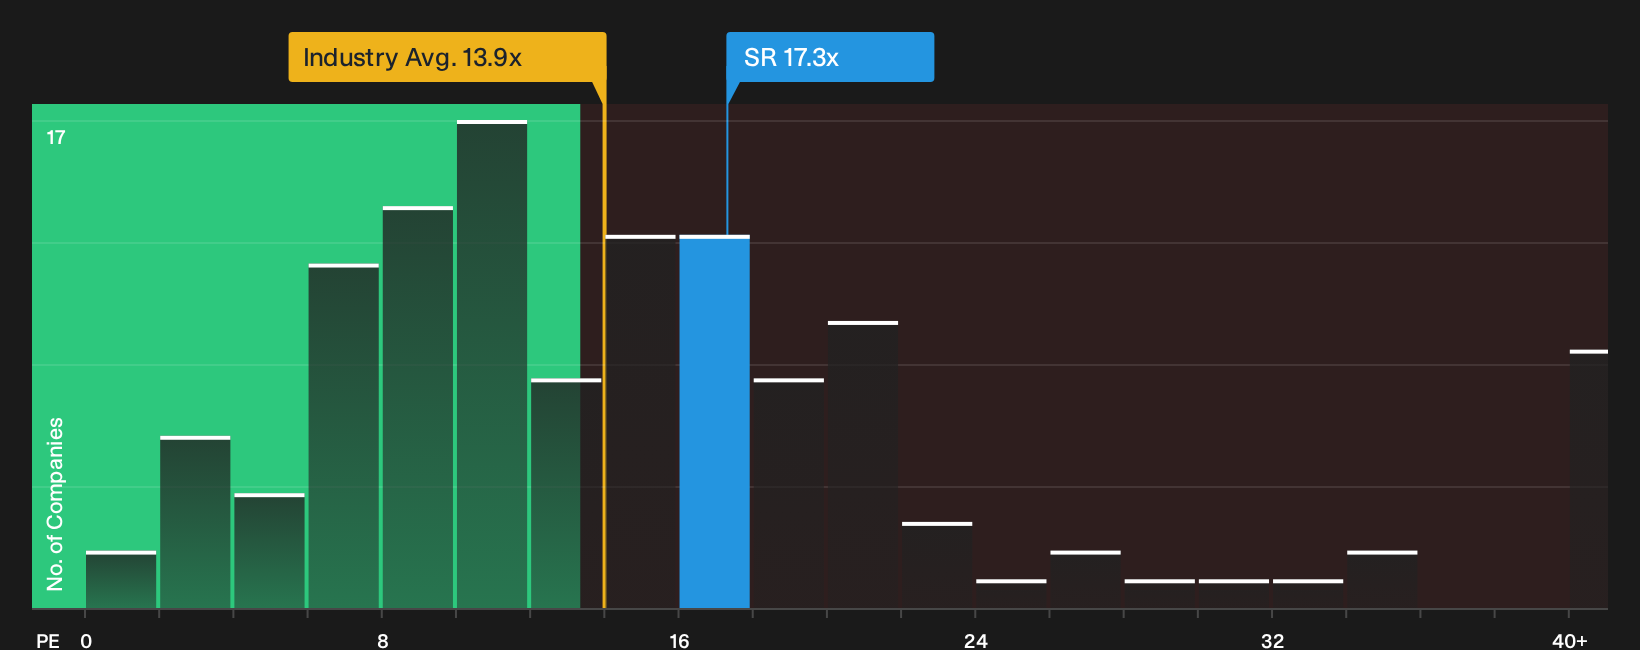
Spire may look undervalued on a fair value of $95, yet the P/E ratio of 17.3x paints a tougher picture. The stock trades richer than both US gas utility peers at 13.4x and the global group at 13.9x, even though its own fair ratio sits higher at 19.5x.
A premium P/E can reflect resilient earnings, but it also shrinks the margin for error if growth or regulation disappoints. The question for you is whether that gap to peers signals quality worth paying up for or valuation risk building quietly in the background.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Spire can feel messy, so take a moment to weigh both sides of the story and move quickly based on your own judgment with 3 key rewards and 2 important warning signs.
Looking for more Spire sized investment ideas?
If Spire has you thinking harder about pricing and risk, do not stop here. Broaden your watchlist now or you risk missing the next opportunity.
- Target resilient balance sheets and cash flows by scanning the list of solid balance sheet and fundamentals (23 results) that could handle tougher conditions without breaking stride.
- Hunt for quality at a discount by reviewing the 29 high quality undervalued stocks that pair fundamental strength with prices that still lag their underlying metrics.
- Stack potential income streams by comparing the 7 dividend fortresses that offer higher yields while still keeping an eye on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com