
Is Brink's (BCO) Still Undervalued Following Its Recent Pullback?
Brink's (BCO) drew fresh attention after recent trading left the stock roughly flat over the past day but down over the past week and month, despite a positive move across the past 3 months.
At a share price of $107.12, Brink's has seen short term momentum cool, with the 30 day share price return down 3.87% after a 90 day share price gain of 11.31%. In contrast, the 3 year total shareholder return of 58.48% and 5 year total shareholder return of 77.06% point to a materially different long run experience for investors.
Scan beyond Brink's and see how other cash flow focused companies with solid fundamentals are trading by checking our handpicked 29 high quality undervalued stocks.
Brink's has already rewarded long term holders, yet the recent pullback leaves a different question hanging. Is most of the easy money behind the stock, or do the current numbers still leave room for upside when you line up the valuation next?
Most Popular Narrative: 30% Undervalued
Against Brink's last close of $107.12, the most followed valuation story pins fair value at $153, which implies a sizeable discount and leans heavily on how its newer service lines reshape the business mix.
Rapid expansion and strong momentum in AMS (ATM Managed Services) and DRS (Digital Retail Solutions) are unlocking a significantly larger and higher-margin addressable market, with double-digit organic growth expected to accelerate in the back half of the year and into the mid-term supporting higher future revenue and net margins.
See why 5 investors see Brink's as 30% undervalued.
Result: Fair Value of $153 (UNDERVALUED)
Still, this narrative can break if the shift to digital payments curbs cash handling demand or if buybacks outweigh investment in Brink's technology and new markets.
Find out about the key risks to this Brink's narrative.
Another View: Brink's Looks Expensive On Earnings
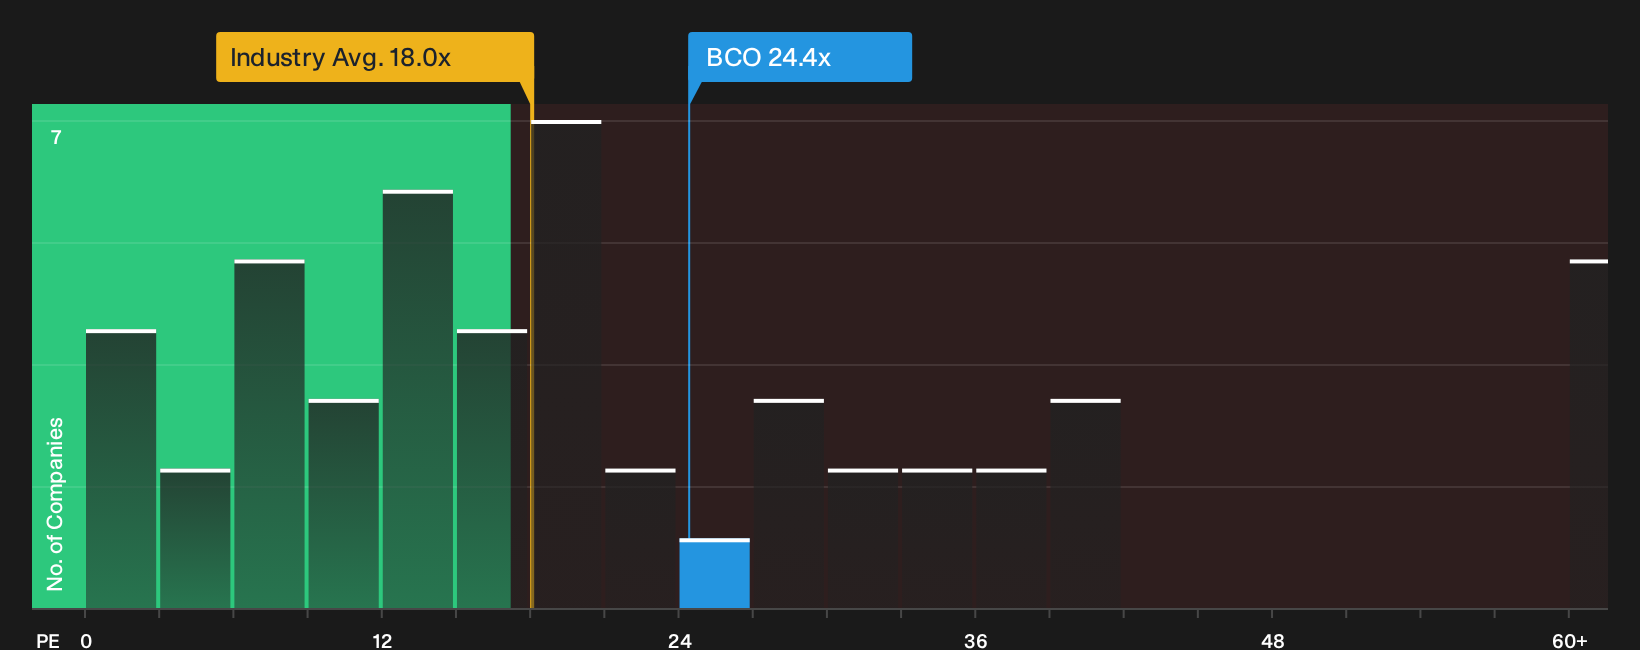
The DCF minded crowd sees Brink's as materially undervalued, yet the simple earnings yardstick tells a different story. On a P/E of 24.4x, the stock trades above the US Commercial Services average of 18x, even though the fair ratio points to an even higher 49.7x.
So investors face a real question. Is paying a premium multiple against the sector a sensible way to back that richer fair ratio, or does it load more valuation risk onto an already optimistic cash flow story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Brink's can pull you in both directions, so look through the full set of numbers and form your own view quickly, then weigh up the balance of 3 key rewards and 1 important warning sign.
Looking for more Brink's style investment ideas?
Brink's offers one angle on the market, but you widen your opportunity set when you actively scan for other quality stocks with different drivers and risk profiles.
- Target long term compounding potential by reviewing a curated mix of quality companies trading below estimated value through the 29 high quality undervalued stocks.
- Strengthen your focus on financial resilience by filtering for businesses with sturdy finances and reliable fundamentals via the list of solid balance sheet and fundamentals (23 results).
- Hunt for lesser known opportunities with robust metrics by scanning the 16 high quality undiscovered gems before the crowd pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com