
3 AI Stocks Trading Up To 48% Below Fair Value
Trump and Xi are now putting AI safety talks on the table, which underlines how critical advanced chips, cloud infrastructure and large language models have become for national security as well as business. That spotlight can focus attention on companies helping power this shift that still trade on undemanding valuations. This article walks through three such AI stocks from the screener that merit a closer look.
The three stocks highlighted below are only a small sample. The full screen surfaces 45 more companies that pair AI exposure with narratives that may be just as compelling for further research.
To see the wider field and pressure test your own ideas, head straight into the Undervalued Artificial Intelligence/ AI Stocks screener to identify, analyze, and filter the AI opportunities that best fit your approach.
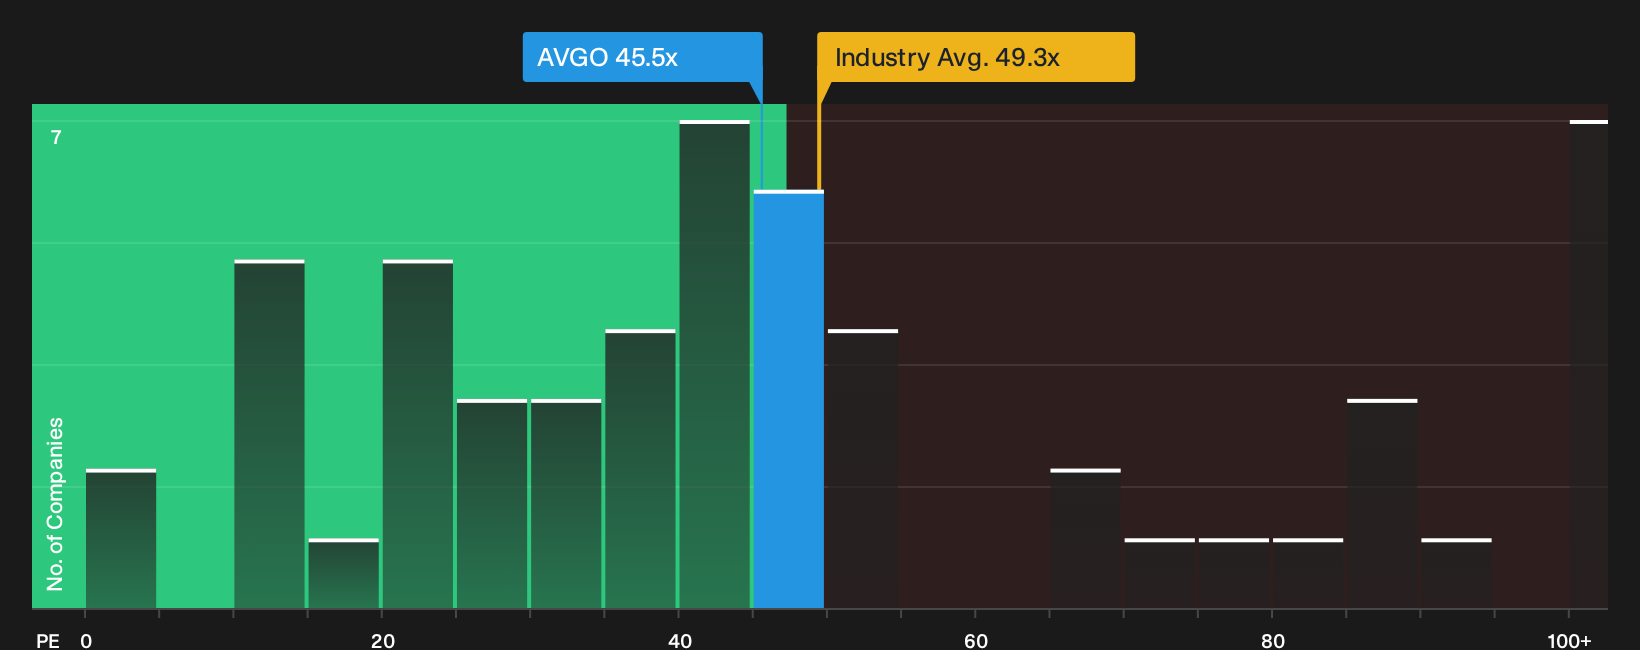
Broadcom (AVGO)
Overview: Broadcom is a global semiconductor and infrastructure software group whose high performance data center chips help power large scale AI workloads.
Operations: Broadcom generates about US$59.4b from Semiconductor Solutions and US$29.7b from Infrastructure Software, reflecting a hardware led AI infrastructure tilt.
Market Cap: US$1.7t
Broadcom matters for this AI screener because its networking chips, custom accelerators and private cloud software together form much of the plumbing behind large language models and enterprise AI rollouts.
"Broadcom is benefiting from several long-term trends simultaneously: growth in AI infrastructure, rising networking and bandwidth requirements, increasing data center complexity, greater demand for custom silicon solutions, and continued enterprise software monetization."
What happens to Broadcom’s AI edge depends on how one unresolved competitive pressure shapes demand, pricing power and long term profitability.
That unresolved pressure is exactly what the full narrative for Broadcom unpacks, describing how Broadcom’s AI plumbing could continue to advance even if headline demand patterns begin to shift.
Cerebras Systems (CBRS)
Overview: Cerebras Systems builds wafer scale AI chips and rack based compute systems that speed up large language model training and inference for hyperscale customers.
Operations: Cerebras currently reports US$680.7 million in semiconductor revenue, with sales concentrated in Europe, the Middle East and Africa and the United States.
Market Cap: US$49.5b
Cerebras Systems matters for this AI screener because its wafer scale engines and CS series racks are built specifically for ChatGPT scale generative workloads, giving hyperscalers and model labs a dedicated alternative to traditional GPU clusters.
"In late 2025, Cerebras signed a transformative Master Relationship Agreement with OpenAI, contractually bound to procure 750 megawatts of inference capacity through 2028 and backed by a $1.0 billion working capital loan to fund Cerebras's manufacturing scale-up."
What happens to Cerebras Systems’ margins and cash flows depends heavily on how one concentrated customer relationship and funding structure evolve.
That single relationship holds the key, and the full narrative for Cerebras Systems shows how Cerebras Systems could turn concentrated risk into accelerating scale, pricing power and optionality.

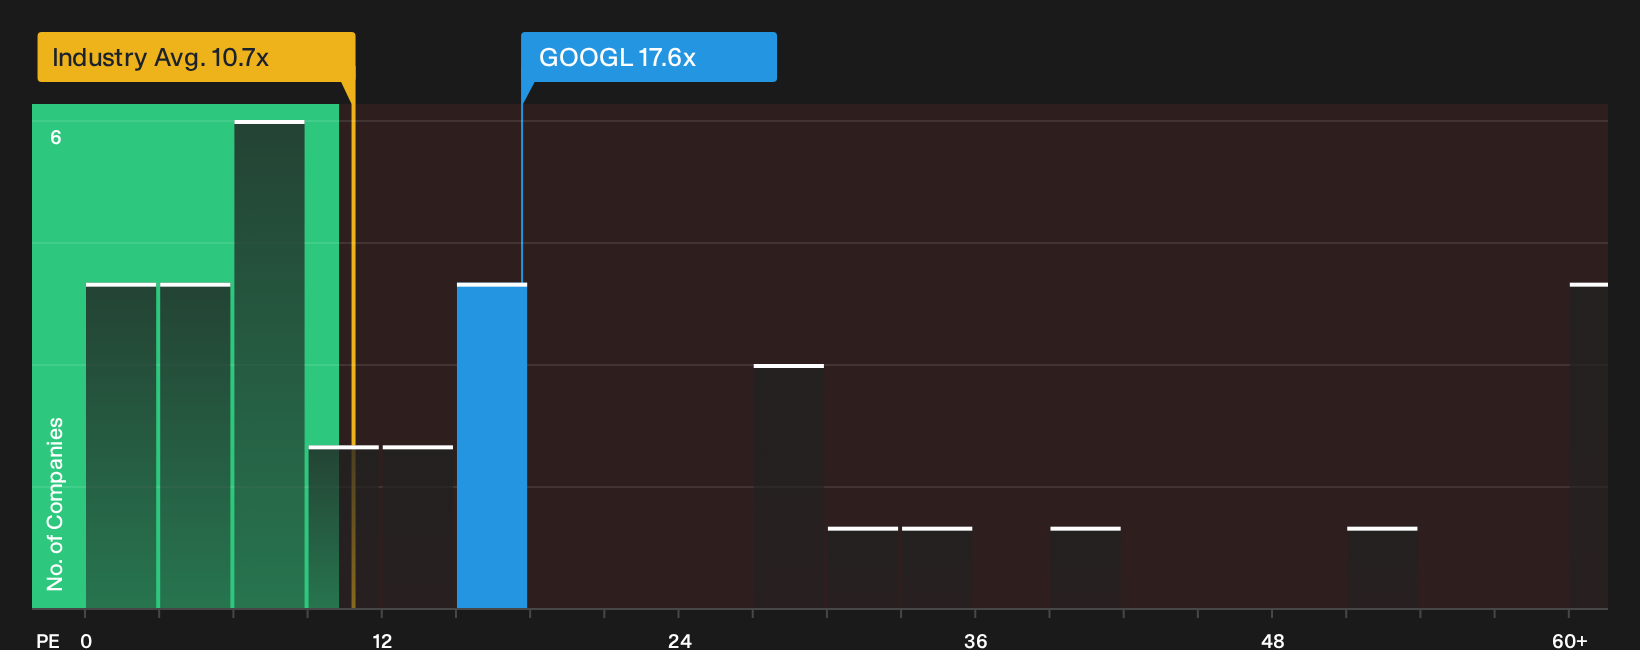
Alphabet (GOOGL)
Overview: Alphabet is the parent of Google, running a global ads and YouTube empire while Google Cloud powers enterprise AI through Vertex AI and Gemini.
Operations: Alphabet generates about US$367.1b from Google Services, US$77.6b from Google Cloud and US$1.5b from Other Bets, mostly across the United States and EMEA.
Market Cap: US$4.3t
Alphabet matters for this AI screener because Google Cloud’s Vertex AI and Gemini models give enterprises a ready made toolkit for building ChatGPT style applications on managed infrastructure.
"Google Cloud has gone from “meh” to money-maker, now #3 globally behind AWS and Azure with over 11% market share and AI-first services like Vertex AI and Duet AI."
What happens to Alphabet’s AI driven earnings path now hinges on how one capital heavy infrastructure bet reshapes future profitability and cash generation.
This is where the heavy infrastructure spend either compresses or accelerates value, and the full narrative for Alphabet shows how Alphabet’s AI flywheel could still be building.
Curious About AI Alternatives?
Fresh ideas move first. By the time the crowd spots real momentum, the best entry points can be gone. Scan these under the radar lists while it matters and review them early.
- Track cash rich small caps before they start hitting headlines by reviewing the 16 high quality undiscovered gems curated for quality and resilience.
- Target steady income while prices are still catching up by checking the 7 dividend fortresses built around durability and payout strength.
- Explore the build out of next generation infrastructure while valuations are still settling by scanning the 39 power grid technology and infrastructure stocks focused on critical grid and hardware players.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com