
USA Compression Partners (USAC) On Debt And Exchange Shift As Undervalued Case Holds
USA Compression Partners (USAC) has paired a planned $600 million private placement of 6.750% senior notes due 2035 with a decision to shift its common unit listing from the NYSE to the Texas Stock Exchange.
Recent trading tells a mixed story. USA Compression Partners’ 1 day, 7 day and 30 day share price returns are all down, yet the 90 day share price return of 2.98% and year to date gain of 7.40% suggest momentum has not fully rolled over. A 1 year total shareholder return of 19.36% and 5 year total shareholder return of 154.71% show those who stayed invested through earlier periods have been well rewarded.
Scan how USA Compression Partners compares with other income and infrastructure plays by running the curated 7 dividend fortresses alongside this latest debt and listing shift.
USA Compression Partners now trades at a clear discount to both analyst targets and intrinsic value estimates. Does that gap signal mispricing after the debt raise and listing shift, or does it represent a fair cushion for the risks involved?
Most Popular Narrative: 14% Undervalued
USA Compression Partners closed at $25.55, compared with a widely followed narrative fair value of about $29.67 that applies an 8.41% discount rate and a detailed earnings path through 2029.
Robust growth in natural gas demand fueled by AI, cloud computing, and massive new data center investments is driving a sustained need for reliable, high-horsepower compression solutions, which positions USAC for ongoing contract wins and steady revenue growth.
Continued expansion in LNG export capacity and related infrastructure is creating long-term volume growth opportunities for midstream service providers, favoring USAC's specialized fleet and supporting utilization, earnings, and margin strength.
See why 5 investors see USA Compression Partners as 14% undervalued.
Result: Fair Value of $29.67 (UNDERVALUED)
Still, USA Compression Partners faces real pressure points, including concentrated exposure to a handful of large customers and higher spending needs that can squeeze future flexibility.
Find out about the key risks to this USA Compression Partners narrative.
Another View on USA Compression Partners Valuation
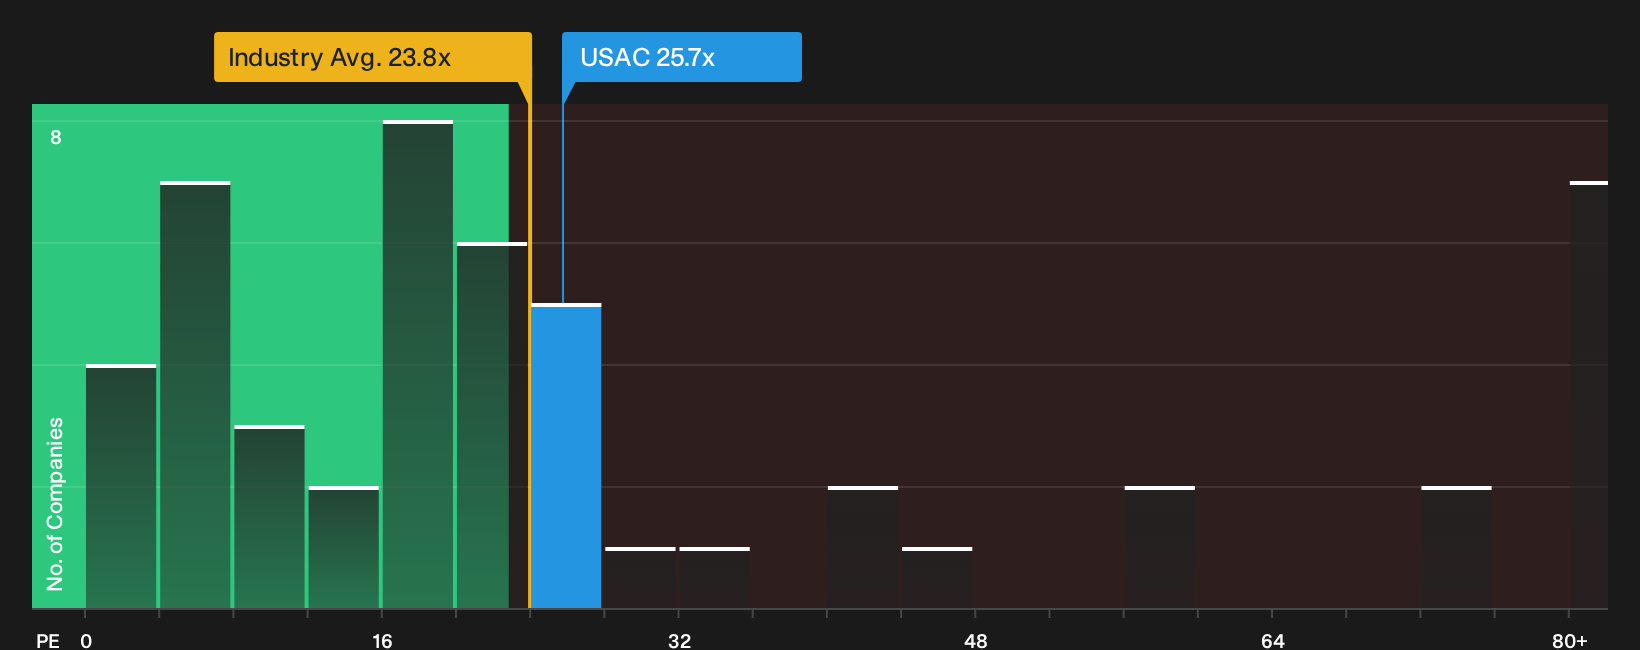
USA Compression Partners might look cheap compared with fair value estimates, yet its 25.7x P/E tells a different story. That multiple is higher than the US Energy Services industry at 24.3x and well above a fair ratio of 20.9x. The gap suggests investors are paying up, so is the margin of safety really as big as it looks?
For a closer look at how this pricing stacks up against peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or a clear message on USA Compression Partners? Act quickly and review the full picture of risks and rewards before deciding where you stand. Start with 3 key rewards and 3 important warning signs.
Looking for more USA Compression Partners sized ideas?
If USA Compression Partners has your attention, do not stop here. Fresh opportunities appear constantly, and you do not want to watch them pass by.
- Target resilient cash generators with strong income potential by scanning the market through 29 high quality undervalued stocks.
- Prioritise balance sheet strength and financial durability by filtering for companies using the list of solid balance sheet and fundamentals (23 results).
- Hunt for lesser known opportunities with solid fundamentals by running the 16 high quality undiscovered gems before the crowd arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com