
3 Export Focused EV Stocks Investors May Want On Watchlists
Global export-focused automakers and EV manufacturers suddenly sit at the crossroads of trade policy, energy routes and rare earth supply, and the Trump-Xi summit plus Iran talks could reshape that mix in a hurry. That creates both openings and tripwires for investors who follow this screener. This article walks through three stocks that appear positively exposed to these headlines and explains why some readers may want them on their watchlist right now.
The three automakers highlighted below are just a starting sample, and the full screen surfaced 168 more companies with equally detailed stories that are not covered in this article. To go deeper into the Global Export-Oriented Automakers and EV Manufacturers idea, analyze, compare and identify your own highest conviction ideas directly inside the Global Export-Oriented Automakers and EV Manufacturers screener.
Yamaha Motor (TSE:7272)
Yamaha Motor plugs neatly into this export-focused automaker and EV-related theme, with motorcycles, marine craft, outdoor vehicles and robotics shipped worldwide, and an increasingly tech-heavy product mix shaping how it earns money across its major businesses.
Yamaha Motor generates most of its revenue from land mobility at ¥1,791,546 million, with marine at ¥548,324 million, outdoor land vehicles at ¥151,127 million, robotics at ¥117,305 million, financial services at ¥123,789 million and other activities at ¥81,781 million. The group is valued at roughly ¥1.77 trillion.
"Yamaha's record R&D spend and strategic focus on integrated energy management, intelligent systems, and connected mobility are positioned to capture demand for electrification, affordable mobility, and recurring digital service revenue in urbanizing and sustainability-focused emerging markets, with the potential to support a long-term step-change in revenue and higher quality recurring cash flows."
What matters now is how one quiet shift in this export mix filters through to pricing power and long-run margins.
That margin puzzle is exactly what the full narrative for Yamaha Motor unpacks, showing where Yamaha Motor’s mix shift, capital spend, and risk profile could be quietly accelerating or stalling.

Aptiv (APTV)
Aptiv plugs into this export-oriented automaker and EV supplier theme through the wiring, sensors, and software that global carmakers rely on for electrified and connected vehicles.
Aptiv develops hardware and software that power advanced safety systems, user experience, and electrical distribution in vehicles worldwide, with Intelligent Systems at about US$5.8b and Engineered Components Group at roughly US$6.8b, and the business is valued around US$9.0b.
"Strong demand for Aptiv's advanced electrical/electronic architectures (including high-voltage and high-speed data connectivity products), driven by the global shift toward electric vehicles and increasingly complex vehicle electrical systems, is supporting robust new business bookings and growth in content per vehicle."
The real test for Aptiv is how one unresolved pressure on future spending by global automakers shapes that content story over time.
That pressure is exactly where the full narrative for Aptiv shows whether Aptiv’s content per vehicle story is quietly accelerating, masking risk, or already decoupling from automaker spending cycles.

Seres GroupLtd (SHSE:601127)
Seres GroupLtd is a Chinese new energy vehicle manufacturer that designs, builds, and sells EVs and key components such as powertrains, batteries, and motors at scale for both domestic and overseas buyers.
The business currently earns about CN¥160.1b from its Automobile Industry segment and carries a market value near CN¥79.9b. This gives Seres GroupLtd meaningful weight inside a screen focused on larger, export-linked EV manufacturers.
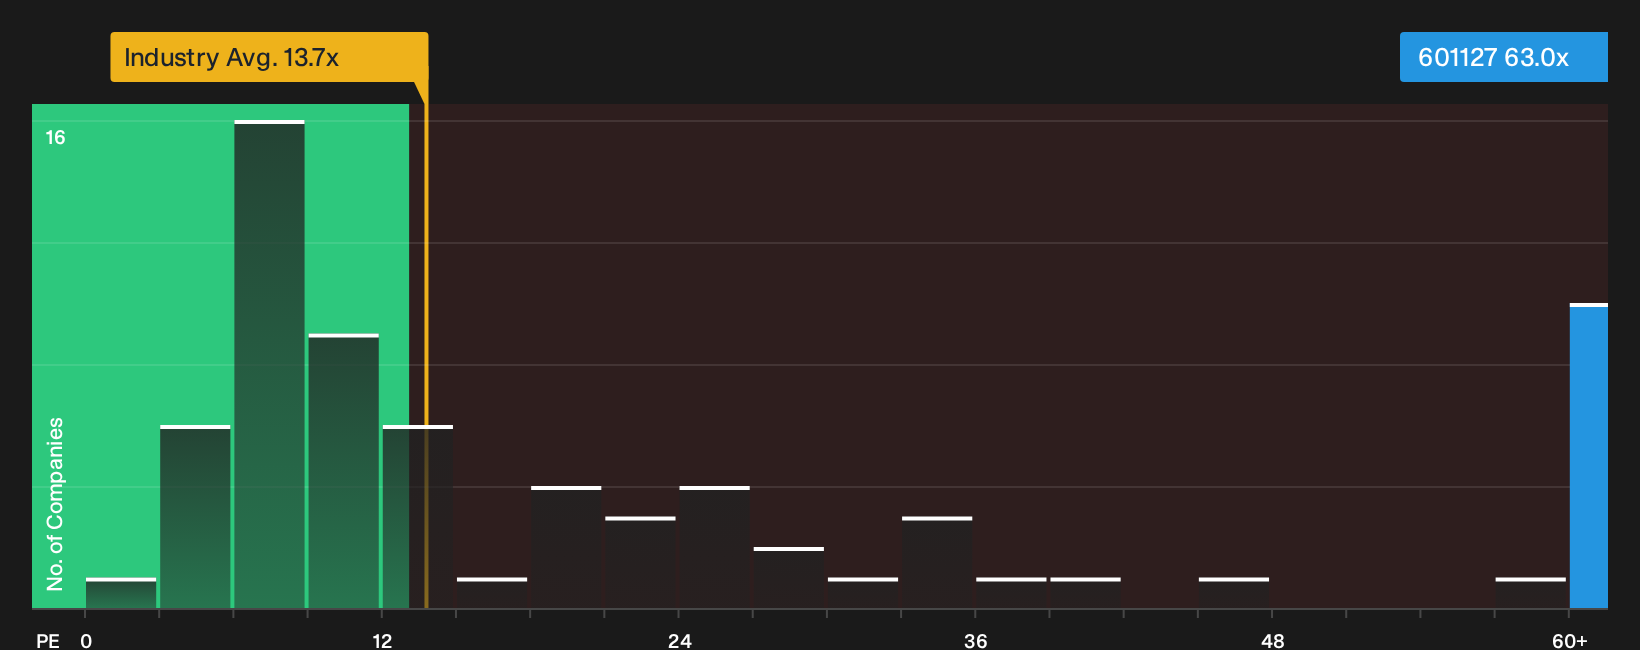
For investors tracking global EV exporters, Seres GroupLtd is a pure-play new energy vehicle producer with international reach and about CN¥160.1b in auto revenue. However, its premium 63x P/E and thin 0.8% net margin mean a lot may depend on how one unseen pressure on future overseas profitability is resolved.
That kind of valuation tension makes it worth scanning the 2 key rewards and 2 important warning signs to see where Seres GroupLtd’s export story could be quietly stretching or cracking.
Curious About Fresh Market Alternatives
Fresh themes can move from quiet to breakout territory fast, and once momentum is flying, ideal entry points can become harder to find before the crowd notices. Consider taking timely action.
- Scan for cash-generating anchors that may steady a portfolio while markets swing by reviewing the list of solid balance sheet and fundamentals (21 results) before it slips off the radar.
- Explore early momentum in infrastructure related to the AI boom and energy transition by checking the curated 39 power grid technology and infrastructure stocks while these ideas are still under the radar for now.
- Evaluate positioning for potential changes in commodity sentiment by assessing the hand-picked miners in the 36 elite gold producer stocks before renewed interest pushes them into the crowd’s view.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com