
Kraft Heinz (KHC) Stock Looks Reasonable As Shares Fell 18%
Kraft Heinz has spent the past few years wrestling with weak share returns and a major reset of its Oscar Mayer business, which puts a fresh spotlight on what investors are actually paying for its sales today. With the stock around US$24, the key issue is how that market price lines up against the revenue base backing the packaged food group.
- Over the past 3 years the Kraft Heinz share price has fallen 17.8%, which makes the current valuation question more about what the existing sales stream is worth than about momentum.
- The overhaul of Oscar Mayer packaging and recipe positioning, along with a US$700 million reinvestment plan running through 2026, can influence how efficiently future sales convert into profit and how much capital the company needs to support its brands.
- The analysts covering Kraft Heinz have run their own numbers. See what analysts think Kraft Heinz's shares could be worth.
The stock's next move may depend on whether Kraft Heinz's current price can be explained by the level and quality of its sales base.
If you want to balance Kraft Heinz's recent share declines against other options, a focused stock screen can help you compare its setup with 29 high quality undervalued stocks.
Does Kraft Heinz Look Undervalued on Sales?
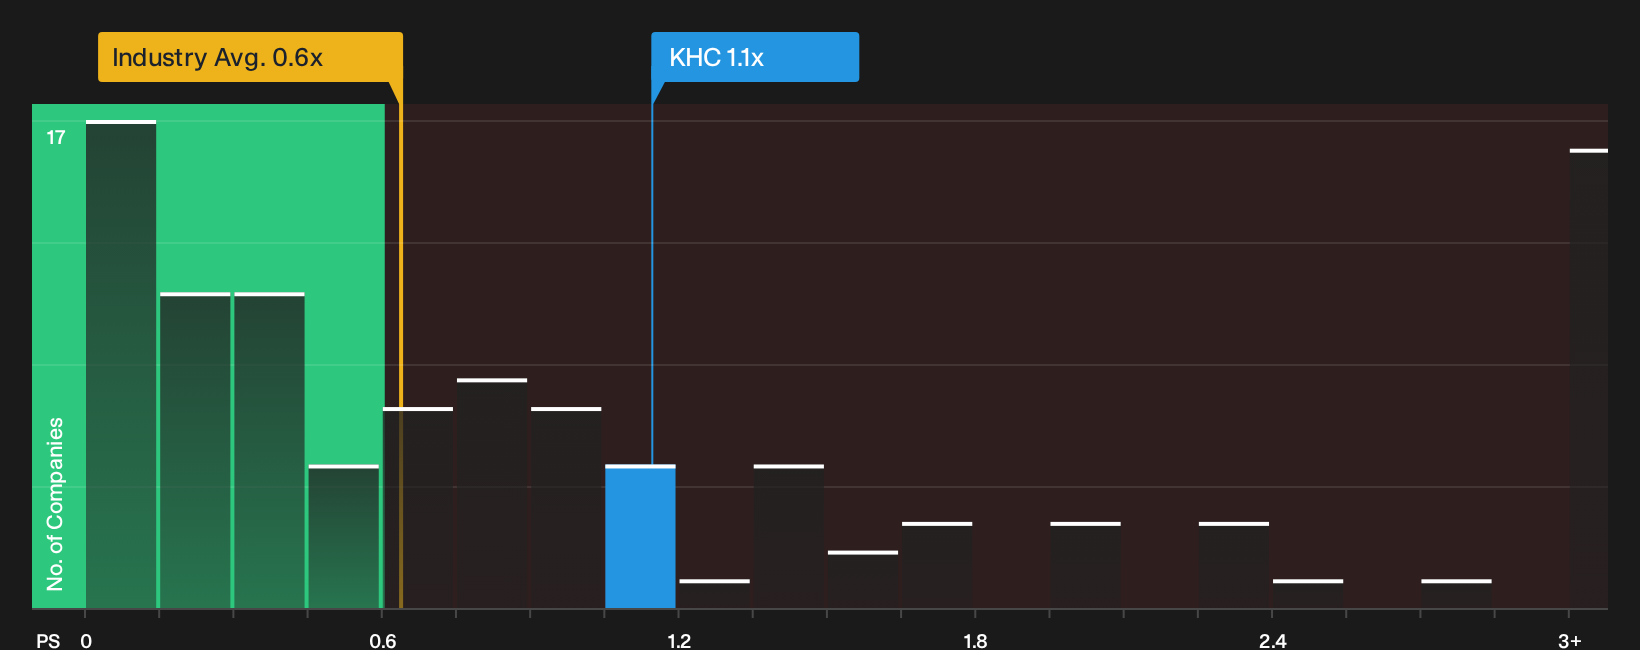
P/S works reasonably well for Kraft Heinz because investors are weighing a mature food portfolio where sales stability often matters more than fast earnings swings. On this measure, the stock trades on a P/S of 1.1x, compared with a food industry average of about 0.6x and a peer group closer to 1.5x. That leaves Kraft Heinz priced above the broad sector on revenue, but not at the top end of more direct competitors.
The fair multiple implied by the valuation model sits above the current 1.1x level. This points to the shares screening as undervalued on this specific yardstick. Because the Oscar Mayer reset and packaging issues have weighed on recent sentiment, a P/S below that tailored fair ratio suggests the market is not placing a full premium on Kraft Heinz’s existing sales base relative to its quality and brand reach. Explore the numbers behind Kraft Heinz's P/S valuation.
The Kraft Heinz Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Kraft Heinz's valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today's price, and by setting out the assumptions behind each fair value view so you can later compare them with Kraft Heinz's reported results as they come through.
Community views on Kraft Heinz split cleanly between investors who see a repair story on a discount and those who think the risks still deserve a markdown.
Bull case: 31% undervalued
"This is not what a dying brand portfolio looks like, it is what a neglected one looks like when somebody starts feeding it again…"
Discover why this Narrative puts Kraft Heinz at 31% undervalued.
Bear case: 26% overvalued
"Shifting consumer trends and rising health regulations threaten the relevance and profitability of Kraft Heinz's heavily processed product portfolio…"
Explore why this Narrative puts Kraft Heinz at 26% overvalued.
Before you act on Kraft Heinz's valuation, there is one more lever to inspect
Price tags and sales ratios only tell part of the story for Kraft Heinz, because the people steering the business and the way their rewards are set can tilt long term outcomes. See who runs Kraft Heinz and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com