
How Investors Are Reacting To Ligand Pharmaceuticals (LGND) Ryjunea Royalty Rights Deal
- Ligand Pharmaceuticals agreed to pay Sydnexis US$23 million upfront to acquire a 100% royalty interest on Ryjunea net sales in Europe, the Middle East, and Africa, while Sydnexis keeps rights to SYD-101 in the U.S. and other territories.
- The Ryjunea royalty deal adds a newly approved pediatric myopia therapy to Ligand Pharmaceuticals' portfolio, expanding its exposure to high-margin, partner-driven revenue streams in licensed international markets.
- This article examines how Ligand Pharmaceuticals' investment narrative is affected by the Ryjunea EMEA royalty acquisition and recurring revenue mix.
Scan how Ligand Pharmaceuticals’ royalty-style model compares with other asset-light opportunities by reviewing our handpicked 16 high quality undiscovered gems in similar high-margin, partnership-driven niches.
Ligand Pharmaceuticals Investment Narrative Recap
To own Ligand Pharmaceuticals, you need to believe its asset light, royalty heavy model can keep turning external drug programs into recurring, high margin income. The near term focus stays on execution from partners behind key assets like O2vir, Filspari, Qarziba and Zelsuvmi. The Ryjunea EMEA royalty deal fits that playbook but does not change it.
The most important short term catalyst still rests on how existing partnered launches perform against expectations and how new royalty deals are integrated without stretching the balance sheet. The biggest risk remains concentration in a handful of products and exposure to drug pricing and regulatory shifts across multiple geographies.
The Ryjunea transaction matters because it slightly broadens Ligand Pharmaceuticals' royalty base into pediatric myopia and adds exposure to EMEA markets. That supports the current catalyst of expanding recurring revenue from partnered drugs while keeping internal R&D lean and relying on capital deployment to refresh the asset pool.
Alongside that, Ligand's participation in the recent Primrose Bio financing reinforces the focus on external platforms that could feed future licensing or royalty streams. For you, the key issue to watch is whether these incremental deals offset the long term risk around pricing pressure, tax exposure and dependence on a relatively small set of high value assets.
Ligand Pharmaceuticals' current analyst narrative points to US$481.1 million in revenue and US$273.9 million in earnings by 2029, based on an assumed 18.3% yearly revenue growth rate and an uptick in profit from US$197.2 million today. This implies roughly a US$76.7 million earnings increase over that period.
Uncover why Ligand Pharmaceuticals' fair value indicates a 15% potential upside to its current price that could narrow quickly.
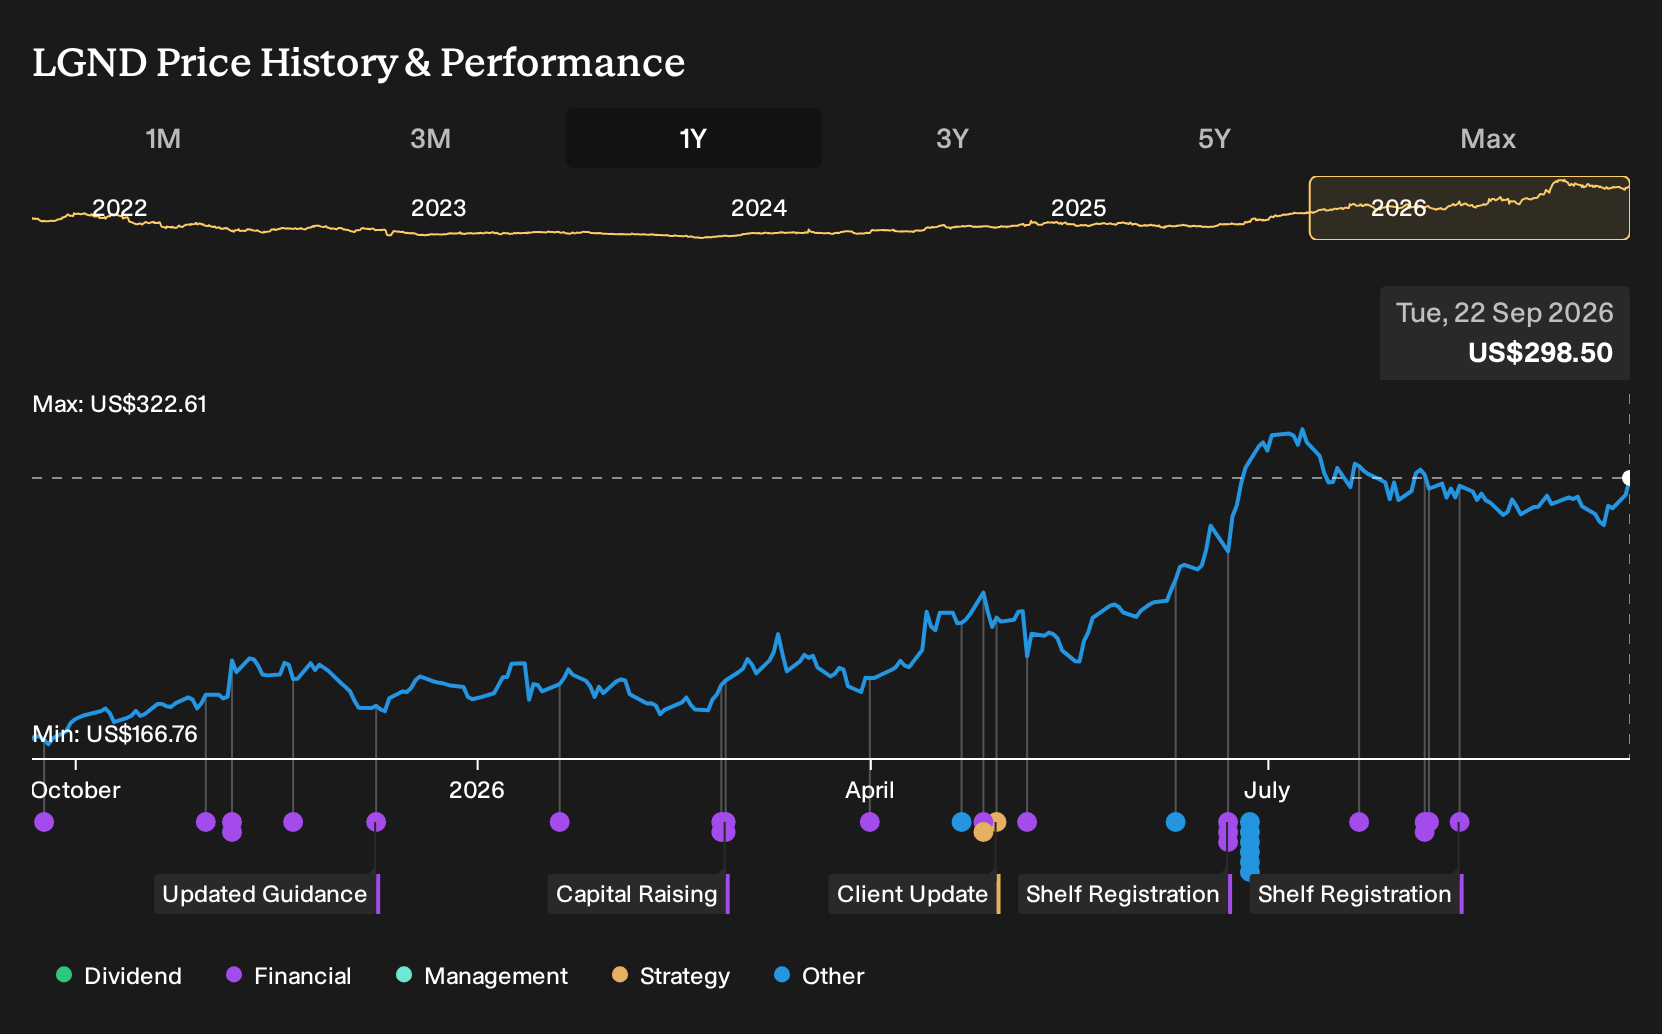
Exploring Other Perspectives
One alternate view puts less weight on new deals like Ryjunea and worries more about execution risk. The most cautious analysts were penciling in 13.4% annual revenue growth to about US$424.0 million and earnings of US$255.2 million by 2029, which is below the consensus path. The takeaway is simple: opinions on Ligand Pharmaceuticals can differ widely, and this royalty acquisition could prompt analysts on both sides to revisit those earlier forecasts.
Explore another Ligand Pharmaceuticals fair value estimate, including one that suggests it could be worth just $342.82.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ligand Pharmaceuticals research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ligand Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ligand Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ligand Pharmaceuticals?
Once you have formed a view on Ligand Pharmaceuticals, it can help to compare its royalty driven story with other businesses that share traits you care about, whether that is value, resilience, or income.
- If you want potential value opportunities with strong fundamentals, review our hand picked 29 high quality undervalued stocks that may warrant a closer look alongside Ligand Pharmaceuticals in your watchlist.
- For investors who care about balance sheet strength first, scan the list of solid balance sheet and fundamentals (23 results) to see which other businesses keep financial risk contained while funding their growth plans.
- If you prefer to keep volatility in check, compare Ligand Pharmaceuticals with the 30 resilient stocks with low risk scores that score well on our risk filters and may offer a smoother ride through market swings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com